Why Silicon Valley Bank’s crisis is rattling America’s biggest banks

Why Silicon Valley Bank’s crisis is rattling America’s biggest banks

The issues of two tiny financial institutions on the West Coast are rippling across marketplaces and producing new investor issues about some of the country’s largest fiscal establishments.

Why? A few words and phrases: increasing desire fees.

The Federal Reserve’s intense campaign to bring down inflation served set the phase for major troubles at two California lending institutions — SVB Financial (SIVB) and Silvergate Capital (SI) — as an outflow of deposits pressured both to provide property at a decline. These belongings ended up bonds.

Banks are huge traders in belongings like Treasury payments simply because they have to have tons of secure areas to park their dollars. Lots of money establishments piled into these investments through a interval of historically-very low fascination rates that spanned the early yrs of the pandemic, as banking companies took in tons of new deposits and lending was considerably restrained.

But now the Fed is mountaineering fees at a immediate clip, with Fed Chair Jay Powell warning earlier this 7 days the central bank could have to velocity up the tempo of its price improves to cool the financial system further more. The challenge that makes for financial institutions is easy: increased costs decreased the benefit of their current bonds.

The withdrawals at SVB’s Silicon Valley Financial institution have arrive from startups and technologies companies, several of which also ran into new issues at the time the Fed commenced boosting fees.

The deposit outflow compelled SVB to provide belongings and take a $1.8 billion decline, a go the bank produced “because we anticipate continued larger curiosity fees, pressured general public and personal marketplaces, and elevated hard cash-burn up degrees from our clientele as they make investments in their companies.” Its shares fell extra than 60{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} Thursday.

In pre-market place trading on Friday, SVB shares had been down a different 60{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} after overnight reporting from Bloomberg reported VC companies ranging from Peter Thiel’s Founders Fund to Union Sq. Ventures experienced informed portfolio corporations to pull their funds from Silicon Valley Lender.

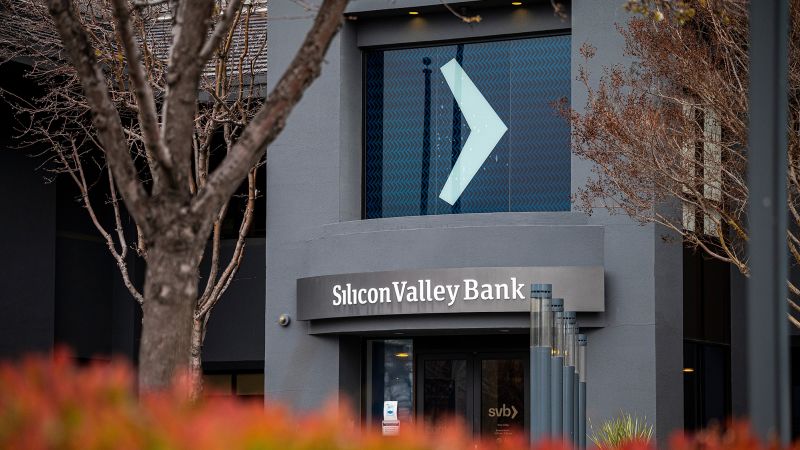
Silicon Valley Bank headquarters and branch in Santa Clara on Aug 7, 2019.

Silicon Valley Bank headquarters and branch in Santa Clara on Aug 7, 2019.

Forced sales, forced losses

Banks never have to comprehend losses on bonds that may have gone down in price amid growing charges if they are not pushed to offer these property. But Silvergate Money and SVB Fiscal did not have that alternative. Buyer withdrawals at Silvergate Financial institution and SVB’s Silicon Valley Financial institution forced their hand.

At Silvergate, which caters to cryptocurrency shoppers, clients yanked their income in the worry that adopted the 2022 collapse of cryptocurrency exchange FTX. Silvergate stated in January that it had recognized losses of $886 million from providing securities as deposits fell. That weakened the bank substantially. On Wednesday it reported it would wind down its lender, and its shares plunged Thursday.

Soon after disclosing the $1.8 billion decline and new funds elevate, Silicon Valley’s CEO Greg Becker urged relaxed in a get in touch with with enterprise capitalists Thursday, in accordance to The Information, inquiring these traders not to withdraw cash. It now is in search of to increase $2.25 billion of new funds to address the new losses.

Greg Becker, President and CEO at SVB speaks  at the 2022 Milken Institute Global Conference in Beverly Hills, California, U.S., May 3, 2022.  REUTERS/Mike Blake

Greg Becker, President and CEO at SVB speaks at the 2022 Milken Institute Worldwide Meeting in Beverly Hills, California, U.S., Could 3, 2022. REUTERS/Mike Blake

The problem now among the buyers is that considerably even bigger banking institutions could be forced to do the exact same. That despatched the stocks of big economical establishments tumbling Thursday, like the biggest of the major: JPMorgan Chase (JPM) and Lender of The united states (BAC). A major financial institution index fell by the most Thursday in virtually three several years.

The most significant U.S. banking institutions are considerably stronger than they were being in the direct up to the final big banking crisis, in 2008, in component for the reason that regulators forced them to hold much more money and endure numerous stress examination eventualities above the very last ten years and a fifty percent. And the giants have far more numerous funding and buyer bases than financial institutions these kinds of as Silicon Valley or Silvergate, which provides them many more possibilities during tough times.

Longtime banking analyst Mike Mayo claimed Thursday all through an visual appeal on CNBC the most significant financial institutions are “a pillar of power and balance” and considerably a lot more resilient than they were prior to the 2008 disaster. “The most important threats are outside the house the major banking companies,” he mentioned, and still all banking institutions are “obtaining painted with the similar brush.”

Financial institution shares, he said, “have gotten Powelled,” referring to the Fed chair.

“Likely from zero to 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} curiosity premiums in a period that is more quickly than any time in 4 a long time, you are heading to have casualties.”

WASHINGTON, DC - SEPTEMBER 09:  Federal Deposit Insurance Corporation Chairman Martin Gruenberg testifies during a hearing before Senate Banking, Housing and Urban Affairs Committee September 9, 2014 on Capitol Hill in Washington, DC. The committee held a hearing on

Federal Deposit Insurance plan Corporation Chairman Martin Gruenberg recently highlighted the risks that rising curiosity charges pose to banks. (Picture by Alex Wong/Getty Images)

Federal Deposit Insurance plan Corporation Chair Martin Gruenberg highlighted the new interest charge risks struggling with the sector all through a speech on March 6, noting that unrealized losses on readily available-for-sale and held-to-maturity securities totaled $620 billion at the stop of 2022 across all U.S. financial institutions.

“The present curiosity level surroundings has experienced extraordinary effects on the profitability and risk profile of banks’ funding and financial commitment methods,” he reported. “Initial, as a final result of the larger fascination fees, for a longer period phrase maturity assets obtained by banks when desire rates were being lessen are now really worth a lot less than their face values. The consequence is that most banks have some sum of unrealized losses on securities.”

These unrealized losses, he included, “weaken a bank’s foreseeable future skill to meet surprising liquidity requirements.”

The fantastic news, in accordance to Gruenberg, is that “banking institutions are typically in a potent fiscal problem, and have not been pressured to know losses by advertising depreciated securities.”

Click below for the most up-to-date inventory marketplace news and in-depth evaluation, which include gatherings that transfer shares

Read through the most recent economic and enterprise news from Yahoo Finance

Automotive Cybersecurity Market Size to Worth USD 16.43 BN by 2032

Automotive Cybersecurity Market Size to Worth USD 16.43 BN by 2032
Precedence Research

Precedence Research

The global automotive cybersecurity market size is expected to be worth around USD 16.43 billion by 2032, and it is registering at a CAGR of 18.15{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from 2023 to 2032.

Ottawa, March 11, 2023 (GLOBE NEWSWIRE) — As per Precedence Research, the global automotive cybersecurity market size was valued at USD 3.1 billion in 2022. The most recent developments in connected and autonomous vehicles, as well as the rising number of electronic control units (ECUs) in electric vehicles, are driving the expansion of the automotive cybersecurity industry. Due to new manufacturing techniques and consumer-challenging technology, the automotive industry is facing a rapid revolution in cyber security that is being fueled by socioeconomic and environmental changes.

Report Highlights:

  • Asia Pacific region has accounted revenue share of 37{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2022.

  • By vehicle type, the electric vehicle (EV) segment is poised to grow at a CAGR of 29{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} between 2023 to 2032.

  • By security type, the wireless network security segment has generated revenue share of 43{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2022.

  • By security type, the application security has held revenue share of 35{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2022.

  • By application, the infotainment segment has contributed revenue share of 37{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2022.

  • By application, the ADAS & safety system segment is growing at a notable CAGR of 22{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from 2023 to 2032.

Get the sample pages of report@ https://www.precedenceresearch.com/sample/2676

Market Overview

Cybersecurity is the defence against malicious assaults, damage, unauthorized access, and manipulation of automobile electronic systems, communication networks, control algorithms, software, users, and underlying data. The market for automotive cybersecurity is expanding as a result of rising demand for automotive cybersecurity solutions brought on by a rise in cyberattacks on the car industry. Cybercrime is on the rise, and it is anticipated that customer comprehension of information security will result in lucrative business opportunities. As a result, owners and organisations are urged to put automotive cybersecurity safeguards in place, which is what propels the sector.

The development of connected cars and the enforcement of vehicle data security regulations by regulatory bodies are expected to fuel further market expansion.

Regional Insights

Asia Pacific held 37{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of the market in 2022 and is anticipated to continue expanding over the course of the forecast period. The number of cyberattacks has been rising steadily across APAC. Yet, a lack of security measures and the rising popularity of work-from-home policies have led to a rapid increase in cyberattacks. The two most prevalent kinds of cyberattacks are malware and ransomware assaults. The number of malware and ransomware attacks in APAC nations is still 1.6 times greater than worldwide. During 2018, ransomware assaults have increased in frequency across the globe. Cyberattacks on the auto industry have become more frequent as connected cars and digitization have proliferated. These attacks target the car and compromise crucial vehicle data, causing owners to incur significant losses.

Ask here for customization study@ https://www.precedenceresearch.com/customization/2676

Scope of this report

Report Coverage

Details

Market Size in 2032

USD 16.43 Billion

Asia Pacific Revenue Share

37{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2022

Infotainment Segment Share

37{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2022

Wireless Network Security Segment Share

43{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2022

Key Players

Vector Informatik GmbH, NXP Semiconductors N.V., Harman International, Broadcom Inc., Denso Corporation, Sheelds, Honeywell International, Inc., Continental AG, Guard Knox Cyber-Technologies Ltd., Robert Bosch GmbH and Others

Report Highlights

Based on vehicle type, commercial vehicles, personal vehicles, and electric vehicles can all be classified as segments of the market (EV). The EV category dominated the market in 2022 and is expected to grow in the near future. The market has grown as a result of more people becoming aware of economic development and the downsides of operating hybrid automobiles. In addition, a few of municipal governments are providing subsidies to encourage the purchase of electric cars in anticipation of greater infrastructure development.

Based on security insights, security for endpoints, applications, and wireless networks are the market segments. With a majority of the market share in 2022, wireless network security dominated the market. During test runs, the Wi-Fi-based wireless technology enables automotive professionals to concurrently monitor hundreds of data channels to track vehicle operational parameters and modify the test as it is being carried out. A modern vehicle incorporates numerous information-sharing networks, including wireless channels, to enable a variety of application scenarios.

Based on application, ADAS & safety system, infotainment, body electronics, powertrain, and telematics are the several market segments for car cyber security. With a highest market share the infotainment section was the market leader. Throughout the forecast period, this segment is anticipated to increase significantly.

The whole automotive industry is working to develop cutting-edge technology to give better connectivity options, increase vehicle safety, and enhance the in-car user experience. The “In-Vehicle Infotainment System” is one of the key technologies that serves as the focal point of all modern automobile systems, integrating their operations so they can be managed and monitored from a single central unit.

Based on form, in 2022 the in-vehicle sector dominated the market. In-car-connected services are technologies that make it possible to connect internal vehicle systems to those found in remote locations or external systems. The modern vehicle’s most connected component due to its mobile connectivity. Car Makers have had to adjust to changing consumer demands, which has resulted in ever-more-advanced technologies.

Also, external cloud services are growing at the fastest rate due to improvements in cloud infrastructure and framework. Cloud services offer a very dependable technology, especially given the volume of data produced by driverless vehicles. Moreover, cloud technology will lead to a faster rate of information transfer as the number of cars and devices connected to the cloud rises.

Market Dynamics

Driver

Increase in need for automotive cybersecurity

The rising connectedness of vehicles to everything, including traffic signals, parking metres, other vehicles, and much more, is altering the automotive industry. The employment of new technologies is prevalent, with electrified vehicles, shared mobility, self-driving cars, and advanced driver assistance systems (ADAS) among them (EV). These technologies not only increase comfort and safety on the roads, but they also leave this complex and dynamic environment vulnerable to intrusions. As the ecosystem becomes increasingly integrated, attack points increase, exposing new vulnerabilities that hackers might employ to jeopardise user privacy, car safety, and the integrity of automotive data. The Upstream Security Automotive Cybersecurity Report 2020, produced by an Israeli cybersecurity business, provided in-depth analyses and statistics based on an examination of 633 events that were widely reported since 2010, of which 207 occurred in 2019.

Restraint

Growing diversity in the automotive domain along with the rising complexity of the security software

Due to the large range of automobile types and the numerous applications that can operate within a car, the automotive industry is growing more and more diverse. The variety and complexity of automotive cyber security systems increase as there are more manufacturers of automotive solutions. The market’s growth will be constrained by the inescapable rise in installation and maintenance costs for vehicle cyber security systems as complexity develops.

Opportunity

Enhancing vehicle security using adaptive security

Adaptive security is a type of cybersecurity system that looks at events and actions to stop and prepare for threats before they happen. A business can utilise an adaptive security architecture to provide proportional enforcement that can be increased or decreased while continuously analysing risk. With adaptive security, which many automobiles manufacturers lack throughout their operations, it is simple to defend a dispersed workforce.

Adaptive security uses analytics and automation to protect against targeted and opportunistic cyberattacks, as well as trusted insiders and other insider threats. Adaptive security also safeguards an automaker’s ecosystem, which is growing every day as a result of connected car activities. Hence, it is anticipated that an increase in adaptive security in the automotive industry will fuel growth of the global automotive cybersecurity market during the forecast period.

Challenge

Discrepancies related to pricing strategies among stakeholders

Due to the introduction of ancillary services like multimedia streaming Ecalls and remote diagnostics within connected cars, the entire ecology of the automotive industry is changing. The automobile ecosystem has evolved from being fixed to being dynamic, with each actor accounting for a portion of the revenue. The linked ecosystem’s pricing model has proven challenging to implement due to the presence of various players. With different pricing strategies, many firms struggle to strike a balance between complexity and expense. Currently, software companies utilise a variety of pricing models to make money. Experts in the area claim that cybersecurity solution providers struggle to implement the night pricing plan to boost profitability and decrease missed chances in a range of circumstances.

Recent Developments

  • In July 2021, in its EVlink line of electric vehicle charging stations, Schneider Electric fixed security issues that may have allowed DoS attacks.

  • In August 2021, Upstream, an automobile firm, raised $62 million in a Series C round to increase the scope of its cloud-based security offerings.

Market Segmentation

By Security Type 

By Vehicle Type 

  • Passenger Car

  • Commercial Vehicle

  • Electrical Vehicle

By Application 

  • ADAS & Safety System

  • Infotainment

  • Body Electronics

  • Powertrain

  • Telematics

By Form 

  • In-Vehicle Services

  • External Cloud Services

By Geography

Immediate Delivery Available | Buy This Premium Research Report@ https://www.precedenceresearch.com/checkout/2676

You can place an order or ask any questions, please feel free to contact at sales@precedenceresearch.com  | +1 9197 992 333

About Us

Precedence Research is a worldwide market research and consulting organization. We give unmatched nature of offering to our customers present all around the globe across industry verticals. Precedence Research has expertise in giving deep-dive market insight along with market intelligence to our customers spread crosswise over various undertakings. We are obliged to serve our different client base present over the enterprises of medicinal services, healthcare, innovation, next-gen technologies, semi-conductors, chemicals, automotive, and aerospace & defense, among different ventures present globally.

For Latest Update Follow Us:

https://www.linkedin.com/company/precedence-research/

https://www.facebook.com/precedenceresearch/

https://twitter.com/Precedence_R

England suffer historic humiliation after France’s Twickenham tour de force | Six Nations 2023

England suffer historic humiliation after France’s Twickenham tour de force | Six Nations 2023

Talk about a guillotine falling with brutal finality. England have endured some chastening days over the years but nothing on the scale of this record thumping by France, who had previously failed to win a Six Nations game in south-west London since 2005. If the home side were nowhere near good enough, Les Bleus were quite outstanding for the majority of a one-sided contest.

By the end even England’s worst ever day at Twickenham, the 42-6 thrashing by South Africa in 2008, was receding in the rear view mirror. Steve Borthwick’s squad had dared to hope this might be the weekend they glimpsed a brighter future coming over the horizon. Instead it proved to be the headlights of a speeding French TGV, smashing aside everything in its path.

The visitors, clearly fuelled by a desire to right a few historic wrongs, scored seven tries in all, with Thibaud Flament, Charles Ollivon and Damian Penaud each bagging two. In many ways this was an even more eye-catching Gallic triumph than their famous 51-0 demolition of Wales at Wembley in 1998 and this autumn’s Rugby World Cup in France cannot now come swiftly enough for them.

But whither England? Where to start. On a damp, rainy evening their ambitions of playing expansive rugby were cruelly exposed by opponents who possessed loads more power and panache. It would be harsh to blame Marcus Smith for all the other glaring deficiencies around him but England’s wet weather tactics were often questionable and their supposed new attacking dawn never remotely materialised.

England’s biggest problem was right in front of their noses. Collision-wise they were blown away and France also looked the fitter side. By the end, with the red rose defence being breached almost at will, the gulf between the teams was embarrassing. One French newspaper described it as “a massive kick up the backside” and that it was.

When paired with Friday night’s 42-7 defeat to France at under-20 level, this result should also finally kill off any lingering English delusions of grandeur. “We know what the reality is now,” muttered Borthwick, making no attempt to gloss over the blatantly obvious. Play as ineffectually as this in Dublin next week and another lower-half championship finish will tell its own stark story.

Thibaud Flament scores his side's fourth try whilst under pressure from England’s Alex Dombrandt during the Guinness Six Nations Rugby match between England and France.
Thibaud Flament scores his side’s fourth try whilst under pressure from England’s Alex Dombrandt. Photograph: Tom Jenkins/The Observer

France, on the other hand, played as if it was Paris in the springtime rather than late winter in south-west London. More effective at the breakdown, more composed when it mattered and stronger in pretty much every other department, rumours of their demise as World Cup favourites have clearly been exaggerated.

They were 10 points up inside the first seven minutes, their young wing Ethan Dumortier intelligently drawing the last defender to allow Thomas Ramos to finish a move he had helped to start. Even before the top scorer in this season’s Six Nations added the conversion and a subsequent penalty it was already clear France were in no-nonsense mood, with the returning Jonathan Danty’s turnover ability among their most conspicuous plusses.

Quick Guide

How do I sign up for sport breaking news alerts?

Show

  • Download the Guardian app from the iOS App Store on iPhone or the Google Play store on Android by searching for ‘The Guardian’.
  • If you already have the Guardian app, make sure you’re on the most recent version.
  • In the Guardian app, tap the Menu button at the bottom right, then go to Settings (the gear icon), then Notifications.
  • Turn on sport notifications.

Thank you for your feedback.

It was no real surprise to anyone when France scored again, the ever-dangerous Antoine Dupont having given them an excellent platform with a sweet left-footed 50-22 kick. The visiting pack immediately scented rosbif blood and Flament, once a fly-half at Loughborough University, galloped unstoppably between both English centres to leave the hosts staring at a 17-0 deficit.

skip past newsletter promotion

Not until the 34th minute did England even make it on to the scoreboard and another in a series of costly knock-ons, this time from Alex Dombrandt, gifted the visitors another try-scoring opportunity on the stroke of half-time. If the dummy run of Penaud played some part in fooling the English blindside defence it was impossible not to admire the strength and skill of Grégory Alldritt as he stormed clear to put the supporting Ollivon over for France’s third try.

England had trailed by more than 24 at the interval only three times in their history, all in the southern hemisphere. At Twickenham in 2006 they trotted back after trailing 28-5 to New Zealand, going on to lose 41-20, but nowhere have they endured a championship humiliation like this.

Something had to change and Borthwick sent on Owen Farrell and Alex Mitchell for Henry Slade and Jack van Poortvliet in a vain attempt to staunch the bleeding. In truth, though, England could have changed half a dozen players without addressing the central issue. France were boulevards ahead in terms of gainline punch and cohesion and, even when Max Malins appeared to have scored from a nice cross-kick from Smith, the officials ruled the ball had not been grounded legally.

Freddie Steward did partially redress the balance with a 48th-minute score that pegged it back to 27-10 but it was to be the high point of England’s evening. First a kind bounce from Dupont’s chip allowed Ramos to put the impressive Flament over for his second try before Smith, under pressure on his own line, was scragged and dragged backwards, with the predatory Ollivon claiming the touchdown. Long before Penaud and friends further twisted the knife, dismayed home supporters could be seen heading for the exits, trying vainly to remember a more savage Twickenham denouement.

Silicon Valley Bank collapses after failing to raise capital

Silicon Valley Bank collapses after failing to raise capital


New York
CNN
 — 

Silicon Valley Bank collapsed Friday early morning immediately after a stunning 48 hours in which a financial institution operate and a capital disaster led to the next-premier failure of a money establishment in US background.

California regulators closed down the tech financial institution and put it below the regulate of the US Federal Deposit Insurance coverage Company. The FDIC is acting as a receiver, which usually implies it will liquidate the bank’s property to pay back back again its customers, including depositors and collectors.

The FDIC, an unbiased federal government agency that insures financial institution deposits and oversees economic institutions, said all insured depositors will have complete accessibility to their insured deposits by no later than Monday early morning. It mentioned it would pay out uninsured depositors an “advance dividend inside the following 7 days.”

The bank, earlier owned by SVB Financial Team, did not reply to CNN’s request for comment.

The wheels began to appear off on Wednesday, when SVB introduced it had marketed a bunch of securities at a reduction and that it would provide $2.25 billion in new shares to shore up its balance sheet. That brought on a panic among the essential venture capital companies, who reportedly recommended corporations to withdraw their money from the lender.

The company’s stock cratered on Thursday, dragging other banks down with it. By Friday early morning, SVB’s shares ended up halted and it experienced abandoned efforts to quickly elevate funds or come across a buyer. Numerous other financial institution shares ended up temporarily halted Friday, which includes Very first Republic, PacWest Bancorp, and Signature Lender.

The mid-morning timing of the FDIC’s takeover was noteworthy, as the agency commonly waits till the market place has closed to intervene.

“SVB’s situation deteriorated so quickly that it could not very last just five a lot more several hours,” wrote Much better Marketplaces CEO Dennis M. Kelleher. “That’s due to the fact its depositors had been withdrawing their income so quickly that the financial institution was bancrupt, and an intraday closure was unavoidable due to a common bank run.”

Silicon Valley Bank’s drop stems partly from the Federal Reserve’s intense desire amount hikes around the past year.

When curiosity premiums were being close to zero, banking companies loaded up on lengthy-dated, seemingly low-hazard Treasuries. But as the Fed raises desire prices to fight inflation, the price of all those belongings has fallen, leaving financial institutions sitting down on unrealized losses.

Higher prices strike tech primarily really hard, undercutting the value of tech stocks and earning it rough to raise cash, Moody’s chief economist Mark Zandi said. That prompted many tech firms to attract down the deposits they held at SVB to fund their operations.

“Higher rates have also lowered the value of their treasury and other securities which SVB desired to fork out depositors,” Zandi stated. ” All of this set off the run on their deposits that pressured the FDIC to takeover SVB.”

Deputy Treasury Secretary Wally Adeyemo on Friday sought to reassure the public about the wellness of the banking method soon after the unexpected collapse of SVB.

“Federal regulators are spending focus to this certain fiscal institution and when we believe about the broader money system, we’re quite self-assured in the skill and the resilience of the process,” Adeyemo explained to CNN in an exclusive interview.

The opinions arrive following Treasury Secretary Janet Yellen convened an unscheduled assembly of money regulators to go over the implosion of Silicon Valley Lender, a main loan company to the hurting tech sector.

“We have the applications that are necessary to [deal with] incidents like what is transpired to Silicon Valley Bank,” Adeyemo explained.

Adeyemo explained US officers are “learning extra information” about the collapse of Silicon Valley Financial institution. He argued the Dodd-Frank monetary reform overhaul, signed into legislation in 2010, has given regulators the equipment they have to have to deal with this and improved the capitalization of financial institutions.

Adeyemo declined to predict what, if any, influence there will be to the broader overall economy or the tech marketplace.

Despite preliminary stress on Wall Avenue over the operate on SVB, which brought about its shares to crater, analysts stated the bank’s collapse is not likely to set off the type of domino outcome that gripped the banking business during the money crisis.

“The program is as properly-capitalized and liquid as it has ever been,” Zandi stated. “The banks that are now in trouble are significantly too modest to be a significant risk to the broader system.”

But scaled-down financial institutions that are disproportionately tied to cash-strapped industries like tech and crypto may be in for a tough journey, according to Ed Moya, senior industry analyst at Oanda.

“Everyone on Wall Avenue realized that the Fed’s fee-hiking campaign would finally break anything, and ideal now that is having down tiny banking companies,” Moya said.

Although somewhat mysterious exterior of Silicon Valley, SVB was amid the best 20 American business banks, with $209 billion in full assets at the finish of final year, in accordance to the FDIC.

It is the most significant loan company to fall short considering the fact that Washington Mutual collapsed in 2008.

The bank partnered with virtually 50 percent of all enterprise-backed tech and wellness treatment providers in the United States, several of which pulled deposits out of the lender.

Mike Mayo, Wells Fargo senior lender analyst, said the disaster at SVB may perhaps be “an idiosyncratic problem.”

“This is evening and working day compared to the worldwide economic disaster from 15 decades ago,” he informed CNN’s Julia Chatterly on Friday. Back then, he stated, “banks had been getting extreme threats, and people today imagined anything was wonderful. Now everyone’s worried, but beneath the area the financial institutions are a lot more resilient than they’ve been in a generation.”

SVB’s unexpected fall mirrored other dangerous bets that have been exposed in the past year’s sector turmoil.

Crypto-centered financial institution Silvergate said Wednesday it is winding down functions and will liquidate the financial institution following remaining fiscally pummeled by turmoil in digital belongings. Signature Lender, another financial institution, was strike tough by the lender selloff, with shares sinking 30{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} ahead of remaining halted for volatility Friday.

“SVB’s institutional problems replicate a more substantial and additional popular systemic issue: The banking market is sitting on a ton of reduced-yielding assets that, many thanks to the past 12 months of price raises, are now far underwater — and sinking,” wrote Konrad Alt, co-founder of Klaros Team.

Alt believed that price will increase have “effectively wiped out close to 28{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of all the capital in the banking business as of the finish of 2022.”

The Fed Just Jammed Another Wrench Into the Housing Market

The Fed Just Jammed Another Wrench Into the Housing Market

On the precipice of the hotly predicted spring housing industry, the U.S. Federal Reserve just dealt homebuyers a further crushing blow.

Jerome Powell, chair of the Federal Reserve, instructed Congress on Tuesday that much more intense fascination prices may be necessary to awesome inflation. And when house loan curiosity rates are independent from the Fed’s limited-time period prices, they usually adhere to the very same trajectory. Those people better prices have strike homebuyers where by it hurts: their budgets.

In reaction to Powell’s comments, mortgage fees strike 7.03{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} for 30-yr fixed-amount loans on Tuesday afternoon, according to Mortgage News Everyday. Those people higher costs are mainly liable for today’s potential buyers shelling out more than 50{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} a month in their property finance loan payments than they would have a yr back.*

“That’s a bummer for purchasers who had their hopes elevated that fees would be falling,” claims Real estate agent.com® Main Economist Danielle Hale. “It’s heading to be a much more complicated spring than some folks were being expecting.”

A lot less than two months ago, there was speculation prices would drop below 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. Prospective buyers experienced returned to the market place, and bidding wars had heated up again. But the increased charges could threaten the rebound.

“It will continue to be a damper on how a lot house consumers can manage. Sellers are likely to need to be aware of that,” states Hale. “There are likely going to be less purchasers in the current market, and the consumers who are in the industry most likely won’t be able to bid as large as they would have more than the final several decades.”

An maximize of even a solitary share stage can incorporate up to a whole lot of revenue over the daily life of the home finance loan mortgage. For example, the variance between 6.03{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and 7.03{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} equals a $219 increase in a buyer’s month to month property finance loan payment for a median-priced dwelling. That provides up to approximately $79,000 about the lifestyle of a 30-year financial loan. (This assumes a 20{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} down payment on a home with the national median selling price of $414,950 in February, in accordance to the most the latest Real estate agent.com knowledge.)

In the short phrase, Hale expects prices will bounce in between the substantial 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 7.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} selection. She does not anticipate they will prime 8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.

“It’s likely to be a more difficult spring than some people ended up expecting,” claims Hale.

There is a vivid location in the fiscal marketplaces, although, that could continue to keep a lid on costs. When the stock market place is unstable, or falls like it did on Tuesday, far more traders sink their money into U.S. Treasury bonds and home loan-backed securities, aka property finance loan bonds, which are perceived to be safer investments. The securities are bundles of mortgages that loan companies sell to buyers to free up capital to make new financial loans.

When there is more need for house loan bonds, like there was immediately after Powell’s responses on Tuesday, selling prices for bonds enhance. And then mortgage loan prices generally slide.

Though greater fees may well slow the spring market, they are not predicted to quit it in its tracks.

“It may delay the restoration in the housing market place that we experienced started out to see,” states Hale. “But I really do not believe points will get even worse from below. It will just consider more time to achieve momentum at the rear of that rebound.”

* The calculation makes use of the countrywide median record costs in February 2023 compared with February 2022 for properties where by the buyer has put down 20{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. It also variables in common mortgage loan charges on March 7, 2023, compared with March 8, 2022, applying Property finance loan News Every day info for 30-calendar year preset-amount financial loans. It does not include things like residence taxes, owners insurance plan, or other costs.

Biden administration gutting online education with new ‘harmful’ guidance, warn experts, lawmakers

Biden administration gutting online education with new ‘harmful’ guidance, warn experts, lawmakers

The Biden administration will now be able to crack down on private companies that contract with colleges and universities to help the schools run their online education programs, raising alarm bells among experts and lawmakers who warned the federal government could stifle remote learning for students.

The Education Department issued guidance last month saying online program managers (OPMs), which are outside contractors that recruit students for and operate schools’ online academic programs, are officially considered third-party servicers, or entities involved with the administration of “any aspect” of an institution’s federal student financial aid.

As a result, these companies can be subjected to stricter federal oversight in a manner that, critics argue, will hurt not only the schools and contractors, but also ultimately the students they serve.

One of the most prominent critics of the department’s new guidance is Rep. Virginia Foxx, R-N.C., chairwoman of the House Committee on Education and the Workforce.

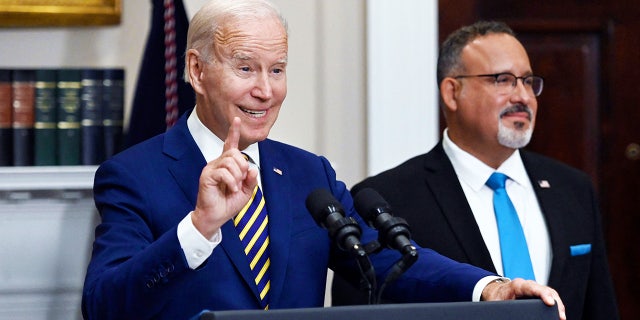
President Biden with Education Secretary Miguel Cardona, right, on Aug. 24, 2022 in the Roosevelt Room of the White House in Washington, D.C.

President Biden with Education Secretary Miguel Cardona, right, on Aug. 24, 2022 in the Roosevelt Room of the White House in Washington, D.C. (OLIVIER DOULIERY/AFP via Getty Images)

GOP SENATORS ACCUSE EDUCATION DEPARTMENT OF ALLOWING ‘TAXPAYER-FUNDED ANTISEMITISM’ ON COLLEGE CAMPUSES

“The growth of technology and its applications in providing students with a well-rounded education is exciting and should be commended,” Foxx told Fox News Digital. “More options for students mean more opportunities for success. For the department to conflate access to online education with rising federal student loan debt diminishes that fact and ultimately hurts the partnerships between institutions, innovators, and the students they serve.”

“The department seems to be more interested in controlling the actions of private companies and creating unnecessary headaches for institutions than it is ensuring students have every tool to succeed academically,” Foxx continued. “I urge the Biden administration to reverse course on this harmful guidance.”

OPMs have long been the target of congressional Democrats and consumer groups, which believe the companies can, through their contractual arrangements, drive up the price of higher education and draw students to low-value academic programs.

Sen. Elizabeth Warren, D-Mass, for example, has raised “concerns about the impact of OPM partnerships on rising student debt loads.”

Under Secretary of Education James Kvaal echoed that sentiment in a statement when the department released its new guidance.

A girl participating in online education training class with teacher and other students using laptop at home.

A girl participating in online education training class with teacher and other students using laptop at home. (iStock)

NEW ONLINE PLATFORM HELPS CONNECT PARENTS WITH TEACHERS OF THEIR CHOICE

“Online education has the potential to meet the needs of many students and lower costs,” he said. “But we are concerned about the growth in loan debt and want to ensure students get value for their money.”

However, many colleges and universities do not have the in-house funding and expertise to develop the online programs they need and need outside help, according to experts familiar with the issue.

OPMs are not the only ones affected by the Education Department’s rules, which critics argue will have a broader negative impact than government officials may realize.

Local police departments helping to compile and analyze campus crime statistics and hospitals providing clinical experiences and “the related educational programing for nurses and other medical professionals” are among the outside entities helping schools through contractual agreements that are being considered third-party servicers, according to the American Council on Education.

The council recently wrote a letter to Education Secretary Miguel Cardona, outlining some of the problems it had with the department’s guidance.

Secretary of Education Miguel Cardona in the Eisenhower Executive Office Building in Washington, D.C., Aug. 8, 2022. 

Secretary of Education Miguel Cardona in the Eisenhower Executive Office Building in Washington, D.C., Aug. 8, 2022.  (REUTERS/Evelyn Hockstein)

BIDEN’S EDUCATION SECRETARY LOBBIES COLLEGES TO DROP OUT OF US NEWS RANKING IN NAME OF EQUITY

“The broadened definition of a [third-party servicer] appears to cover entities that are beyond the common understanding of that term,” the letter states. “Our hope, if given appropriate time to comment, is to provide the department with a fuller picture of the variety of important institutional arrangements that exist so it may better understand the guidance’s impact … We believe the department would benefit from a deeper understanding of the potential that the guidance could trigger an unintended disruption of services to students currently provided by institutions through these entities.”

The letter was co-signed by 46 other higher education interest groups and associations, including accreditors.

Other experts see the department’s actions as not merely misguided but intentional overreach.

“The Department of Education’s crusade against for-profit colleges is now ensnaring a wide range of service providers,” Adam Kissel, visiting fellow at the Heritage Foundation, told Fox News Digital. “This is a classic case of overregulation by overzealous bureaucrats. Every new rule or interpretation like this makes it harder for colleges to serve their students.”

Whatever the department’s motivation, what is clear is the new guidance will present a host of new hurdles for both schools and companies.

A woman working form home with a laptop.

A woman working form home with a laptop. (iStock)

PRESIDENT BIDEN’S STUDENT DEBT RELIEF IS ‘COMFORTABLY WITHIN’ LAW, DOJ ARGUES TO SCOTUS

One challenge, according to legal experts, is that third-party servicers are legally required to sign a contract with their educational partner to be “jointly and severally liable” to the Education Department for any federal violations.

“Third-party OPMs have been able to hide behind really crafty language in their contracts that keeps them from being responsible for any violations,” Stephanie Hall, a senior fellow at the Center for American Progress, told Inside Higher Ed. “It places all the responsibility on the institution.”

Critics have countered that, beyond creating a major new legal hurdle to overcome, the liability requirements could hurt smaller companies, which unlike bigger players, may be unwilling or unable to indemnify their campus partners. Duane Morris, a law firm that works with colleges, has also noted that while a purpose of the guidance may be to hold OPMs liable, the reverse would also hold true; the school would be liable for any violation committed by the third-party servicer.

Another challenge is that third-party servicers are subject to regular audits, which would require these companies to make all their contracts available to federal regulators.

As a result, OPMs and educational institutions will need to take the extra time and effort to carefully redo all their contracts, and some may not even want to continue their partnerships, according to Tony Guida, an attorney at Duane Morris who focuses on education issues.

A tour group makes a stop at the Sterling Memorial Library on the Yale University campus in New Haven, Connecticut, June 12, 2015.

A tour group makes a stop at the Sterling Memorial Library on the Yale University campus in New Haven, Connecticut, June 12, 2015. (Photographer: Craig Warga/Bloomberg via Getty Images)

MARYMOUNT UNIVERSITY STUDENTS LAUNCH PROTESTS AFTER SCHOOL AXES MAJORS LIKE MATH, ENGLISH, RELIGIOUS STUDIES

“OPMs will have to be much more intentional about services they provide,” Guida told Fox News Digital. “With more liability, some companies won’t want to take the risk.”

All these changes would be disruptive to the service of providing online education, critics argue, and have a downstream negative effect on student learning and the quality of higher education.

However, in a statement to Fox New Digital, the Education Department defended its guidance, arguing its simply meant to ensure all parties are complying with federal law.

“The updated third-party servicer guidance is intended to provide much needed clarity and transparency on existing requirements regarding companies that work with colleges around the administration of federal student aid,” a department spokesperson said. “It will help ensure these companies are in compliance with federal rules and regulations so that students can make the best possible decisions about their education.”

“The department is seeking public comment on this guidance, and we will carefully review all comments received,” the spokesperson added. “In the meantime, we will work with colleges to ensure the requirements are clear and that they have ample time to meet reporting deadlines.”

The Department of Education Building.

The Department of Education Building. (iStock)

BIDEN EDUCATION OFFICIAL CLAIMS DEMOCRACY, FATPHOBIA BASED ON WHITE SUPREMACY

Perhaps most importantly, however, these voices argue expanding who falls under the umbrella of third-party servicers also increases the control of the federal government.

“If you’re a regulated entity, the Education Department has broad investigative powers over you,” said Guida. “They can request documents, other things of that nature that would make operating much more difficult. And if third-party servicers don’t comply, this guidance could be weaponized against them.”

Supporters of the department’s guidance counter that the current situation is too opaque.

“That will provide important transparency into what’s going on,” Robert Shireman, senior fellow at the Century Foundation, told Inside Higher Ed. “The Department of Education and then the rest of us will learn more about the contracts that institutions have, and there will be greater scrutiny and accountability for the OPM contractors if they are involved in recruiting students.”

A key issue for the Education Department and those critical of OPMs is how these companies share revenue with academic institutions. In many cases, the company receives a share of the schools’ tuition revenue. However, contractors are increasingly moving away from the revenue-sharing model, instead charging fixed fees for specific services. Some observers claim these companies are having the effect of increasing school tuition rates and profiting from it.

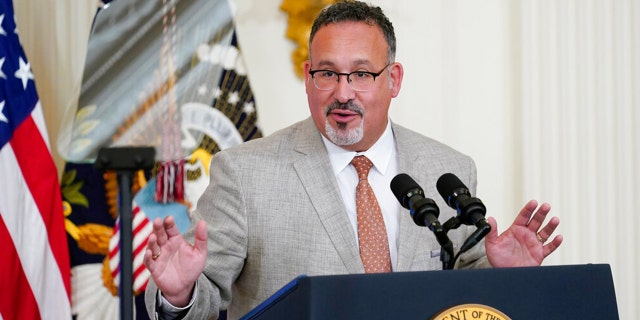
Education Secretary Miguel Cardona speaks during the 2022 National and State Teachers of the Year event in the East Room of the White House in Washington, April 27, 2022.

Education Secretary Miguel Cardona speaks during the 2022 National and State Teachers of the Year event in the East Room of the White House in Washington, April 27, 2022. (AP Photo/Susan Walsh, File)

RANDI WEINGARTEN CLAIMS CHILDREN ‘DO BETTER IN SCHOOLS UNDER TEACHERS UNIONS’

However, others see such arguments — and the department’s new guidance — as ultimately an effort to combat efforts to profit in the education space.

“With the new guidance released last month, the Biden administration seems to be following in the footsteps of President Obama in trying to extinguish private sector, profit seeking participation in higher education,” Beth Akers, senior fellow at the American Enterprise Institute, told Fox News Digital. “There seems to be an attitude that there is no place for profit seeking in higher education. It’s a nice idea to think that all service providers in education should be motivated by benevolence, but profit is what often motivates major innovation — something desperately needed in higher education.”

“Higher education,” continued Akers, “is a realm that has been remarkably stagnant. Instead of trying to stamp out profit seeking and the innovation that would come with it, the Department of Education should focus instead on ousting poorly performing institutions and programs of study from the federal dole by cutting off student aid (loans and grants) from colleges whose graduates fail to out-earn workers with just a high school diploma.”

CLICK HERE FOR THE FOX NEWS APP

The department initially gave colleges and universities until May 1 to report details of their agreements to the government and 30 days to submit comments on the changes. Following widespread outcry, however, the department said that in response to “confusion,” the guidance would not take effect until Sept. 1, rather than immediately as of last month. It also pushed back the end date of the public comment period through March 29.

“This seems to be a solution in search of a problem rather than the other way around. The department hasn’t identified what harm it’s trying to prevent,” said Guida. “It appears to be a broad regulatory grab.”