Silicon Valley Bank collapses after failing to raise capital

Silicon Valley Bank collapses after failing to raise capital


New York
CNN
 — 

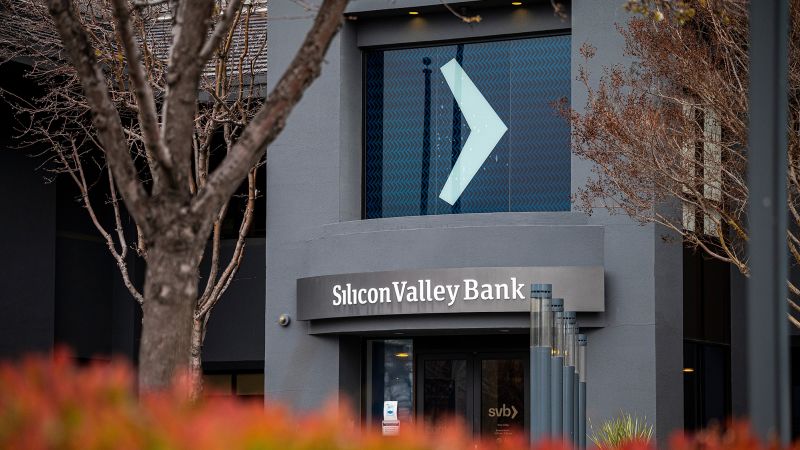
Silicon Valley Bank collapsed Friday early morning immediately after a stunning 48 hours in which a financial institution operate and a capital disaster led to the next-premier failure of a money establishment in US background.

California regulators closed down the tech financial institution and put it below the regulate of the US Federal Deposit Insurance coverage Company. The FDIC is acting as a receiver, which usually implies it will liquidate the bank’s property to pay back back again its customers, including depositors and collectors.

The FDIC, an unbiased federal government agency that insures financial institution deposits and oversees economic institutions, said all insured depositors will have complete accessibility to their insured deposits by no later than Monday early morning. It mentioned it would pay out uninsured depositors an “advance dividend inside the following 7 days.”

The bank, earlier owned by SVB Financial Team, did not reply to CNN’s request for comment.

The wheels began to appear off on Wednesday, when SVB introduced it had marketed a bunch of securities at a reduction and that it would provide $2.25 billion in new shares to shore up its balance sheet. That brought on a panic among the essential venture capital companies, who reportedly recommended corporations to withdraw their money from the lender.

The company’s stock cratered on Thursday, dragging other banks down with it. By Friday early morning, SVB’s shares ended up halted and it experienced abandoned efforts to quickly elevate funds or come across a buyer. Numerous other financial institution shares ended up temporarily halted Friday, which includes Very first Republic, PacWest Bancorp, and Signature Lender.

The mid-morning timing of the FDIC’s takeover was noteworthy, as the agency commonly waits till the market place has closed to intervene.

“SVB’s situation deteriorated so quickly that it could not very last just five a lot more several hours,” wrote Much better Marketplaces CEO Dennis M. Kelleher. “That’s due to the fact its depositors had been withdrawing their income so quickly that the financial institution was bancrupt, and an intraday closure was unavoidable due to a common bank run.”

Silicon Valley Bank’s drop stems partly from the Federal Reserve’s intense desire amount hikes around the past year.

When curiosity premiums were being close to zero, banking companies loaded up on lengthy-dated, seemingly low-hazard Treasuries. But as the Fed raises desire prices to fight inflation, the price of all those belongings has fallen, leaving financial institutions sitting down on unrealized losses.

Higher prices strike tech primarily really hard, undercutting the value of tech stocks and earning it rough to raise cash, Moody’s chief economist Mark Zandi said. That prompted many tech firms to attract down the deposits they held at SVB to fund their operations.

“Higher rates have also lowered the value of their treasury and other securities which SVB desired to fork out depositors,” Zandi stated. ” All of this set off the run on their deposits that pressured the FDIC to takeover SVB.”

Deputy Treasury Secretary Wally Adeyemo on Friday sought to reassure the public about the wellness of the banking method soon after the unexpected collapse of SVB.

“Federal regulators are spending focus to this certain fiscal institution and when we believe about the broader money system, we’re quite self-assured in the skill and the resilience of the process,” Adeyemo explained to CNN in an exclusive interview.

The opinions arrive following Treasury Secretary Janet Yellen convened an unscheduled assembly of money regulators to go over the implosion of Silicon Valley Lender, a main loan company to the hurting tech sector.

“We have the applications that are necessary to [deal with] incidents like what is transpired to Silicon Valley Bank,” Adeyemo explained.

Adeyemo explained US officers are “learning extra information” about the collapse of Silicon Valley Financial institution. He argued the Dodd-Frank monetary reform overhaul, signed into legislation in 2010, has given regulators the equipment they have to have to deal with this and improved the capitalization of financial institutions.

Adeyemo declined to predict what, if any, influence there will be to the broader overall economy or the tech marketplace.

Despite preliminary stress on Wall Avenue over the operate on SVB, which brought about its shares to crater, analysts stated the bank’s collapse is not likely to set off the type of domino outcome that gripped the banking business during the money crisis.

“The program is as properly-capitalized and liquid as it has ever been,” Zandi stated. “The banks that are now in trouble are significantly too modest to be a significant risk to the broader system.”

But scaled-down financial institutions that are disproportionately tied to cash-strapped industries like tech and crypto may be in for a tough journey, according to Ed Moya, senior industry analyst at Oanda.

“Everyone on Wall Avenue realized that the Fed’s fee-hiking campaign would finally break anything, and ideal now that is having down tiny banking companies,” Moya said.

Although somewhat mysterious exterior of Silicon Valley, SVB was amid the best 20 American business banks, with $209 billion in full assets at the finish of final year, in accordance to the FDIC.

It is the most significant loan company to fall short considering the fact that Washington Mutual collapsed in 2008.

The bank partnered with virtually 50 percent of all enterprise-backed tech and wellness treatment providers in the United States, several of which pulled deposits out of the lender.

Mike Mayo, Wells Fargo senior lender analyst, said the disaster at SVB may perhaps be “an idiosyncratic problem.”

“This is evening and working day compared to the worldwide economic disaster from 15 decades ago,” he informed CNN’s Julia Chatterly on Friday. Back then, he stated, “banks had been getting extreme threats, and people today imagined anything was wonderful. Now everyone’s worried, but beneath the area the financial institutions are a lot more resilient than they’ve been in a generation.”

SVB’s unexpected fall mirrored other dangerous bets that have been exposed in the past year’s sector turmoil.

Crypto-centered financial institution Silvergate said Wednesday it is winding down functions and will liquidate the financial institution following remaining fiscally pummeled by turmoil in digital belongings. Signature Lender, another financial institution, was strike tough by the lender selloff, with shares sinking 30{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} ahead of remaining halted for volatility Friday.

“SVB’s institutional problems replicate a more substantial and additional popular systemic issue: The banking market is sitting on a ton of reduced-yielding assets that, many thanks to the past 12 months of price raises, are now far underwater — and sinking,” wrote Konrad Alt, co-founder of Klaros Team.

Alt believed that price will increase have “effectively wiped out close to 28{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of all the capital in the banking business as of the finish of 2022.”

US Economy Advancing Faster Than Expected: Central Bank Chief

US Economy Advancing Faster Than Expected: Central Bank Chief

Federal Reserve Chair Jerome Powell reported Tuesday the U.S. overall economy is advancing at a more rapidly speed than anticipated, which could prompt central financial institution plan makers to elevate desire rates at a more quickly tempo than at first planned to curb paying out and borrowing in hopes of reining in the continuing enhance in purchaser price ranges.

Plan makers at the central financial institution had signaled their intent to boost its benchmark fascination fee by a quarter of a proportion level at upcoming conferences about many months. But Powell advised the Senate Banking Committee that may possibly not be enough to suppress the U.S. inflation level, which rose 6.4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} above the 12 months ending in January, about 3 situations the 2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} pace the Fed considers appropriate.

“The most current economic details have arrive in more robust than anticipated, which indicates that the ultimate level of interest premiums is probable to be better than previously expected,” Powell said. “If the totality of the info had been to suggest that faster tightening is warranted, we would be prepared to increase the speed of rate hikes.”

The Fed raised its benchmark fascination rate, which has an effect on borrowing expenses for each organizations and shoppers, by a quarter-level to a range between 4.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and 4.75{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} final month, easing the rate of level boosts subsequent raises of a fifty percent percentage position in December and .75{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in November.

The Fed had projected escalating the rate to in between 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and 5.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and keeping it there right until 2024, but the quicker economic development could alter those people programs and drive policy makers to improve the benchmark fee even better.

“We will proceed to make our decisions meeting by meeting,” Powell said. “Although inflation has been moderating in new months, the system of acquiring inflation back down to 2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} has a prolonged way to go and is probably to be bumpy.”

Some U.S. economists have continued to forecast that the overall economy, the world’s greatest, will dip into a recession in the coming months, but that has nevertheless to happen. Companies keep on to increase hundreds of hundreds of new workers to their payrolls month following month — 517,000 in January alone — and the national unemployment fee is 3.4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, a 53-calendar year lower.

A report for employing in February is thanks out Friday.

Fed plan makers last fulfilled February 1, but economic knowledge revisions because then showed buyer rate improves and the demand for a lot more staff late previous 12 months didn’t sluggish as considerably as first documented.

A robust labor industry is normally favorable for personnel seeking for larger fork out and hundreds of countless numbers of U.S. workers have switched work for more substantial salaries as the nation continues to get well from the 2020 coronavirus pandemic.

Powell explained to lawmakers that “strong wage expansion is good for staff but only if it is not eroded by inflation.”

“We have more function to do,” he stated. “Our coverage actions are guided by our dual mandate to boost most work and stable selling prices. Devoid of value security, the overall economy does not operate for any person.”

Global economy ‘perilously close’ to a recession: World Bank | Economy News

Global economy ‘perilously close’ to a recession: World Bank | Economy News

The worldwide financial state will occur “perilously close” to a economic downturn this calendar year, led by weaker advancement in all the world’s prime economies – the United States, Europe and China – the Environment Lender warned on Tuesday.

In an annual report, the Earth Financial institution, which lends revenue to poorer nations around the world for progress projects, mentioned it had slashed its forecast for world-wide expansion this 12 months by virtually fifty percent, to just 1.7 per cent, from its past projection of 3 p.c. If that forecast proved precise, it would be the third-weakest annual enlargement in 30 several years, behind only the deep recessions that resulted from the 2008 world-wide economic disaster and the coronavirus pandemic in 2020.

Though the United States could prevent a recession this calendar year – the Entire world Bank has predicted the US economic system will eke out expansion of .5 {515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} – world weak spot will probably pose one more headwind for US businesses and customers, on top rated of large costs and a lot more high-priced borrowing prices. The US would also keep on being vulnerable to more source chain disruptions if COVID-19 keeps surging or Russia’s war in Ukraine worsens.

And Europe, long a major exporter to China, will very likely go through from a weaker Chinese overall economy.

The Earth Lender report also noted that soaring fascination premiums in developed economies like the United States and Europe will attract financial commitment money from poorer nations, thus depriving them of essential domestic expenditure. At the similar time, the report mentioned, these large desire premiums will sluggish progress in made nations around the world at a time when Russia’s invasion of Ukraine has saved earth food prices higher.

“Russia’s invasion of Ukraine has extra big new fees,” Earth Bank President David Malpass explained on a simply call with reporters. “The outlook is specifically devastating for many of the poorest economies where poverty reduction is currently ground to a halt and accessibility to electricity, fertiliser, foodstuff and capital is very likely to continue to be limited for a extended interval.”

The influence of a international downturn would tumble notably tricky on poorer nations around the world in these kinds of, parts as Saharan Africa, which is house to 60 per cent of the world’s inadequate. The World Bank has predicted for every capita earnings will develop just 1.2 percent in 2023 and 2024, which is this sort of a tepid rate that poverty charges could rise.

Chad economy
For most of the earth, this is going to be a ‘tough year’ [File: Xaume Olleros/Bloomberg]

“Weakness in growth and organization investment decision will compound the previously devastating reversals in education and learning, well being, poverty and infrastructure and the rising demands from weather transform,” Malpass mentioned. “Addressing the scale of these issues will involve appreciably much more methods for enhancement and global public goods.”

Along with trying to get new financing so it can lend a lot more to poorer international locations, Malpass explained, the Entire world Financial institution will, among other items, request to improve its lending phrases that would raise personal debt transparency, “especially for the soaring share of very poor international locations that are at superior risk of credit card debt distress”.

Major a few slowdown

The report adopted a likewise gloomy forecast a 7 days before from Kristina Georgieva, the head of the Global Financial Fund, the world lending company. Georgieva approximated on US news community CBS’s, Confront the Country, that one particular-3rd of the environment will tumble into recession this year.

“For most of the earth economy, this is likely to be a difficult 12 months, harder than the 12 months we leave behind,” Georgieva said. “Why? Simply because the three significant economies – US, EU, China – are all slowing down simultaneously.”

The World Financial institution has projected that the European Union’s economy will not increase at all subsequent year just after obtaining expanded 3.3 p.c in 2022. It foresaw China developing 4.3 {515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, just about a share point lower than it experienced beforehand forecast and about 50 {515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} the speed that Beijing posted in 2021.

The bank predicted building countries to fare greater, expanding 3.4 {515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} this calendar year, the same as in 2022, though nonetheless only about fifty percent the speed of 2021. It forecast Brazil’s advancement slowing to .8 p.c in 2023, down from 3 {515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} previous calendar year. In Pakistan, it predicted the economy to broaden just 2 {515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} this year, one-third of last year’s speed.

Other economists have also issued bleak outlooks, although most of them not rather as dire. Economists at JPMorgan are predicting slow progress this 12 months for innovative economies and the environment as a total, but they do not be expecting a worldwide economic downturn. Past thirty day period, the bank predicted that slowing inflation will bolster consumers’ potential to shell out and electricity advancement in the US and elsewhere.

“The world growth will transform into 2023 bent but not damaged,” the JPMorgan report reported.

What Q4 bank earnings can tell us about the economy

What Q4 bank earnings can tell us about the economy

This will be a major 7 days for financial information. The shopper value index will come out Thursday and notify us irrespective of whether inflation proceeds to moderate less than the influence of continuing Federal Reserve price hikes. And the kickoff of company earnings time will also aid fill in the around-phrase picture for desire charges and a potential economic slowdown.

FactSet estimates that calendar fourth-quarter profits for S&P 500 organizations will be down extra than 4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from a calendar year earlier — the worst demonstrating considering the fact that early in the pandemic.

Friday, we’ll listen to from a gaggle of huge financial institutions: JPMorgan Chase, Citigroup, Lender of The usa and Wells Fargo. So significantly, predictions aren’t good for company earnings in Q4 — when the financial state was slowing and layoffs had been spreading in tech and finance.

Equity analyst Ken Leon at CFRA Exploration sees the significant banks’ earnings reports as a harbinger of what’s to occur: “a weaker fourth quarter in ’22 versus ’21, lots of uncertainty for 2023.”

Mortgage loan finance, investment banking, mergers and preliminary public choices have all slumped, Leon said, as markets faltered and borrowing charges enhanced. 

But higher desire prices also develop an upside for banking companies, in accordance to Mark Zandi at Moody’s Analytics.

“The desire fees on their deposits, they’re climbing incredibly slowly,” he said. “But the desire price they cost on their financial loans are up, so they are carrying out rather very well on that so-termed net curiosity margin — which is their revenue margin.”

But Zandi does not imagine that’ll final, which could possibly be welcome news for savers. “I do assume financial institutions will need to have to shell out their depositors extra to keep on to deposits. They are setting up to drop deposits.”

What comes about to banks’ stability sheets in 2023 will explain to us a good deal about recession danger, stated Karen Petrou at Federal Economic Analytics.

“Banks are canaries in the financial coal mine,” she reported.

Quincy Krosby, chief international strategist at LPL Fiscal, puts it this way: “Whatever transpires in the financial system is likely to manifest itself in the banking companies.”

She’ll be observing for any rise in defaults on mortgages, car or truck financial loans and credit history playing cards and how considerably banking institutions have to set apart to go over those people losses.  

“That will give us an sign of how People in america are dealing with paying out back again personal debt,” Krosby said.

Banks’ reporting on credit rating card use has now advised us something vital, she additional. “Lower-wage earners have been working with their cards more and more for necessities than just discretionary things.”

Which is a sign that large costs and dwindling price savings are pushing individuals consumers a tiny closer to the edge.

There is a lot going on in the planet.  Via it all, Market is right here for you. 

You count on Marketplace to break down the world’s occasions and tell you how it influences you in a reality-based mostly, approachable way. We count on your financial guidance to maintain building that achievable. 

Your donation nowadays powers the independent journalism that you count on. For just $5/thirty day period, you can support maintain Market so we can keep reporting on the factors that make any difference to you.  

Bank of England delays bond sales, launches temporary purchase program

Bank of England delays bond sales, launches temporary purchase program

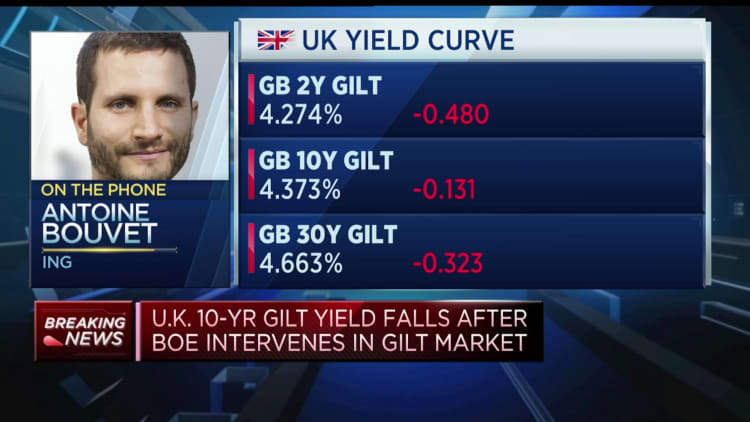
ING: BOE might have to extend bond purchases with ongoing market volatility

LONDON — The Financial institution of England will suspend the planned commence of its gilt providing next 7 days and start off quickly purchasing prolonged-dated bonds in buy to tranquil the current market chaos unleashed by the new government’s so-termed mini-price range.

Yields on U.K. govt bonds, acknowledged as “gilts,” have been on study course for their sharpest month to month increase considering the fact that at the very least 1957 as investors fled British mounted revenue markets subsequent the new fiscal plan bulletins. The steps provided huge swathes of unfunded tax cuts that have drawn international criticism, like from the IMF.

In a statement Wednesday, the central lender reported it was monitoring the “substantial repricing” of U.K. and worldwide assets in modern days, which has hit very long-dated U.K. government credit card debt specially really hard.

“Ended up dysfunction in this market place to continue or worsen, there would be a product chance to Uk financial steadiness. This would lead to an unwarranted tightening of financing disorders and a reduction of the move of credit history to the actual economy,” the Lender of England mentioned.

“In line with its fiscal steadiness goal, the Bank of England stands all set to restore market performing and reduce any pitfalls from contagion to credit circumstances for British isles households and enterprises.”

As of Wednesday, the lender will get started temporary buys of very long-dated U.K. federal government bonds in order to “restore orderly marketplace ailments,” and mentioned these will be carried out “on regardless of what scale essential” to soothe marketplaces.

Pound could fall even further in the absence of aggressive BOE monetary policy, KCL professor says

The bank’s Financial Plan Committee on Wednesday acknowledged the dysfunction in the gilt industry posed a material chance to the country’s money balance, and opted to consider fast action.

The Monetary Policy Committee’s concentrate on of an yearly £80 billion ($85 billion) reduction of its gilt holdings remains unchanged, the financial institution stated, with the first gilt product sales — to begin with slated for Monday — now having area on Oct. 31.

A U.K. Treasury spokesperson confirmed that the procedure experienced been “absolutely indemnified” by the Treasury and mentioned that Finance Minister Kwasi Kwarteng is “dedicated to the Financial institution of England’s independence.”

“The Government will carry on to do the job closely with the Financial institution in aid of its monetary stability and inflation objectives,” the spokesperson extra.

The financial institution claimed it will publish a market see outlining the operational particulars of the program “shortly.”

Yields on U.K. 30-yr gilts and 10-year gilts dropped sharply after the announcement, when sterling initially fell 1.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} against the greenback right before recovering a little bit to trade at around $1.066 by mid-afternoon in London.

‘Caught in a crossfire’

Antoine Bouvet, senior costs strategist at ING, stated that the Financial institution of England could have to have to lengthen the bond purchases over and above the first two-week period if volatility in the gilt sector carries on, and that an additional hike in curiosity prices was not off the table.

Bouvet instructed CNBC promptly after the announcement that the bank’s to start with precedence for now experienced to be the working of the gilt market place, suggesting the worst consequence would be for the sovereign to be left with no marketplace accessibility and not able to secure funding.

“Plainly the gilt marketplace was caught in a crossfire between the Financial institution of England and the Treasury, and it’s not precisely like that but it looked a large amount like they ended up competing, or operating at crossed functions,” Bouvet explained.

“So you have a entire world in which you have a economic downturn and the BOE is trying to amazing the financial system with hikes, and on the other hand you have the Treasury that is making an attempt to shield the economic system from that economic downturn and utilizing fiscal actions that are inflationary.”

He additional that the Treasury’s assertion of assistance was critical, noting that the federal government would be eager to keep away from the effect that the gilt current market is in “so substantially issues” that it had compelled the Bank of England to get keep of rescuing the overall economy.

How Donald Trump got his Deutsche Bank loans

How Donald Trump got his Deutsche Bank loans

Deutsche Bank has emerged as the star witness in New York lawyer basic Letitia James’ circumstance versus Donald Trump and the Trump Corporation.

In a suit submitted final week, James accused Trump and his corporation of defrauding the German financial investment bank and some others by exaggerating the price of his qualities. Deutsche Financial institution, which prolonged Trump hundreds of tens of millions of pounds in financial loans for resort and resort progress projects in the earlier decade, is cooperating with her office’s investigation, James reported at a press convention.

Read through a lot more

The New York legal professional general’s (NYAG) grievance describes an surroundings in which Trump was able to pass off defective economical documents as true, duping economic and government institutions in the process. Trump lawyer Alina Habba referred to as the lawsuit meritless, expressing the NYAG was “neither concentrated on the specifics nor the legislation.”

How Trump’s connection with Deutsche Financial institution evolved

The Trump Business experienced accomplished business with Deutsche Bank considering the fact that the 1990s, but the pivot point in their shared history arrived in 2011 when the enterprise switched from the industrial real estate division of the bank to the non-public prosperity administration division, according to the grievance.

In September 2011, Jared Kushner introduced his brother-in-law Donald Trump Jr. to Rosemary Vrablic, a handling director and senior banker at Deutsche Financial institution. More than the up coming decade, Vrablic would become acknowledged as Trump’s “private banker.” (Vrablic resigned in December 2020 along with fellow Deutsche Financial institution banker Dominic Scalzi soon after violating inside bank regulations by personally investing in an apartment partly owned by Kushner, a customer. Vrablic and Scalzi are presently barred by the Financial Marketplace Regulatory Authority, or Finra, from acting as brokers. Scalzi is not named in the criticism.)

The Trump Group sought a mortgage for its golf course in Doral, Florida. The professional authentic estate division identified as it “a hard asset and our preliminary reaction was not enthusiastic,” the grievance suggests.

But soon after browsing the mortgage all around to other financial institutions, Vrablic available the very best mortgage: her division’s deal arrived with a 2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} fascination amount vs. the professional real estate division’s offer you of 8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. “It does not get much better than this,” Ivanka Trump stated. The tradeoff was that Trump would individually have to ensure the whole sum of the loan—$125 million—and preserve a internet worth of $2.5 billion and $50 million in unencumbered liquidity.

When he noticed the conditions of the bank loan settlement, Trump Group finance chief Jason Greenblatt was taken aback, in accordance to the criticism. “Is DJT keen to do that?” he asked Ivanka. “Also, the net worth covenants and DJT indebtedness limits would appear to be a trouble?”

Greenblatt additional that the private assurance was a “highly dangerous proposition” and conflicted with what Trump had informed him in the past, the grievance states. “Obviously this is not my final decision, but this is totally inconsistent with what he told me he would at any time do once again.”

Who did Trump defraud?

Trump was in a position to get the Doral mortgage, like many many others outlined in the grievance, in element due to his statements of financial problem, personalized stability sheets that James alleges contained fraudulent misrepresentations of his wealth, property values, and belongings. Amongst the allegations she cites: Trump allegedly lied about the dimension of his Manhattan apartment, around-counted anticipated golf club membership, and violated the phrases of a conservation easement to inflate his estimated really worth and safe favorable loans.

In the complaint, Deutsche Lender is solid as 1 of the primary victims of Trump’s alleged fraud. In a statement to Quartz, bank spokesperson Dylan Riddle said:

“We are unable to remark on the specifics of recent or previous client accounts, nor the compound of lawful promises based mostly on sure specifics that the NYAG, alone, has alleged had been mysterious or unavailable to Deutsche Bank at the time. The Lender takes its lawful obligations very seriously, including properly responding to authorized investigations and proceedings.”

The NYAG informed Deutsche Financial institution of the falsified monetary paperwork in 2020 as portion of an investigative subpoena. Afterward, Deutsche Lender requested the Trump Business inquiries about the fiscal paperwork. The firm “refused to respond” so Deutsche Bank resolved to “exit its relationship” with the corporation, the grievance claims.

At the very least a single of the Deutsche Bank loans—a $125 million credit for the Doral property—was refinanced by Axos Bank, a San Diego-centered financial institution, in May perhaps 2022. Given that the Trump Business paid out $295 million of what it owes to Deutsche, the German bank now only holds $45 million in Trump connected credit card debt, according to the NYAG’s filing. NYAG estimates that Trump saved among $85 million and $150 million in curiosity rate personal savings mainly because of the misleading statements.

Banking institutions weren’t the only institutions defrauded. Deutsche Bank loaned the Trump Business $170 million to buy and renovate the Previous Put up Business making in Washington DC, a bid that Trump gained for his Trump Worldwide Hotel.

Trump’s economical documents have been utilised in the bidding method with the US Typical Providers Administration (GSA), a system that the Trump Organization bragged was “one of the most competitive choice procedures in the historical past of” the GSA.