

Here’s What’s Concerning About NVIDIA’s (NASDAQ:NVDA) Returns On Capital

Here’s What’s Concerning About NVIDIA’s (NASDAQ:NVDA) Returns On Capital

Obtaining a business that has the prospective to increase significantly is not effortless, but it is probable if we glimpse at a several vital financial metrics. First of all, we’d want to identify a expanding return on capital employed (ROCE) and then alongside that, an ever-expanding foundation of money employed. Set simply, these sorts of enterprises are compounding equipment, that means they are frequently reinvesting their earnings at ever-greater charges of return. On the other hand, after briefly hunting in excess of the figures, we really don’t assume NVIDIA (NASDAQ:NVDA) has the makings of a multi-bagger likely forward, but let us have a search at why that might be.

Knowing Return On Cash Employed (ROCE)

If you haven’t labored with ROCE just before, it measures the ‘return’ (pre-tax financial gain) a enterprise generates from cash utilized in its business enterprise. The formula for this calculation on NVIDIA is:

Return on Cash Employed = Earnings Prior to Desire and Tax (EBIT) ÷ (Full Property – Latest Liabilities)

.16 = US$5.6b ÷ (US$41b – US$6.6b) (Primarily based on the trailing twelve months to January 2023).

So, NVIDIA has an ROCE of 16{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. That is a somewhat typical return on capital, and it can be about the 14{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} generated by the Semiconductor industry.

Watch our latest analysis for NVIDIA
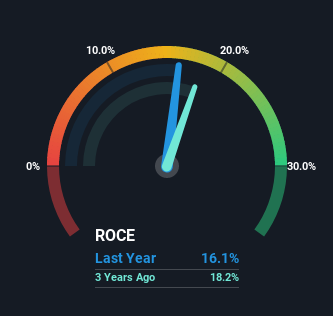
roce

roce

In the over chart we have calculated NVIDIA’s prior ROCE from its prior efficiency, but the long run is arguably additional essential. If you happen to be fascinated, you can look at the analysts predictions in our free report on analyst forecasts for the enterprise.

The Development Of ROCE

On the surface area, the development of ROCE at NVIDIA doesn’t encourage confidence. More than the very last five decades, returns on funds have lowered to 16{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from 32{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} 5 yrs back. On the other hand it appears like NVIDIA may well be reinvesting for extensive term expansion simply because whilst capital employed has elevated, the firm’s product sales haven’t transformed a lot in the previous 12 months. It is value retaining an eye on the firm’s earnings from in this article on to see if these investments do finish up contributing to the base line.

The Bottom Line

Bringing it all alongside one another, though we are relatively encouraged by NVIDIA’s reinvestment in its possess small business, we’re informed that returns are shrinking. But to long phrase shareholders the inventory has gifted them an unbelievable 372{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} return in the last 5 many years, so the marketplace appears to be rosy about its future. On the other hand, unless these underlying tendencies turn a lot more beneficial, we would not get our hopes up too superior.

If you want to carry on researching NVIDIA, you may well be interested to know about the 3 warning signs that our evaluation has uncovered.

If you want to research for sound providers with great earnings, check out this free list of firms with fantastic balance sheets and impressive returns on fairness.

Have comments on this posting? Involved about the content material? Get in contact with us specifically. Alternatively, email editorial-team (at) simplywallst.com.

This report by Basically Wall St is normal in mother nature. We present commentary based mostly on historical data and analyst forecasts only utilizing an impartial methodology and our articles are not meant to be fiscal advice. It does not constitute a recommendation to get or market any inventory, and does not get account of your goals, or your money scenario. We aim to carry you extended-phrase targeted evaluation pushed by fundamental data. Take note that our evaluation might not component in the most recent cost-delicate firm announcements or qualitative materials. Only Wall St has no posture in any shares outlined.

Be part of A Compensated Consumer Study Session
You’ll acquire a US$30 Amazon Gift card for 1 hour of your time while helping us establish better investing applications for the specific traders like you. Sign up listed here
Silicon Valley Bank collapses after failing to raise capital

Silicon Valley Bank collapses after failing to raise capital


New York
CNN
 — 

Silicon Valley Bank collapsed Friday early morning immediately after a stunning 48 hours in which a financial institution operate and a capital disaster led to the next-premier failure of a money establishment in US background.

California regulators closed down the tech financial institution and put it below the regulate of the US Federal Deposit Insurance coverage Company. The FDIC is acting as a receiver, which usually implies it will liquidate the bank’s property to pay back back again its customers, including depositors and collectors.

The FDIC, an unbiased federal government agency that insures financial institution deposits and oversees economic institutions, said all insured depositors will have complete accessibility to their insured deposits by no later than Monday early morning. It mentioned it would pay out uninsured depositors an “advance dividend inside the following 7 days.”

The bank, earlier owned by SVB Financial Team, did not reply to CNN’s request for comment.

The wheels began to appear off on Wednesday, when SVB introduced it had marketed a bunch of securities at a reduction and that it would provide $2.25 billion in new shares to shore up its balance sheet. That brought on a panic among the essential venture capital companies, who reportedly recommended corporations to withdraw their money from the lender.

The company’s stock cratered on Thursday, dragging other banks down with it. By Friday early morning, SVB’s shares ended up halted and it experienced abandoned efforts to quickly elevate funds or come across a buyer. Numerous other financial institution shares ended up temporarily halted Friday, which includes Very first Republic, PacWest Bancorp, and Signature Lender.

The mid-morning timing of the FDIC’s takeover was noteworthy, as the agency commonly waits till the market place has closed to intervene.

“SVB’s situation deteriorated so quickly that it could not very last just five a lot more several hours,” wrote Much better Marketplaces CEO Dennis M. Kelleher. “That’s due to the fact its depositors had been withdrawing their income so quickly that the financial institution was bancrupt, and an intraday closure was unavoidable due to a common bank run.”

Silicon Valley Bank’s drop stems partly from the Federal Reserve’s intense desire amount hikes around the past year.

When curiosity premiums were being close to zero, banking companies loaded up on lengthy-dated, seemingly low-hazard Treasuries. But as the Fed raises desire prices to fight inflation, the price of all those belongings has fallen, leaving financial institutions sitting down on unrealized losses.

Higher prices strike tech primarily really hard, undercutting the value of tech stocks and earning it rough to raise cash, Moody’s chief economist Mark Zandi said. That prompted many tech firms to attract down the deposits they held at SVB to fund their operations.

“Higher rates have also lowered the value of their treasury and other securities which SVB desired to fork out depositors,” Zandi stated. ” All of this set off the run on their deposits that pressured the FDIC to takeover SVB.”

Deputy Treasury Secretary Wally Adeyemo on Friday sought to reassure the public about the wellness of the banking method soon after the unexpected collapse of SVB.

“Federal regulators are spending focus to this certain fiscal institution and when we believe about the broader money system, we’re quite self-assured in the skill and the resilience of the process,” Adeyemo explained to CNN in an exclusive interview.

The opinions arrive following Treasury Secretary Janet Yellen convened an unscheduled assembly of money regulators to go over the implosion of Silicon Valley Lender, a main loan company to the hurting tech sector.

“We have the applications that are necessary to [deal with] incidents like what is transpired to Silicon Valley Bank,” Adeyemo explained.

Adeyemo explained US officers are “learning extra information” about the collapse of Silicon Valley Financial institution. He argued the Dodd-Frank monetary reform overhaul, signed into legislation in 2010, has given regulators the equipment they have to have to deal with this and improved the capitalization of financial institutions.

Adeyemo declined to predict what, if any, influence there will be to the broader overall economy or the tech marketplace.

Despite preliminary stress on Wall Avenue over the operate on SVB, which brought about its shares to crater, analysts stated the bank’s collapse is not likely to set off the type of domino outcome that gripped the banking business during the money crisis.

“The program is as properly-capitalized and liquid as it has ever been,” Zandi stated. “The banks that are now in trouble are significantly too modest to be a significant risk to the broader system.”

But scaled-down financial institutions that are disproportionately tied to cash-strapped industries like tech and crypto may be in for a tough journey, according to Ed Moya, senior industry analyst at Oanda.

“Everyone on Wall Avenue realized that the Fed’s fee-hiking campaign would finally break anything, and ideal now that is having down tiny banking companies,” Moya said.

Although somewhat mysterious exterior of Silicon Valley, SVB was amid the best 20 American business banks, with $209 billion in full assets at the finish of final year, in accordance to the FDIC.

It is the most significant loan company to fall short considering the fact that Washington Mutual collapsed in 2008.

The bank partnered with virtually 50 percent of all enterprise-backed tech and wellness treatment providers in the United States, several of which pulled deposits out of the lender.

Mike Mayo, Wells Fargo senior lender analyst, said the disaster at SVB may perhaps be “an idiosyncratic problem.”

“This is evening and working day compared to the worldwide economic disaster from 15 decades ago,” he informed CNN’s Julia Chatterly on Friday. Back then, he stated, “banks had been getting extreme threats, and people today imagined anything was wonderful. Now everyone’s worried, but beneath the area the financial institutions are a lot more resilient than they’ve been in a generation.”

SVB’s unexpected fall mirrored other dangerous bets that have been exposed in the past year’s sector turmoil.

Crypto-centered financial institution Silvergate said Wednesday it is winding down functions and will liquidate the financial institution following remaining fiscally pummeled by turmoil in digital belongings. Signature Lender, another financial institution, was strike tough by the lender selloff, with shares sinking 30{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} ahead of remaining halted for volatility Friday.

“SVB’s institutional problems replicate a more substantial and additional popular systemic issue: The banking market is sitting on a ton of reduced-yielding assets that, many thanks to the past 12 months of price raises, are now far underwater — and sinking,” wrote Konrad Alt, co-founder of Klaros Team.

Alt believed that price will increase have “effectively wiped out close to 28{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of all the capital in the banking business as of the finish of 2022.”

Up from here? The free fall in housing market demand just concluded, says Capital Economics

Up from here? The free fall in housing market demand just concluded, says Capital Economics

But there could at last be some good information for builders and brokers: Scientists at Cash Economics consider housing sector activity is bottoming out.

“There are developing indicators that housing industry activity may be near to a trough. The decline in house loan costs around the past pair of months has led to a little enhancement in affordability and a increase in homebuyer sentiment, albeit from a report low. Corroborating this, mortgage loan applications for household buy have ticked greater in the previous couple of months, which ought to feed by means of to increased product sales,” writes Sam Corridor, assets economist at Funds Economics.

It is not just Cash Economics. There is a increasing optimism among brokers and brokers across the place. They’re hoping that loosening economical ailments, which noticed the regular 30-yr fastened mortgage charge drop from 7.37{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 6.09{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} over the earlier two months, will assist to give the looming spring year a minimal juice.

Let us be obvious: Even if housing industry activity (i.e. residence gross sales) has in fact bottomed out, it doesn’t guarantee that household sales will have a swift restoration. Immediately after all, housing affordability remains “pressurized” to a historic diploma. That will happen when U.S. home costs soar 41{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in just over two a long time and mortgage prices spike from 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to over 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in just a 12-thirty day period span.

“But any recovery in housing market place action this year will be tepid. Stretched affordability, a weakening overall economy, and falling residence charges will all weigh on activity. As a end result, we assume 2023 will be the weakest year for gross sales given that 2011 and for starts since 2014,” generate Cash Economics scientists.

Just because U.S. dwelling profits might be nearing a base will not suggest we need to also pencil in the bottom for U.S. property charges.

“Affordability will continue being stretched,” compose Funds Economics scientists. “We believe residence prices will have to have to slide by a further 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} or 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to convey affordability again to a degree that will support additional usual amounts of need.”

Via October, the Circumstance-Shiller Countrywide Residence Cost Index has U.S. house price ranges down 2.4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from the June 2022 peak. In 2023, Funds Economics expects U.S. dwelling rates to fall 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} whilst the ordinary 30-calendar year home loan charge slips to 5.75{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} by yr-stop. Peak to trough, Money Economics expects U.S. dwelling rates to fall among 8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}

Moody’s Analytics chief economist Mark Zandi also thinks U.S. residence product sales are nearing their base though countrywide home charges have further to drop.

“Housing desire [home sales] is near to a trough housing supply [housing starts and completions] has however to hit bottom and [U.S.] residence prices have a way to go in advance of achieving their nadir,” Zandi tells Fortune.

Peak to trough, Zandi expects U.S. household price ranges to fall 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}—with “overvalued” housing marketplaces out West having hit the toughest.

Let us say Capital Economics and Moody’s are proper and countrywide home costs slide 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from peak to trough. If that takes place, household rates as calculated by Circumstance-Shiller would slide again to Oct 2021 stages. On one hand, that would mark the 2nd-most important residence price tag correction of the put up-WWII era. On the other hand, it would be relatively tame in contrast to the 26{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} nationwide house price tag correction observed among the housing bubble’s best in 2007 and the housing crash’s base in 2012.

Seeking for additional housing facts? Stick to me on Twitter at @NewsLambert.

Master how to navigate and fortify trust in your business with The Rely on Element, a weekly newsletter analyzing what leaders want to triumph. Signal up below.