House GOP debt ceiling plan would cap future government spending

House GOP debt ceiling plan would cap future government spending

Speaker Kevin McCarthy (R-CA) on Wednesday unveiled his party’s extremely-predicted financial debt ceiling proposal, indicating he’s prepared to raise the restrict by $1.5 trillion or right up until March 31, 2024 — whichever comes very first — but only if Democrats agree to a host of other actions.

“I urge all my colleagues on both equally sides of the aisle to aid this strategy to get our nation back on monitor,” McCarthy said on the flooring of the U.S. Household immediately after months of ready to introduce a plan, saying those measures will save taxpayers $4.5 trillion above the following ten years.

But a lot of of the key GOP priorities in the 320-site bill — which includes things like a cap on government paying and a reversal of areas of Biden’s agenda — are deeply opposed by Democrats, generating it unclear how the two sides will appear collectively before the credit card debt limit is achieved, perhaps in June. A governing administration default would have considerably-achieving penalties for entire world marketplaces and, many fear, immediately tip the U.S. overall economy into a recession.

WASHINGTON, DC - APRIL 19: Speaker of the House Kevin McCarthy (R-CA) is surrounded by reporters after he leaves the House Floor to return to his office at the U.S. Capitol on Wednesday, April 19, 2023 in Washington, DC. McCarthy delivered remarks on the House floor, accounting the GOP's debt limit bill, which they call the Limit, Save, Grow Act. (Kent Nishimura / Los Angeles Times via Getty Images)

Speaker of the Residence Kevin McCarthy (R-CA) is surrounded by reporters right after he introduced the GOP’s financial debt restrict bill, which they contact the Limit, Preserve, Improve Act. (Kent Nishimura / Los Angeles Periods by using Getty Photos)

“Not everybody sees the similar way as the Speaker does or as the conservative wing of the Republican Bash does,” Stifel Chief Washington Coverage Strategist Brian Gardner explained to Yahoo Finance Are living Tuesday right after aspects of the proposal leaked out, noting the passage of the bill in the Residence is significantly from a confident matter.

If it does move, McCarthy and other people say that will drive President Joe Biden and other Democrats to come to the negotiating table and abandon their party’s place that the only suitable motion now is to increase the personal debt ceiling without any conditions.

Here’s some highlights of the GOP plan.

Caps on shelling out and ‘clawing back’ COVID-19 cash

The centerpiece of the invoice, which has been dubbed the “Limit, Help you save, Mature Act of 2023,” are caps of federal government paying out with a proposal to return discretionary paying to FY2022 ranges and then impose a 1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} boost limit on federal government paying soon after that.

These actions, Republicans say, would impose fiscal discipline on Washington that has been missing in recent many years. Meanwhile, critics say the approach would disproportionately area the obligation for saving revenue on federal government social packages, even though keeping away from significant cuts to the Pentagon and veteran providers, two politically well-liked programs that McCarthy has reported will mainly be spared.

The strategy also contain provisions to claw back unspent dollars from the flurry of COVID-19 reduction expenditures passed in latest yrs that are projected to return further billions of bucks to government coffers.

The bill received one particular early good assessment Wednesday afternoon when Maya MacGuineas, president of the Committee for a Responsible Federal Finances, stated in a statement that the “bill is not ample to provide our debt to manageable degrees, but is a sensible and extremely welcome to start with phase.”

Using intention at the Biden legacy

The bill also seeks to reverse some of the central achievements of the Biden administration’s early years in business, including massive chunks of the Inflation Reduction Act — potentially the president’s most cherished accomplishment.

To start with, it would undo a host of what the invoice phone calls “market distorting eco-friendly strength tax credits” that are focused on amplifying the US government’s means to respond to climate transform. The bill would also reverse $80 billion in new funding established to go to that Inside Earnings Assistance in the coming ten years intended to shut the tax hole and shell out for superior assistance. Republicans, nevertheless, have warned the IRS funding would guide to an “army of 87,000 IRS agents.”

The GOP proposal would also kill President Biden’s new force by means of government motion to forgive student personal loan credit card debt. That is an effort and hard work that is now tied up in legal troubles with the Supreme Courtroom expected to decide its fate in the coming months.

A different evaluate features in the package deal is referred to as the “REINS act,” which targets what Republicans explain as Biden’s government overreach.

ACCOKEEK, MD - APRIL 19: President Joe Biden delivers remarks on the economy at an International Union of Operating Engineers Local 77 union training facility on April 19, 2023 in Accokeek, Maryland. Biden spoke on his plans to expand the economy and addressed Republican leadership's approach to raising the debt ceiling later this year. (Photo by Nathan Howard/Getty Images)

President Joe Biden delivers remarks in Accokeek, Maryland. (Nathan Howard/Getty Visuals)

A emphasis on energy and controversial new perform necessities

There is also a large swath of the bill devoted to vitality.

In March, the Dwelling handed HR1 — what Republicans dubbed their prime priority — about a suite of electricity reforms. The law sought to open up new regions of The united states for fossil gas output and for mining as properly as velocity up the allowing method for energy tasks.

That invoice was lifeless on arrival in the Democratic-controlled Senate, but is having a different life soon after remaining included in Wednesday’s credit card debt restrict monthly bill.

The bill also seeks to impose controversial new work needs on lower-profits People who participate in federal systems like food stuff stamps and Medicaid. These rewards would carry on, but only in trade for a prerequisite that these recipients operate lengthier hours.

In his speech, McCarthy said they were “common perception measures” that would enable “rebuild the workforce.”

The inclusion of these operate prerequisites is a bid to satisfy the most conservative Republican associates of McCarthy’s caucus who have been wary of the total proposal. Some even suggested the invoice may possibly have to have to go even further by repealing the complete Inflation Reduction Act to obtain their assist.

Through an occasion in Maryland Wednesday afternoon, President Biden laid into the approach and the GOP strategy to the personal debt ceiling, expressing the Republican agenda is about getting absent gains for hundreds of thousands of decrease-earnings Individuals to maintain tax cuts for the richest Americans and biggest firms.

“A minority of the social gathering, what I phone the MAGA Republicans, are in command of the celebration and they’re in Congress threatening to undo all the stuff you’ve got assisted me get carried out” he told an audience of union users.

As for McCarthy, he claimed that now that his monthly bill has been proposed, it’s time for talks to start off in earnest.

“Now that we have introduced a obvious plan for a responsible credit card debt limit raise, they have no additional justification and refuse to negotiate,” he explained Wednesday.

Ben Werschkul is Washington correspondent for Yahoo Finance.

Click on listed here for politics news associated to company and money

Examine the most recent fiscal and company news from Yahoo Finance

Download the Yahoo Finance app for Apple or Android

Abide by Yahoo Finance on Twitter, Facebook, Instagram, Flipboard, LinkedIn, and YouTube
Long Covid treatment can lead to debt after insurance denies claims

Long Covid treatment can lead to debt after insurance denies claims

In June 2021, 32-yr-old Alyssa Maness was diagnosed with POTS, a anxious process disorder that her medical professionals imagine was triggered by Covid.

POTS, or postural orthostatic tachycardia syndrome, induced numbness during her arms and legs, a pins-and-needles feeling and sudden drops in her heart rate.

Simply because her coronary heart challenges didn’t go away, in early 2022 her medical professionals commenced conducting a series of lab exams in an endeavor to much better fully grasp her very long Covid signs and symptoms.

When Maness submitted the screening to her insurance coverage — Anthem Blue Cross — the supplier deemed the tests medically needless and declined to go over the charge. She’s now on the hook for the healthcare expenses, which have previously value her far more than $10,000 out of pocket.

“I’m variety of at the point regrettably where I have just given up,” stated Maness, a Ph.D. student in Sacramento, California. Quite a few of her insurance policies appeals have been denied. “I don’t have the mental bandwidth to even fight this any more, for the reason that it’s become very clear that it is most likely heading to be unsuccessful.”

Maness is between a number of extensive Covid patients in the United States interviewed by NBC News who say their coverage companies are declining to provide coverage similar to their disease.

Alyssa Maness.
Alyssa Maness.Courtesy Alyssa Maness

But there are most likely a lot of a lot more. Up to 4 million comprehensive-time staff are out of the labor force owing to lengthy Covid, according to study from the Brookings Establishment, a Washington-dependent assume tank.

NBC Information has requested insurance companies for comment.

For some, the treatment they require to control their continual health issues has still left them in medical credit card debt, which can conveniently balloon into the countless numbers or even tens of thousands of dollars, specialists say. It is unclear how many are getting denied coverage, but a paper revealed in Could in JAMA Well being Forum estimated that the individual healthcare prices of extensive Covid could occur to around $9,000 a calendar year.

Aspect of the dilemma, authorities say, is the ambiguity of long Covid symptoms, which can range from excessive exhaustion to reduction of flavor and smell to debilitating heart palpitations. You will find no formal take a look at to diagnose the affliction, nor is there any distinct encouraged treatment. That would make it additional complicated for medical practitioners to come up with a proper therapy.

Right before they pay out, insurance policy providers normally want to know if the procedure is confirmed to perform.

Lengthy Covid clients can struggle the denied promises by means of appeals or heading to courtroom — a time-consuming and draining strategy for any individual, let on your own those people who may well suffer from fatigue and brain fog, reported Michele Johnson, the executive director of the Tennessee Justice Middle, a lawful support group that has aided extensive Covid patients get wellness protection.

“They’re attempting to preserve their position or maintain caring for their household,” she stated, “and there’s so significantly bureaucracy and red tape that they’re just drowning in it.”

‘Medical necessity’

Specialists say coverage companies will usually deny claims for care relevant to prolonged Covid for the reason that they will not see it as a “medical necessity.”

The expression is what insurance policy businesses use to evaluate no matter if they should approve or deny a assert, claimed Linda Bergthold, a previous wellness plan researcher at Stanford University’s Heart for Wellness Policy.

The term has been thrown all around by insurance plan organizations for decades, but it was not supplied a formal framework until eventually the late 1990s, which Bergthold assisted acquire.

In order for the care a individual gets to be considered medically required by an insurance coverage provider, there has to be substantial research or evidence that displays that it operates, she mentioned.

That’s “a vital difficulty for very long Covid,” she explained, mainly because the sickness is so new and continue to badly comprehended.

“Analysis, just like every thing with Covid, is all new,” she reported. “No one really pretty appreciates what is effective and nobody really understands why some people today have it lengthier than other folks.”

To be certain, as of 2021, there are diagnostic codes for very long Covid — essential applications applied by medical doctors to characterize health care diagnoses for insurance policies coverage, reported Dr. Alan Kwan, a cardiologist at Cedars-Sinai Clinical Heart in Los Angeles. These codes, however, never usually address the myriad overall health problems connected to prolonged Covid, he said.

POTS, for instance, does not have a standardized diagnostic code and has only recently been linked to Covid.

Medical doctors may perform tricky to get a patient a formal prognosis for extensive Covid to enable with insurance, even though there is just not an official test for long Covid and the tests that is carried out may well not be protected by insurance coverage.

Some people may possibly finally get coverage soon after submitting an enchantment to their insurance plan, but generally not before shelling out hundreds of pounds, Kwan claimed.

Other folks may possibly not be so blessed and could be forced to fork out for most of their treatment out of pocket.

That is what happened to Amy Cook, 51, of Orange County, California.

Amy Cook.
Amy Cook.Courtesy Amy Prepare dinner

In May possibly, she received Covid, which prompted her multiple extensive-time period health troubles including upper body congestion, erratic heart amount, head aches and visible impairment.

Prepare dinner, who functions a whole-time job as a chief operating officer for a consulting company, reported she was bedbound for four months because of her lengthy Covid indications.

All-around Oct, her physician encouraged that she attempt naltrexone, a drug utilized for opioid dependancy that has shown assure in lifting prolonged Covid signs, as well as hyperbaric oxygen. The two therapies are currently being analyzed in clinical trials as prospective treatment options for the ailment, nevertheless neither is approved by the Foods and Drug Administration for the disease.

Aetna, her insurance policy service provider, declined to go over most of the expense of the therapies.

“I’m at $28,000 to day and I have far more treatment plans coming up,” Cook claimed of her out-of-pocket fees.

Prepare dinner explained she’s at the moment in a monetary placement to be in a position to self-fund the therapies, although she even now has not recovered from her ailment and the bills could simply improve.

“I really do not know when I’ll be ready to prevent,” she explained.

In a statement, Alex Kepnes, a spokesperson for Aetna, mentioned there is no single definition for extended Covid and that coverage conclusions “are based on professional medical requirement and evidence-based guidelines.”

“We are focused and fully commited to giving our customers with accessibility to care and solutions for medically necessary solutions to assistance them tackle their situations and improve their wellness,” he explained.

What can be finished?

Johnson, of the Tennessee Justice Center, explained a affected individual can boost their likelihood of coverage approving their declare by producing guaranteed they have a strategy just before they even enter the doctor’s business.

Her advice:

  • Ask how a lot the treatment will price tag.
  • Request the health care provider to demonstrate obviously on insurance plan paperwork precisely why the treatment was required.

Performing with a medical doctor can be “incredibly successful,” Johnson reported, as they are normally skilled to know what meets insurance providers’ specifications for coverage.

If that will not function, and coverage denies the patient’s assert, the individual can appeal the decision, she reported. Underneath the Reasonably priced Treatment Act, all well being insurance policy ought to have an external attraction approach that permits a patient to problem the provider’s verdict.

“The plan that you could deny solutions without the need of an possibility for attraction is no more time accurate,” she claimed.

If still unsuccessful at this stage, individuals may perhaps begin to panic, Johnson said, simply because the remarkable monthly bill can be taken to collections and individuals can just take a hit on their credit score score. Vendors normally deliver a very brief time window for payment, and appeals typically consider months.

Maness, of California, mentioned she’s panicked at the very least at the time when her coverage company took also lengthy to get again to her on an charm and finished up shelling out hundreds of pounds toward her monthly bill.

What a client does following that will count on their health insurance plan, Johnson said.

People today with Medicaid, for case in point, can acquire the assert to court if they really feel the denial was unjustified. For folks on personal insurance, it really is much less distinct what they can do, but 1 alternative is to make contact with the state’s Division of Commerce and Coverage, which regulates insurance policy firms.

Johnson instructed individuals frame their criticism saying, “You’ve licensed this insurance policies to do this in our condition and they’re denying essential rewards continually.”

Follow NBC Overall health on Twitter & Facebook.

Patient advocates push for aggressive crackdown on medical debt : Shots

Patient advocates push for aggressive crackdown on medical debt : Shots

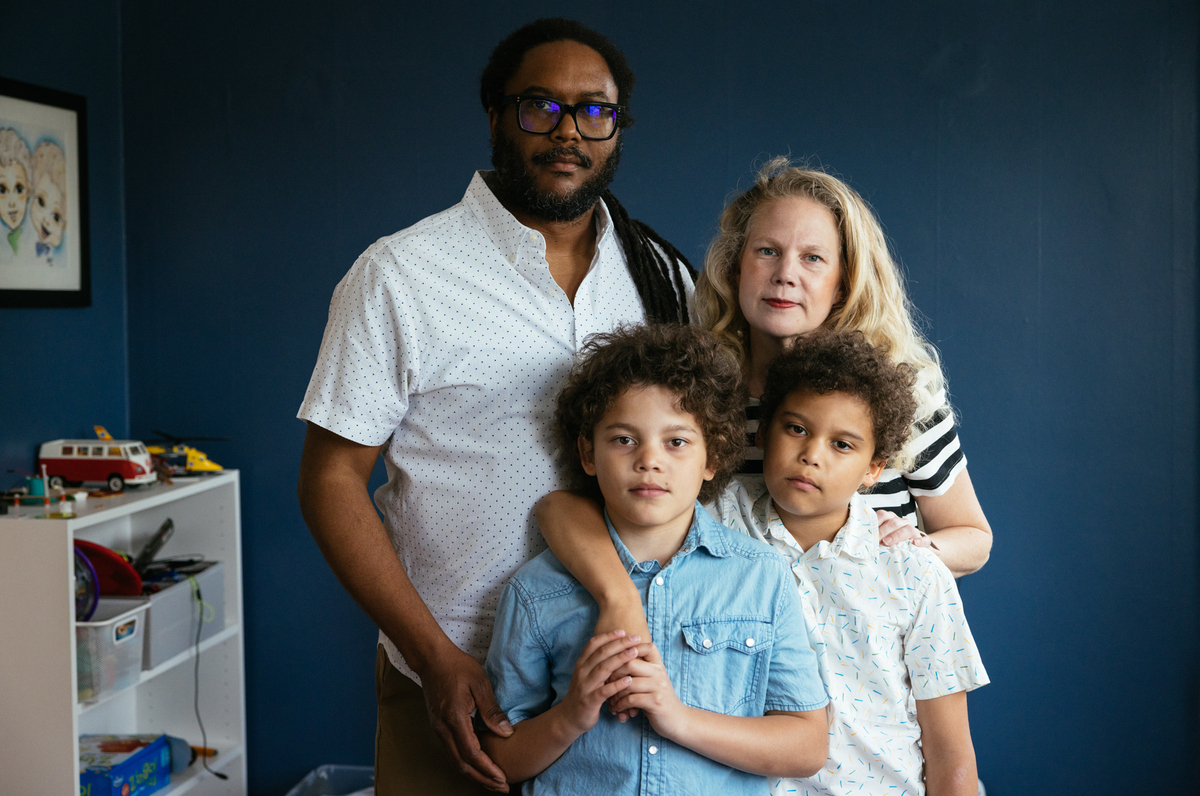
Marcus and Allyson Ward have been spending off a credit card debt dating again to the birth of their twins, Theo and Milo. They are amongst 100 million People with health-related credit card debt, in accordance to a KHN/NPR investigation.

Taylor Glascock for KHN and NPR


hide caption

toggle caption

Taylor Glascock for KHN and NPR


Marcus and Allyson Ward had been shelling out off a personal debt dating back again to the start of their twins, Theo and Milo. They are between 100 million Individuals with health care personal debt, according to a KHN/NPR investigation.

Taylor Glascock for KHN and NPR

Dozens of advocates for clients and individuals, citing common harm brought on by professional medical credit card debt, are pushing the Biden administration to choose more aggressive methods to defend Us citizens from health care bills and personal debt collectors.

In letters to the IRS and the Consumer Money Defense Bureau, the teams phone for new federal procedures that among other matters would prohibit personal debt for medically essential care from appearing on buyer credit rating reviews.

Advocates also want the federal govt to bar nonprofit hospitals from marketing affected person credit card debt or denying clinical treatment to men and women with earlier-because of expenditures, tactics that continue to be popular throughout the U.S., KHN identified.

And the teams are urgent the IRS to crack down on nonprofit clinic programs that withhold economic support from lower-earnings clients or make support cumbersome to get, an additional prevalent impediment KHN documented.

“Every single day men and women are possessing to make alternatives about housing and outfits and food items due to the fact of professional medical financial debt,” claims Emily Stewart, govt director of Group Catalyst, a Boston nonprofit main the exertion. “It’s seriously urgent the Biden administration consider action to set protections in position.”

Amongst the far more than 50 groups supporting the initiative are countrywide advocates these types of as the National Buyer Law Heart, the Arthritis Basis, and the Leukemia & Lymphoma Society.

Nationwide, 100 million persons have wellbeing treatment credit card debt, in accordance to a KHN-NPR investigation, which has documented a disaster that is driving People from their houses, draining their personal savings, and stopping tens of millions from accessing treatment they have to have.

When some of the debt appears on credit score stories, substantially of it is concealed elsewhere as credit rating card balances, financial loans from kin, or payment programs to hospitals and other health care vendors.

The scale of this difficulty and its toll have spurred numerous countrywide and point out endeavours.

Previous spring, the White House directed federal organizations to operate on relieving clinical money owed for veterans and to end contemplating clinical personal debt in assessing eligibility for some federally backed home loans.

California, Colorado, Maryland, New York, and other states have enacted new guidelines to increase client protections and involve hospitals inside their borders to enhance economical help. And the a few greatest credit companies — Equifax, Experian, and Transunion — mentioned they would cease which include some health care credit card debt on credit rating studies as of past July.

But a lot of shopper and patient advocates say the steps, while significant, continue to leave tens of millions of People in america susceptible to fiscal damage if they develop into sick or wounded. “It is vital that the CFPB consider extra action,” the groups write to the federal agency created in 2010 to bolster oversight of client financial merchandise.

The important credit history score providers, for case in point, agreed to exclude only debts that have been paid off and unpaid money owed of significantly less than $500. Patients with greater medical expenditures they can not pay may possibly continue to see their credit scores drop.

The teams also are inquiring the CFPB to do away with deferred fascination on health-related credit score cards. This arrangement is typical for vendors this kind of as CareCredit, whose financial loans carry no interest at first but can exceed 25{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} if individuals you should not fork out off the bank loan in time.

Collection field officials have lobbied in opposition to broader constraints on credit rating reporting, stating limits would get away an critical tool that hospitals, physicians’ places of work, and other health care providers need to accumulate their cash and stay in business enterprise.

“We value the difficulties, but a wide ban on credit rating reporting could have some unintended effects,” explained Jack Brown III, president of Florida-based Gulf Coast Collection Bureau, citing the prospect of battling hospitals and other companies closing, which would lower care selections.

Brown, a previous president of ACA Global, the collection industry’s main trade affiliation, warned that extra health care vendors would also start out demanding upfront payment, putting supplemental stress on sufferers.

To further more shield sufferers from out-of-pocket costs like these, lots of advocates say hospitals, especially people that are exempt from taxes because they are intended to provide the neighborhood, need to make financial aid additional obtainable, a vital desire in the group’s letters. “For far too very long, nonprofit hospitals have not been behaving like nonprofits,” stated Liz Coyle, govt director of the nonprofit Georgia Observe.

Charity treatment is provided at most U.S. hospitals. And nonprofit professional medical units will have to give support as a affliction of becoming tax-exempt. But at several professional medical facilities, information about this assistance is challenging or not possible to discover.

Specifications also differ greatly, with help at some hospitals restricted to sufferers with money as lower as $13,590 a calendar year. At other hospitals, individuals generating 5 or six occasions that significantly can get support.

The outcome is prevalent confusion that has remaining numerous sufferers who really should have been qualified for assist with massive expenses as a substitute. A 2019 KHN analysis of healthcare facility tax filings identified that just about 50 percent of nonprofit health-related units were being billing clients with incomes minimal ample to qualify for charity treatment.

The teams are asking the IRS to concern regulations that would set prevalent requirements for charity treatment and a uniform software throughout nonprofit hospitals. (Present-day polices for charity treatment do not apply to for-gain or general public hospitals.)

The advocates also want the federal agency to reinforce restrictions on how much nonprofit hospitals can demand and to curtail aggressive selection practices these types of as foreclosing on patients’ residences or denying or deferring medical treatment.

Far more than two-thirds of hospitals sue people or choose other lawful motion in opposition to them, such as garnishing wages or positioning liens on assets, according to a current KHN investigation. A quarter sell patients’ debts to personal debt collectors, who in turn can go after patients for several years for unpaid charges. About 1 in 5 deny nonemergency care to people today with excellent personal debt.

“Charitable establishments, which have other solutions of assortment accessible to them, need to not be permitted to withhold wanted health care care as a means to stress individuals to pay,” the groups wrote.

KHN (Kaiser Health Information) is a nationwide, editorially unbiased plan of KFF (Kaiser Family Foundation).

Education Department releases new data on 25M applications for Biden’s student debt relief

Education Department releases new data on 25M applications for Biden’s student debt relief

Biden administration officials had previously only provided approximations of the number of borrowers who filled out applications to apply for the program, which provides up to $20,000 of debt relief for federal student loan borrowers.

The new federal data details, for the first time, the precise number of borrowers who filled out applications and where they live.

The Education Department received the most applications from some of the nation’s most populous states: California (2.2 million applications); Texas (2 million); Florida (1.5 million); New York (1.5 million); Pennsylvania (1 million); Ohio (1 million); Illinois (1 million); and Georgia (about 950,000).

The data does not include information on borrowers who did not apply but were deemed automatically eligible for relief because the Education Department already had their income information on file. But many of those borrowers also submitted applications.

The Biden administration was widely praised among Democrats for setting up an easy online application for borrowers to apply for the debt relief program. But the data also highlights some significant gaps in which borrowers filled out the application compared to the White House’s earlier estimates of the number of borrowers who may be eligible.

For example, the data shows that Massachusetts borrowers submitted 563,740 applications in the first month of the program — nearly 70 percent of the 813,000 borrowers that the administration estimated would be eligible in that state.

Wyoming borrowers, by contrast, submitted 26,869 applications — only about half of the 49,600 borrowers the administration estimates qualify for the program.

The new data also shows the huge influx of applications in the days after the Biden administration launched the application in mid-October, just weeks before the midterm elections.

Several million applications poured into the Education Department each day in the week following the announcement. In the following weeks, the department continued to receive hundreds of thousands of applications each day. More than 100,000 borrowers were applying each day when the application was taken offline on Nov. 11 in response to a federal court order.

About 76,000 borrowers applied for student debt relief using the Spanish-language version of the application, according to the data.

The Supreme Court is preparing to decide the fate of Biden’s student debt relief program in the coming months. The justices in February will hear arguments in two legal challenges brought by six Republican-led states and a conservative group.

Full state-by-state data as released by the Education Department under a FOIA request:

State/Location Application Count
California 2,202,565
Texas 2,035,304
Florida 1,541,485
New York 1,503,527
Pennsylvania 1,097,017
Ohio 1,028,607
Illinois 1,010,760
Georgia 950,796
Michigan 825,115
North Carolina 756,341
New Jersey 728,853
Virginia 647,129
Massachusetts 563,740
Indiana 509,517
Maryland 501,545
Tennessee 486,453
Minnesota 478,809
Arizona 467,406
Washington 460,471
Missouri 455,114
Colorado 442,594
Wisconsin 438,453
South Carolina 411,260
Louisiana 355,256
Alabama 351,250
Kentucky 346,467
Oregon 312,521
Connecticut 307,628
Oklahoma 253,233
Iowa 248,375
Mississippi 234,906
Puerto Rico 224,268
Kansas 212,824
Arkansas 207,871
Nevada 188,656
Utah 172,465
Nebraska 144,049
West Virginia 124,330
New Mexico 117,728
Idaho 116,052
New Hampshire 113,643
Maine 108,789
Rhode Island 92,322
Delaware 77,408
District of Columbia 70,979
Hawaii 70,849
South Dakota 68,698
Montana 68,338
Vermont 49,615
North Dakota 47,884
Alaska 35,907
Wyoming 26,869
All Other Locations 53,734
Not Yet Matched to Borrower Data or Address Unavailable 686,129

How to Use Debt to Build Wealth | Family Finance

How to Use Debt to Build Wealth | Family Finance

In accordance to the Federal Reserve Bank of New York, overall American household debt equaled $16.51 trillion in the 3rd quarter of 2022, a 2.2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} increase over the next quarter of the year. But while credit card debt frequently receives a poor rap in personal finance circles, it is not usually a detriment to own funds.

“Debt can be an really strong device when utilised correctly,” Michael Tanney, senior running director of New York-based mostly Magnus Financial Team, suggests.

But like most powerful applications, if you use it improperly it can damage you. It’s vital to just take on debt for the right motives and beneath the correct guidance, he suggests.

When you use debt responsibly it can assistance you attain financial security and develop your web worth. Keep reading to study how.

How Great Credit card debt Differs From Terrible Credit card debt

Fiscal gurus say you will find good financial debt and poor debt. Great credit card debt involves financial loans – like home loans, scholar financial loans and small company loans – that allow you to purchase an asset with the opportunity to obtain benefit about time. (In the situation of scholar financial loans, you’re gaining obtain to a vocation that will most likely afford you larger potential earnings.)

Undesirable credit card debt normally features high-curiosity monetary products – like credit history cards – you use to order items that decrease in worth or that you promptly eat. This form of debt can turn out to be a drag on your funds and prevent you from assembly other money goals.

Grant Sabatier, creator of the private finance web site Millennial Revenue and creator of “Fiscal Liberty,” suggests that when we hear about poor personal debt, it is commonly pertaining to credit history cards with superior desire rates.

When you make only minimum payments on credit history card accounts, the volume you owe continues to increase and compound promptly and can set you deep into debt ahead of you know it. Negative debt also features payday and other predatory loans, Sabatier claims.

How to Build Wealth When You’re in Debt

When you use debt house, it shouldn’t prevent you from growing your web really worth above time. Stick to these steps to take control of your financial debt and get ahead financially.

Shell out Down Significant-Interest Debt Initially

If you’re carrying balances on your credit history playing cards, halt applying them for a while. Direct your money toward spending down people balances each month, starting off with the best-desire card 1st.

Credit rating playing cards can serve as a fantastic software to improve your credit history rating, increase dollars flow and rack up rewards details. But if you are carrying a equilibrium just about every month, the curiosity price will commonly outweigh any of all those rewards. Switch to applying a debit card or income till you pay out off your playing cards.

Established Apart Savings

Location aside from three to six months of cost savings will assistance stop you from heading back into financial debt if an crisis – like an unforeseen dwelling maintenance or work decline – occurs. Goal to place some money into your unexpected emergency fund each thirty day period and at least more than enough into a retirement account to get benefit of your employer’s match.

“You really don’t want to use an all-or-almost nothing strategy to spending down personal debt that would alienate your other monetary targets,” John McCafferty, director, monetary arranging at Edelman Economic Engines, says.

Take On Supplemental Credit card debt Only if You Have a Plan to Pay back It Back again

Whether or not it’s a smaller small business financial loan, university student financial loan or mortgage loan, imagine diligently about the volume of cash you want to borrow and irrespective of whether you are going to have the sources to pay back it back again. For illustration, if you are likely back to school and using out a financial loan, make confident your projected salary immediately after graduation will help you to comfortably make the payments.

Never Eliminate Your ‘Good Debt’ Way too Rapidly

If you have been a single of the millions of Us citizens who took benefit of report low interest prices in the past 10 years and secured a home finance loan at a rock-base rate, don’t rush to pay out it off.

In its place, place that dollars you would use to spend down your property finance loan into a substantial-generate price savings account. You could generate up to 4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} desire that way, which would be a better return than you’d get paying out off a 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} home finance loan. Or, make investments the cash in the stock sector. Even though it can be unpredictable suitable now, if you really do not need to have the cash in the near long term it could possibly be a great spot to set some dollars.

“The inventory industry has historically made an regular of 8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} for each yr, depending on the time period of time that you search at,” Paul Dietrich, chief expenditure strategist at B. Riley Wealth, claims. “If your personal debt is less than that, you may well target on investing instead.”

How a government debt ceiling crisis could affect future travel

How a government debt ceiling crisis could affect future travel

The U.S. government has just reached its debt ceiling for the first time since 2011.

Though lawmakers funded the federal government through the end of the fiscal year 2023 in December, they still borrow money to fund ongoing operations via a debt ceiling.

“The federal government is like any other person with a credit card in that it limits how much it can borrow to finance extra spending, known as the debt ceiling. That’s essentially to ensure the government can still fund its legal obligations,” Sarah Foster, an economy reporter for Bankrate (a publication owned by TPG’s parent company, Red Ventures), explained. “But running the world’s largest economy gives you special privileges because, unlike when you hit your credit line, Congress can continue committing to new spending.”

“When this happens, the Treasury Department can take ‘extraordinary measures’ to move money around and ensure the nation doesn’t default on its bills,” Foster said. “But each day will be like a ticking clock — Treasury Secretary Janet Yellen estimates she’ll have run out of tricks to help the government avoid default by early June. “

If this June default happens, the federal government might fail to extend funding for certain government programs, potentially affecting travel if you want to visit a national park, renew your passport or Global Entry membership and more.

Here’s what you need to know — and what you can do now to minimize impacts to your plans — if this does come to pass.

Global Entry, TSA PreCheck and passport applications

Trusted Traveler programs, such as TSA PreCheck and Global Entry, are operated by U.S. Customs and Border Protection under the U.S. Department of Homeland Security. This means any pause in funding could curtail the ability to process applications.

Plus, the government is already facing a pandemic-induced backlog of applications and is currently warning of extended wait times.

U.S. DEPARTMENT OF HOMELAND SECURITY

Similarly, the U.S. Department of State is currently telling travelers that routine passport service can take six to nine weeks, with three to five weeks for expedited service.

Sign up for our daily newsletter

Potential funding issues aside, we recommend applying for and renewing your Trusted Traveler program memberships and U.S. passports as soon as they are eligible for renewal. The process can take time, and many countries will not allow you to enter with less than three months left on your passport — some even require six months of validity remaining.

Beyond application processing times, a government funding delay could result in a shortage of Transportation Security Administration agents at airports, potentially increasing wait times for TSA PreCheck lines at certain airports.

During the 2018-2019 government shutdown — which lasted 35 days and was the longest in history — flights were canceled due to staffing shortages among TSA agents and air traffic controllers. Additionally, some airports closed TSA security lines.

National parks

As a federal agency under the U.S. Department of the Interior, the U.S. National Park Service is primarily funded by Congress.

If funding were to stall, you could still enter some national parks, and some roads, lookouts, trains and open-air memorials would likely still be accessible. Everything else — including essential services such as visitor centers, restrooms and educational programs within the park — is run by NPS staff and would therefore be affected.

Though visiting a park during this time technically would be free, a lack of staff would result in the park being less safe overall, thanks to the absence of park rangers to actively monitor the grounds without active search and rescue services.

Contracted hotel companies run hotels within parks, so in theory, these would remain open since they don’t rely on NPS staff.

In the past, we’ve seen third parties intervene to help keep national parks open in the face of a government shutdown. Though a government shutdown is not on the line here, the same groups could potentially step in to avoid park closures.

For example, in 2018, then-Arizona Gov. Doug Ducey signed an order to keep the Grand Canyon open via state revenue funding.

“The park gates stayed open, but nobody was working the toll booths to collect the usual $35 fee per car to get in the park,” per reporting by The Arizona Republic.

Therefore, states and private entities, including volunteer groups, could act to keep national parks open.

Ultimately, the decision to keep parks open during a shutdown lies in the hands of the president in office at the time of the shutdown.

Washington monuments and museums

Federally funded monuments and museums in Washington, D.C., would also be at risk. This includes the 17 Smithsonian museums and galleries and National Zoo, plus the NPS-run memorials, such as the Lincoln Memorial and the National Mall, which are usually staffed by NPS rangers.

In the aforementioned government shutdown, the Smithsonian used funds to remain open through Jan. 1, 2019, leaving the park closed for 24 days.

Bottom line

KENT NISHIMURA/LOS ANGELES TIMES/GETTY IMAGES

Hopefully, there won’t be government-related staffing shortages in 2023. However, with the looming potential of a reality where that happens, it’s best to apply for or renew relevant government documents you may need to travel now.

For more information on Trusted Traveler programs, read: