Hospitals and health care facilities should drop mask requirements, medical experts say

Hospitals and health care facilities should drop mask requirements, medical experts say

Even after mask mandates were dropped across the country amid dwindling COVID-19 cases and deaths, face coverings have still been required in many doctors’ offices, hospitals and other health care settings.

Now, a group of esteemed medical experts is calling for a change.

In an April 18 journal entry in the Annals of Internal Medicine, an academic medical journal, several physicians — including infectious disease specialists — wrote that it’s time to remove masking requirements in health care facilities.

“While critically important in the earlier phases of the pandemic, we’ve entered a more stable phase, with substantial population-level immunity, durable protection against severe disease, a series of less virulent variants, and other important and favorable changes,” said corresponding author Erica S. Shenoy, M.D., PhD, in a press release. 

FACE MASKS MADE ‘LITTLE TO NO DIFFERENCE’ IN PREVENTING SPREAD OF COVID, SCIENTIFIC REVIEW FINDS

She is the medical director of infection control for Mass General Brigham and an infectious diseases physician at Massachusetts General Hospital in Boston. 

“As conditions change, we need to re-evaluate our infection prevention policies, including masking requirements in health care settings, and adapt,” she added.
Patients in masks

Even after mask mandates were dropped across the country amid dwindling COVID-19 cases and deaths, face coverings have still been required in many doctors’ offices, hospitals and other health care settings. Now, a group of doctors is calling for this to end.  (iStock)

Other contributing physicians came from Harvard Medical School, Washington University School of Medicine, University of Iowa College of Medicine, Dartmouth Hitchcock Medical Center, Tufts University School of Medicine and Trinity Health Michigan. 

“Masking requirements in health care have continued longer than in the community because these settings have a higher proportion of individuals at high risk for complications of infection,” the authors wrote in the journal entry.

“However, the context and conditions of the pandemic have changed dramatically and favorably since masking requirements in health care were initially adopted, and evidence-based public health policy should also adapt in response.”

‘Makes complete sense’

Dr. Marc Siegel, a professor of medicine at NYU Langone Medical and a Fox News contributor, agreed with the decision.

“It makes complete sense to remove the universal mask requirements for medical centers — and NYU did it weeks ago,” he told Fox News Digital. “It hasn’t made sense for a while.”

“We should adapt mask policies to reflect this new reality.”

Dr. Shana Johnson, a physical medicine and rehabilitation physician in Scottsdale, Arizona, reviewed the doctors’ recommendations.

“As we transition to the place where SARS-CoV-2 is a constant and stable presence in our community, we should adapt mask policies to reflect this new reality,” she told Fox News Digital. 

Weighing costs, benefits

In the journal entry, the authors pointed out that masking in health care settings was appropriate early in the pandemic as a means of limiting spread among medical personnel, patients and visitors.
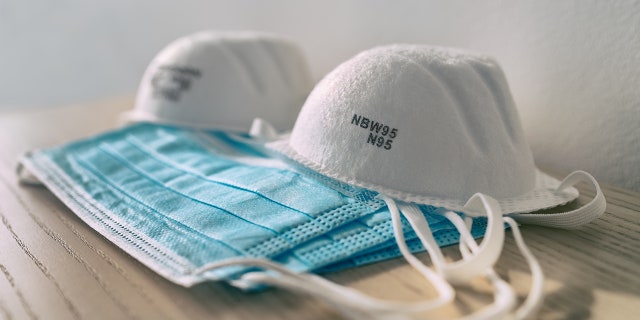
Photo shows piles of face masks, including surgical masks and N95 masks

Dr. Marc Siegel of New York City said he continues to wear a KN95 or N95 mask in the room with most patients, especially those with respiratory symptoms. He said, however, that it “makes complete sense to remove the universal mask requirements for medical centers.” (iStock)

But as the population has achieved greater immunity and COVID has entered a “more stable phase” — and as public health agencies and the U.S. government have declared that the public health emergency is over — the physicians stated in the findings that the small benefits of continuing to require masks don’t justify the costs.

“Masks do have downsides, such as impaired communication and disrupted human connection.”

“After three years of universal masking in health care, the risk-benefit calculation has shifted,” said Shira Doron, M.D., chief infection control officer for Tufts Medicine health system and hospital epidemiologist at Tufts Medical Center, in the press release announcing the paper. 

“Masks do have downsides, such as impaired communication and disrupted human connection.  We are at a stage of the pandemic where it now makes sense to end mandatory masking,” she added.

PARENTS NOW QUESTION WHETHER COVID MASK MANDATES DID MORE HARM THAN GOOD

Among the drawbacks of masks, the study authors cited an “increased cognitive load” for doctors who are trying to listen to patients wearing face coverings. 

This is particularly difficult for patients who do not speak fluent English or who are hard of hearing, they added.

“Masks obscure facial expression; contribute to feelings of isolation; and negatively impact human connection, trust and perception of empathy,” the authors wrote.

“Masking is not without its downsides,” Dr. Johnson said. “Masks make it more difficult to hear, understand and communicate with your provider. Some choice makes sense.”

‘Standard precautions’ should be used

In lieu of universal masking, the study authors suggested that health care settings should follow “Standard Precautions and Transmission-Based Precautions,” as outlined by the Centers for Disease Control and Prevention (CDC).
Patients without masks

“Masks obscure facial expression; contribute to feelings of isolation; and negatively impact human connection, trust and perception of empathy,” the authors wrote. (iStock)

Health care personnel should wear masks to prevent exposure as needed, according to those guidelines. 

Also, any people with respiratory symptoms (namely, coughing or sneezing) should use a face covering.

Additionally, if a medical worker is “caring for patients with suspected or confirmed respiratory infection, they should use personal protective equipment and other interventions.”

Rather than having universal masking requirements, Dr. Siegel believes the decision should be “based on individual risk.”

“Universal masking in health care is a policy whose time has come and gone … for now.”

“It should be reserved for patients who are immunocompromised or severely or chronically ill or the doctors that care for them,” he told Fox News Digital. “Patients who are acutely ill and those with chronic lung problems should continue to wear masks.”

The doctor said he continues to wear a KN95 or N95 mask in the room with most patients, especially those with respiratory symptoms.

“Certain health care settings with high-risk patients could still choose to use universal masking, but it would not be required in other areas of normal risk,” added Dr. Johnson.

Reconsidering other early-pandemic precautions

Along with dropping mask requirements in health care settings, the physicians wrote that other protocols should be reconsidered.
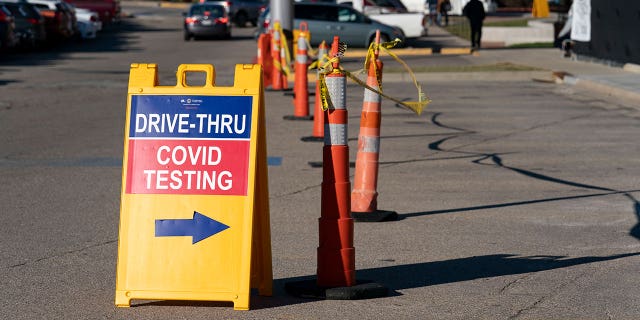
COVID testing

The doctors wrote that in addition to universal masking, other early pandemic strategies, such as asymptomatic testing and contact tracing, should also be reconsidered. (AP)

“Moving away from universal masking policies should be accompanied by reconsideration of other pandemic-era strategies (for example, asymptomatic testing, resource-intensive contact tracing), which similarly have experienced a shift in their risk-benefit balance over the course of the pandemic,” they stated in the discussion.

Potential for masking to return

The latest commentary doesn’t mean that masking policies won’t return sometime in the future, the physicians noted.

“Future pandemics or significant localized outbreaks may justify more widespread or targeted masking policies, respectively, as part of a bundled response,” they wrote, noting that it’s important to educate health care personnel and patients as policies change.

COVID-19’S LASTING IMPACT: ‘LESS ATTRACTIVE’ PEOPLE WEAR MASKS MORE OFTEN THAN OTHERS, STUDY FINDS

“Change and adaptation are expected,” said senior author Dr. Westyn Branch-Elliman, an infectious diseases specialist and clinical investigator at VA Boston Healthcare System. 

“That does not mean ‘the science has changed,’ but almost everything around it has.”

The doctors called for “focused research” to “ensure requirements are not maintained longer than necessary and are reinstated when needed.”

Additionally, the authors noted that the Healthcare Infection Control Practices Advisory Committee (HICPAC) at the Centers for Disease Control and Prevention (CDC) “is currently reevaluating existing approaches to Transmission-Based Precautions, which is likely to inform future considerations for health care transmission mitigation strategies.”
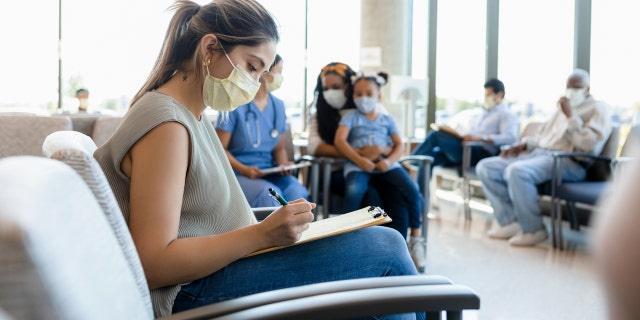
Hospital waiting room

The authors pointed out that masking in health care settings was appropriate early in the pandemic as a means of limiting spread among medical personnel, patients and visitors. Now, however, they said that “universal masking in health care is a policy whose time has come and gone … for now.” (iStock)

“The time has come to de-implement policies that are not appropriate for an endemic pathogen when the expected benefits of such policies are low,” they concluded. 

“Universal masking in health care is a policy whose time has come and gone … for now.”

CLICK HERE TO SIGN UP FOR OUR HEALTH NEWSLETTER

COVID cases and deaths continue to decline. 

As of April 19, the CDC reported 94,142 weekly deaths in the U.S., down from a peak of 5.5 million in January 2022. 

Weekly deaths from COVID were down to 1,160; the highest count was 23,629 in January 2021.

CLICK HERE TO GET THE FOX NEWS APP

The World Health Organization released updated masking guidelines in January 2023. 

Despite the decreasing COVID numbers, the agency stated that “masks are recommended following a recent exposure to COVID-19, when someone has or suspects they have COVID-19, when someone is at high risk of severe COVID-19, and for anyone in a crowded, enclosed or poorly ventilated space.”

As home prices drop, Colorado’s real estate industry looks to history to understand trends

As home prices drop, Colorado’s real estate industry looks to history to understand trends

If you’re house hunting, there are plenty of homes available in Colorado — nearly 10,000 at the end of March, which is up 41.8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from a year ago. 

Prices are a bit lower, too.

If you need a loan to pay for the house, though, that’ll cost more than it would have a year ago. Even so, mortgage loan rates are about where they were in 2008. And that’s roughly two-thirds lower than the peak in the early 1980s.

In this Oct. 22, 2019 file photo, a sign stands outside a home for sale in southeast Denver. (AP Photo/David Zalubowski, File)

The way Colorado Realtors see it is that while the for-sale market has slowed significantly and median sale prices have dropped, it’s been worse. Way worse. And now, the market appears to be settling down with the latest inflation report showing prices aren’t rising as fast as before and the Federal Reserve considering a pause on upping interest rates.  (More on that below.)

“The reality is that there’s a bunch of people that need to buy and sell homes. Their life situation changed. That’s a natural thing. It’s not like the world’s come to an end. It’s just slowing down,” said Realtor David S. Anderson, with Re/Max of Pueblo. “And we’re probably getting more to a more neutral market that we haven’t been in since ’19 when you were looking at three to four months on the market.”

Anderson has a point. Just look at the March home sales data from the Colorado Association of Realtors between 2014 and 2023. 

The count of houses sold in March is closer to where it was in 2019 in the seven-county Denver metro area, according to the latest “Market Trends” report from the Colorado Association of Realtors. Statewide, the number of days a house sat on the market before someone bought it was back to the more leisurely pace of 2019 as well. As for inventory? Bidding wars are rarer. Houses are available, though there are fewer for sale now than two years ago. 

In the largest market, median sale prices fell 12.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to $650,000 in the city of Denver, and that’s kind of a relief for the real estate industry because the frenzy pushed prices up so high, many prospective buyers left disappointed even after offering more than the asking price on multiple properties. 

“It’s like the heavens have opened up and a giant eraser has come down from the sky and is just kind of erasing all of the 2021 and 2022 madness,” said Matthew Leprino, CEO of Denver-based real estate brokerage Remingo. “Yes, prices are decreasing (but) they’re still higher than they were in 2020. And ’21 and ’22 were weird. They were bad. They were really expensive. But we don’t appear to be going into a huge regression. It might just be that we’re bouncing back out.”

The low interest rates in the past couple of years — between 2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} — are gone, with mortgage loan rates at 6.39{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, as of Friday, according to Mortgage News Daily. Buying a lower-median-priced home in Denver at today’s higher interest rate is nearly $300 more per month than last year’s higher-priced home at a lower interest rate according to Bankrate’s mortgage calculator. 

“The public has gotten very spoiled thinking they should get a 2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} or 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} interest rate. That’s not going to happen again,” Anderson said. “If you get down into 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, you’re getting a damn good interest rate. And 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} is actually very good.”

A home is listed for sale on Oct. 20, 2022 near Lookout Park in western Arvada. (Olivia Sun, The Colorado Sun via Report for America)

Buyers haven’t stopped buying houses in Colorado. 

Sunny Banka, who sells houses in Aurora and Centennial, blamed cold weather for keeping people from home shopping in March. But in April, she’s expecting different results. Shoppers have had a year to get used to higher interest rates. Currently in Aurora, there are 409 single family houses for sale and 418 with pending sales. 

“We are getting bidding wars,” said Banka, who has been a Realtor for 44 years. “A (colleague) put a $550,000 home on the market over the weekend and had 80 showings and 14 offers. It sold for about $30,000 over (the list price).”

The house must be priced right and in a good neighborhood, said Banka, whose clients are split between buyers and sellers. She said she has to educate them about what it takes to be in the housing market today. 

What’s also been helping? Relatives, she said. 

“What I’m seeing is there’s a lot of grandma, grandpa, great aunt money, mom and dad, who are helping with the down payment to help offset those higher interest rates for first-time homebuyers,” she said.


Denver inflation higher than the US

Higher housing, energy and food costs were reasons for the Denver-area’s 5.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} inflation rate increase in March from a year ago. This was higher than the national 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} rate, according to the U.S. Bureau of Labor Statistics, which does not track inflation rates by states. 

The good news for consumers is that this means prices aren’t rising as fast as they were last year. But this also means that consumer prices are still rising, and that’s on top of March 2022’s 9.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} increase. The top items that changed in price last month:

▲▲ Higher ▲▲  

  • Nonalcoholic beverages were up 16{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} 
  • Fruits and vegetables, up 14.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} 
  • Dairy and related products, up 12.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}
  • Rent of primary residence, 10.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}
  • Food away from home, up 10.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}
  • Owners’ equivalent of rent, up 7.8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}
Health and wellness manager Jennifer Pham, right, and project manager Joan Deming, place fresh fruits and vegetables out on shelves before shoppers arrive at the Clayton Cares Market on the Clayton Early Learning campus in Denver. (Kathryn Scott, Special to The Colorado Sun)

▼▼ Lower ▼▼

  • Used cars and trucks, down 11.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}
  • Gasoline, all types, down 2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}
  • Electricity, down 2.9{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}
  • Medical care, down 0.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}

You may not have noticed the increases because we had experienced much higher inflation last year, when the Denver-area rate hit 9.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in March 2022. That jump from the Federal Reserve goal of 2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}-3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} seems to make the latest increase less of a shocker.

“We’re still accelerating fast, just not accelerating as fast as we were a few months ago,” said Joe Craig, interim faculty director for the University of Colorado Colorado Springs Economic Forum. “That’s hard for consumers to notice. I would posit that a lot of consumers are still thinking, ‘Oh my god, prices are still going up. Why is the Fed still doing this? They’re slowing down our economy.’ Yes. But not at the same rate, which is a hard concept to get across and a hard concept to feel because we’ve been anchored to that 2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.”

Inflation hits lower-income households much harder than the better off. When the price of a dozen eggs or a gallon of gasoline increases, everyone pays the same amount. 

Higher inflation here “probably is just indicative of the fact that Denver is wealthier on average than the West as a whole and the nation,” Craig said. “The higher income brackets are still continuing to spend and that’s probably what we’re seeing with higher inflation in Denver. It is unfortunate though for the working class of Denver, but there’s always a tension like that in popular big cities.”

Looking at core inflation of the past two months, however, points to a more regional impact, said Brian Lewandowski, executive director of the Business Research Division at the Leeds School of Business, University of Colorado Boulder. Remove the volatile pieces like food and energy prices and Denver’s core inflation was at 5.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, or the same as the nation’s.

“I think the difference is really that the supply issue that we had was a more local phenomenon that drove up fuel prices locally,” he said. “I would expect that to come down because our prices are now coming down pretty quickly. … And on the housing front, we’re still leading the nation down in terms of (Federal Housing Finance Agency) home price index. I think we’re actually going to see the Denver metro region normalize with the U.S. as we progress through the year, perhaps even lower than the U.S.”

➔ Hmm… gas prices are up again. According to the AAA gas price tracker, Colorado’s average price for a gallon of regular gas was $3.57 on Friday, up 11 cents from last week and down 32 cents from a month ago. US prices also went up by 8 cents in a week. AAA’s explanation? “The main culprit is the high cost of oil, gasoline’s main ingredient, which is hovering in the low $80s per barrel. The national average has risen daily since March 29.” >> See gas prices

How it’s going for some Sun readers

Sun readers seem to be doing OK. Roughly 40{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} responded to last week’s reader poll that their household budgets are the same as last year, though half of that group said it’s because things cost more so they’re buying less but spending the same amount.

Nearly half of respondents feel that the economy’s impact on their life is more or less the same as last year.

Kristiana Huitrón, from Colorado Springs, said that helping her adult children has added to her budget. “I wish my adult children could get jobs that cover medical insurance and retirement and that paid them a wage that would sustain them over their lifetimes,” she wrote.

Cutting down on eating out was the top expense cut from household budgets. The second? Cable TV and other traditional paid-TV services. “Not paying for satellite was the best decision ever,” wrote a person from Arvada. 

On the other hand, Laurence Slivon from Durango didn’t mind paying more for Starlink, the satellite internet service, and for streaming video services. Slivon, who said he’s retired, is ready to splurge. He picked the “Haven’t cut anything” option in the poll.

After an initial big purchase on an electric vehicle, Louisville resident George Burson said he cut out gasoline, which used to set him back about $50 a month. “Since we have solar panels, my electric bill didn’t go up when we got the EV,” he wrote. “I’m adding more solar panels both for the environment and to keep the electric bill down.”

Thanks to everyone who participated in last week’s reader poll. Here’s the next one:

Take the poll: Housing


Other working bits

➔ Denver-based unicorn is now called Guild. Access to higher education has helped employees at Walmart, Disney, Chipotle and others get ahead thanks to their partner Guild Education, the Denver company valued above $1 billion based on venture investment. Now Guild has dropped the second part of its name to bolster their career advancement at those companies. A goal is to offer workers more opportunities and help employers retain staff. CEO Rachel Romer said in a statement, “We are building a movement that lifts up the moral imperative to accelerate access to opportunity for America’s workforce.” >> More from Guild 

➔ Law bans deceptive solicitations for business fees. If you paid more than $1 to register a trade name in Colorado, you paid too much. And now anyone behind deceptive marketing practices to trick businesses into paying “exorbitant costs” could face penalties of up to $20,000 for each violation, according to Senate Bill 37, which was signed into law by Gov. Jared Polis on April 11. The Colorado Secretary of State’s office handles new business formations, change of ownership and other business filing requirements online and probably at a cost lower than you’d think. >> See list of Colorado’s business fees

➔ Colorado mission-driven funds get $30.7 million. Community Development Financial Institutions, often the only financial lender in a community that works with low- and moderate-income clients who traditional banks often won’t consider, received a $1.73 billion boost from the U.S. Treasury Department. Nine are in Colorado and received a total of $30.7 million. That includes First Southwest Bank in Alamosa. Bank CEO Kent Curtis said that First Southwest plans to use the funds to support new loan programs, such as one that will help rural water distribution systems in low-income areas in southwestern Colorado and the San Luis Valley. Here’s the list of Colorado recipients:  

  • Colorado Enterprise Fund, Inc., in Denver, $3,718,258
  • Community Choice Credit Union, in Commerce City, $2,478,839 
  • Community Enterprise Development Services in Aurora, $955,179 
  • First SouthWest Bancorporation in Alamosa, $4,957,678 
  • Impact Development Fund in Loveland, $3,718,258
  • Mercy Community Capital in Denver, $2,478,839 
  • Native American Bank in Denver, $4,957,678
  • NuVista Federal Credit Union in Montrose, $3,718,258
  • Oweesta Corporation in Longmont, $3,718,258

Thanks for sticking with me for this week’s report. As always, share your 2 cents on how the economy is keeping you down or helping you up at cosun.co/heyww. ~ tamara 

Don’t miss the free weekly newsletter on Colorado jobs and unemployment. Sign up: ColoradoSun.com/working

Miss a column? Catch up:

What’s Working is a Colorado Sun column about surviving in today’s economy. Email tamara@coloradosun.com with stories, tips or questions. Read the archive, ask a question at cosun.co/heyww and don’t miss the next one by signing up at coloradosun.com/getww. 

Support this newsletter and get Colorado economic news weekly. coloradosun.com/join 

TEA official says public school funds could drop with voucher-like programs

TEA official says public school funds could drop with voucher-like programs

Real estate housing market in 2023 could lead to drop in home prices

Real estate housing market in 2023 could lead to drop in home prices

When Will Housing Prices Drop? | Real Estate

When Will Housing Prices Drop? | Real Estate

For just about any house owner, talk of slipping housing prices can spark panic. With homeownership currently being the major fiscal and own expense it is, you can find a all-natural anxiety that will come with any opportunity danger to that expense.

However, housing market place exercise to day does not demonstrate a yr-over-yr decrease of household prices on a national scale – at least not nonetheless. Whilst some information sets present thirty day period-to-thirty day period home rate declines, month-to-thirty day period details is more volatile and does not sign a drastic change in the sector on its possess.

There is a marked deceleration in home value advancement thanks to a mixture of presently higher household prices, high home loan interest fees, small housing stock and financial uncertainty on a greater scale. Numerous would-be homebuyers are just opting out of a buy now.

As a final result, properties on the sector sit a bit lengthier, and sellers are dropping their asking costs extra usually than all through the preceding two several years, when purchaser activity was red-sizzling and dropping a listing cost was nearly unheard of.

“Right now you’ve obtained some residence sellers that are delayed in their thinking that the price ranges are what they have been 6 months ago,” suggests Nick Bailey, president and CEO of Re/Max.

To support you much better understand the information, we’re breaking down the different kinds of value drops, declines and decelerations you may hear about, as well as what this indicates for property prices now and in the long term.

When you hear about house costs dropping, it can signify 1 of a couple various matters. Make clear which type of dropping price tag it could be:

  • Listing price tag drops. If a household is sitting down on the sector and not receiving considerably fascination, the listing agent and vendor will most likely have a conversation about dropping the home’s inquiring price. “If we really don’t get the traction and we’re accomplishing every little thing we can … the sector will notify us what we require to do,” claims Mary Anne McMahon, broker owner of Re/Max Posh Properties in Austin, Texas. When you see far more listing value drops on a bigger scale, it is a sign that a restricted seller’s marketplace is easing up and most likely beginning to favor potential buyers. Listing cost drops frequently coincide with for a longer period median days on the industry.
  • Deceleration of sale cost boosts. Home sale prices can nevertheless see yr-above-year will increase, but at a a great deal slower level than formerly. In the closing 4 weeks of 2022, the median home price tag was $350,000, .5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} larger than the remaining 4 months of 2021, in accordance to Redfin.
  • Thirty day period-around-month property selling price declines. If the median residence sale price tag in June was decrease than in May perhaps, for instance, that is viewed as a declining month-to-thirty day period price. Nonetheless, since of the mostly seasonal character of the housing industry, thirty day period-to-thirty day period figures are normally regarded too volatile to suggest shifting traits except put into a more substantial context.
  • Declining home values. A declining residence worth takes place when the appraised marketplace price is considerably less than the rate a purchaser paid for it. A property owner is only underwater if the industry value of the dwelling drops beneath the amount of money owed on the residence by means of home loans or other liens. “If you obtain 40{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} (in residence value) and your selling price comes down 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, you are even now effectively ahead,” Bailey suggests.

Dwelling sale selling prices are nevertheless climbing 12 months-around-calendar year, even though at a decelerating amount, and with current month-more than-thirty day period declines. The countrywide median residence sale rate in November 2022, at $370,700, is 3.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} greater than in November 2021, the most latest information offered, in accordance to NAR. It was the 129th consecutive month of calendar year-more than-12 months enhance in the median home value, the longest-functioning streak of increasing calendar year-over-12 months price ranges, for each NAR info.

Realtor.com experiences the countrywide median listing rate for homes active on the current market in November was $416,000, an 11{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} maximize in comparison to November 2021.

What could feel like a sizeable distinction for household on the current market, nevertheless, is that “we’re not seeing houses – throughout, truly, virtually all marketplaces – provide for in excess of asking,” Bailey suggests.

The median days on current market in September also greater 15{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} yr-more than-calendar year to 56 days – a major alter as opposed to 2021, supplied that numerous recent homebuyers try to remember having to scramble to make an offer you the working day a assets was listed on the current market, but on par with the elevated range of days on current market considering that at minimum slide 2022.

Looking at present-day market traits and wanting forward, expect far more varied final results between different components of the nation.

“We really don’t assume we will see double-digit selling price declines nationally, but in some marketplaces, we are probable to see far more stark declines,” wrote Ruben Gonzalez, main economist for nationwide brokerage Keller Williams, in an e mail.

“Those regions that took the highest amount of appreciation, people are the locations that are down,” Bailey claims.

One particular instance is Boise, Idaho, which has been rising at an outstanding tempo for a couple of several years and observed important curiosity in the course of the peak of the COVID-19 pandemic. On the other hand, the latter months of 2022 saw the market place transform.

Redfin experiences the median sale price tag in the Boise market place in November 2022 was $470,000, a 1.9{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} 12 months-around-calendar year minimize.

Austin, Texas, saw quick value boosts before the pandemic started, during which property charges entered warp pace. Redfin studies the median sale selling price in the Austin current market in November 2022 was $540,000, a 3.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} 12 months-over-yr lessen.

These value decreases mirror a industry rate correction – a interval of time in which property prices fall to mirror where price ranges would be had there not been a interval of rapidly paced growth.

“The markets most at danger of larger sized declines are the exact same marketplaces which observed the most quick spikes in charges,” Gonzalez says. “In places exactly where home rates jumped 30{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in a single calendar year, there is a whole lot of area for them to come back down.”

With several contributing variables, there is no guaranteeing what will materialize upcoming in the authentic estate market place. Prices may go on to develop at a slowing level, they may plateau for a period of time of time or they could decrease.

The point that quite a few homeowners have opted not to provide at this time – in quite a few scenarios to stay away from taking on a better property finance loan fascination level for the upcoming house they would invest in – is one particular of a handful of things that feel to be keeping modifications to house values comparatively sluggish-paced.

“The deficiency of stress on house owners to market will avoid prices from dropping as significantly as they did through the Fantastic Economic downturn,” Gonzalez states. “Distressed gross sales are even now at historically minimal stages and so far, unemployment stays minimal as effectively.”

Even if costs drop a lot more, householders can fret a lot less about getting underwater on their homes. “Home equity across the region stays significant, meaning several home owners are close to negative equity,” Gonzalez claims. “We are not in an environment exactly where hearth profits of properties feel most likely.”

The normal home-owner fairness – the part of a home’s price that the house owner has over and above any home loans or other liens – noticed a internet gain of 15.8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} 12 months-about-yr in the third quarter of 2022, according to CoreLogic’s Home-owner Fairness Insights report. That helps make a homeowner’s regular fairness attain a lot more than $34,000 in excess of a a person-12 months period of time.

This higher sum of fairness provides some cushion for owners, lowering the chance of short sales, foreclosures and other distressed profits that have been all too prevalent in the Wonderful Economic downturn. That cushion can supply householders time in the function that they won’t be able to make month to month mortgage loan payments. Thankfully, that’s not the scenario for most house owners ideal now.

Mortgage rates drop by largest amount in 41 years

Mortgage rates drop by largest amount in 41 years

Mortgage charges plunged by just about a half-p.c this week, marking the most significant week-over-7 days decrease since November 1981.

The level on the regular 30-year set mortgage fell to 6.61{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from 7.08{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} the 7 days prior, in accordance to Freddie Mac, which this 7 days changed its methodology calculating costs. The drop follows a sharp decrease in the generate on the 10-12 months Treasury very last 7 days just after a govt showed inflation cooled very last thirty day period.

The unexpected lessen gave cost-strained homebuyers and sellers nonetheless in the marketplace an inkling of aid, boosting exercise in the otherwise sluggish sector.

“The drop in premiums incentivized purchasers to rush and try to lock rates this weekend, the big difference in need was major,” Adriana Perezchica, president of Via Serious Estate, explained to Yahoo Income. “Until just lately, customer demand experienced weakened as borrowers have experienced a tricky time maintaining up with larger charges and dwelling costs. We really do not know how prolonged this dip in prices will last…and customers are certainly racing to lock a charge.”

This week’s benefits also debuts Freddie Mac’s revised methodology, which now collects real-time fees primarily based on personal loan applications submitted to its automatic underwriting method. The new technique has an ordinary variance of significantly less than 10 foundation factors.

Consumers hurry to protected decreased fees

Purchasers built strategic moves as charges fell. Demand for mortgages spiked very last week with the volume of obtain apps raising 4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, according to the Mortgage Bankers Association’s most recent study of programs.

Whilst Freddie Mac noted that the normal 30-calendar year mortgage loan experienced topped 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} last Thursday, that exact day the govt launched new inflation knowledge, which arrived in weaker than anticipated. That prompted the produce on the 10-year Treasury — which fixed property finance loan costs are inclined to monitor — to plunge by a lot more than 32 foundation factors to 3.816{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, beneath its current regular of 4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.

The 10-yr Treasury bonds fell even decreased this week, dropping to 3.716{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} Wednesday.

“Mortgage charges moved extremely much in line with last week’s 10-yr Treasury collapse. In truth, it was the solitary biggest everyday reduction in mortgage loan premiums that I can keep in mind in in excess of 20 years,” Jeffrey Ruben, president at WSFS Home finance loan, explained to Yahoo Funds previous week. “The 30-calendar year set fee home loan went from just above 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} down to 6.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in a one day.”

Open house on a home for sale in Sherman Oaks. According to the Mortgage Bankers Association, homebuyer activity spiked during the week ending November 11, as prospective buyers took advantage of declining rates.  (Credit: Lawrence K. Ho, Los Angeles Times via Getty Images)

Open up property on a dwelling for sale in Sherman Oaks. According to the Home loan Bankers Association, homebuyer action spiked during the 7 days ending November 11, as prospective potential buyers took gain of declining prices. (Credit history: Lawrence K. Ho, Los Angeles Periods via Getty Photos)

According to Perezchica, the dip in costs boosted one of her client’s getting electrical power – upping the borrower’s pre-permitted home loan spending budget from $430,000 to $490,000.

“My client’s house loan fee dropped from 8.2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 6.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 1 working day. That is substantial,” Perezchica reported. “It implies that the identical consumer will be equipped to afford to pay for a dwelling in an place closer to the city and won’t have to settle for a property that is possibly further away or smaller.”

However, increased residence rates and ongoing inflation pressures continue to keep fueling housing affordability considerations, especially as historically small premiums continue to be new in buyers’ minds. The volume of obtain applications, for example, is however down 46{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from a year ago when rates were at 3.10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.

“Buyers may well wait to shift forward with transactions if they discover the erratic nature of present-day home finance loan costs disconcerting,” George Ratiu, supervisor of financial analysis at Realtor.com, explained in a news assertion. “Some purchasers might want to wait and see if charges will drop even lessen. Nonetheless, with inflation still north of 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, the mortgage market place is not out of the woods.”

Realtor Steve Bremis puts out an

Real estate agent Steve Bremis puts out an “Open House” indication for a few condominiums for sale in Somerville, Massachusetts. (Credit score: Brian Snyder, REUTERS)

Home sellers stay careful

The slump in demand from customers is disappointing for sellers. The share of respondents in a Fannie Mae survey who said it’s a excellent time to promote lessened from 59{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in September to 51{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in Oct.

Residence builders are feeling likewise despondent about the industry, with confidence in the industry falling for the 11th straight month, according to the National Affiliation of Residence Builders.

To motivate purchasers in the marketplace, property sellers are little by little adjusting their price tag expectations.

The share of houses with a price tag reduction was 20.9{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in Oct, up from 10.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} a year in the past, according to Realtor.com. In November, 37{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of builders lower charges this thirty day period, up from 26{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in September, with the typical cost reduction of 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. Builders are also featuring to obtain points and acquire-downs for prospective buyers.

It may perhaps not be plenty of for some price range-constrained buyers.

“Higher fees and elevated residence rates have been difficult on household sales,” Perezchica explained. “Even with this dip in costs, some prospective buyers I’ve talked to have expressed their uncertainty about a potential economic downturn and their potential to pay for a month-to-month mortgage payment in the close to long run. They never know if now is the suitable time to purchase.”

Gabriella is a individual finance reporter at Yahoo Money. Abide by her on Twitter @__gabriellacruz.

Click in this article for the hottest economic news and economic indicators to aid you in your investing conclusions

Study the most up-to-date money and enterprise information from Yahoo Finance

Down load the Yahoo Finance application for Apple or Android

Comply with Yahoo Finance on Twitter, Fb, Instagram, Flipboard, LinkedIn, and YouTube