Investing system Robinhood is having deeper into the news enterprise.
The enterprise, which has prolonged supplied the economical newsletter Treats, mentioned Tuesday (Jan. 17) it had shaped Sherwood Media, a subsidiary that “will be a dwelling for information and information about the markets, economics, enterprise, technologies, and the lifestyle of funds.”
The web page will be led by Joshua Topolsky, founder and previous editor-in-main of The Verge and co-creator of its guardian corporation Vox Media. He is also the previous chief digital content material officer for Bloomberg.
“The story of funds is the story of tradition — from sports activities and enjoyment to the greatest organization and tech news of the day, to geopolitics and over and above,” Topolsky mentioned. “These tales don’t just reside in a terminal they perform out in our life each and every day.”
Sherwood Media plans to start a suite of new editorial offerings all over the calendar year, the release said. In an job interview with Axios on Tuesday, Topolsky mentioned he programs to employ dozens of staffers, including editors, reporters and social media content creators.
He claimed he also programs to start newsletters devoted to particular areas of organization and finances, such as types that include increased-profile corporations like Disney.
Robinhood launched Snacks in 2012. In an earnings phone in 2021, the firm introduced its initial major articles distribution deal with Snapchat, generating Robinhood Snacks available to the thousands and thousands on that social media system.
The headlines dealing with Robinhood of late have commonly concerned collapsed crypto organization FTX, whose founder Sam Bankman-Fried desires Robinhood stock seized by the U.S. returned to him, arguing the shares are his property.
Bankman-Fried’s lawyers reported the shares are not aspect of the FTX bankruptcy scenario, nor is the business that owns them — Emergent Fidelity Technologies, of which Bankman-Fried owns 90{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.
The lawyers explained in a court docket filing earlier this month that when FTX debtors have unsuccessful to clearly show that they would be “irreparably injured” by denial of the claim to the shares, Bankman-Fried demands some of the assets to fund his prison protection.
“Mr. Bankman-Fried has not been located criminally or civilly liable for fraud, and it is incorrect for the FTX Debtors to inquire the Court to only assume that anything Mr. Bankman-Fried ever touched is presumptively fraudulent,” his attorneys claimed in a court submitting.
Robinhood’s CEO has reported he’s not certain what Bankman-Fried will do with his shares, assuming he receives access to them.
“I’m not surprised that it’s one of the far more precious belongings they have on their harmony sheet because it is public company’s inventory,” Vlad Tenev said past thirty day period in a Bloomberg interview.
“We really do not have a good deal of details that you guys really don’t have,” he said. “We’re just seeing this unfold and … it’s heading to be locked up in personal bankruptcy proceedings, most most likely for some time. And so we’re just sort of viewing how that performs out.”
PYMNTS Information: Why Consumers Are Attempting Electronic Wallets
A PYMNTS examine, “New Payments Choices: Why Individuals Are Hoping Digital Wallets” finds that 52{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of US people experimented with out a new payment technique in 2022, with numerous selecting to give digital wallets a try out for the to start with time.
In my defence, I did not get into economic difficulty instantly soon after finishing my master’s diploma in economics. It took months. I experienced a decently paid out graduate career and was living within just my implies, so how did it occur? Uncomplicated: I experienced “cleverly” set all my price savings in a 90-working day see account to maximise the interest I gained. When I was amazed by my 1st tax invoice, I experienced no way of meeting the payment deadline. Oops.
Thankfully, my father was equipped to bridge the hole for me. He experienced no economics teaching, but three decades of further practical experience experienced taught him a simple lesson: things comes about, so it is ideal to hold some completely ready cash in reserve if you can. It wasn’t the first collision concerning official economics and the faculty of lifetime, and it will not be the last.
My eye was caught lately by James Choi’s scholarly posting “Popular Personalized Money Suggestions vs . the Professors”. Choi is a professor of finance at Yale. It’s historically a formidably technological willpower, but immediately after Choi agreed to train an undergraduate course in personalized finance, he dipped into the market of preferred monetary self-assistance publications to see what gurus such as Robert Kiyosaki, Suze Orman and Tony Robbins had to say on the topic.
Immediately after surveying the 50 most well-known personal finance books, Choi observed that what the ivory tower encouraged was typically incredibly distinctive to what tens of hundreds of thousands of viewers had been becoming instructed by the economical gurus. There ended up occasional outbreaks of arrangement: most well-liked finance publications favour low-cost passive index money about actively managed cash, and most economists assume the exact same. But Choi discovered more differences than similarities.
So what are people variations? And who’s suitable, the gurus or the professors?
The remedy depends on the expert, of training course. Some are in the small business of dangerous get-prosperous-swift strategies, or the ability of favourable contemplating, or barely provide any coherent assistance at all. But even the far more useful monetary tips guides depart strikingly from the optimal methods calculated by economists.
Sometimes the common textbooks are basically completely wrong. For case in point, a widespread declare is that the extended you maintain equities, the safer they turn into. Not genuine. Equities give the two extra chance and a lot more reward, whether you hold them for weeks or for many years. (Around a extended time horizon, they are extra most likely to outperform bonds, but they are also far more probably to hit some catastrophe.) However Choi reckons that there is very little damage finished by this mistake, for the reason that it creates sensible expenditure methods even if the logic is muddled.
But there are other discrepancies that should really give the economists some pause. For illustration, the regular financial assistance is that a person should really repay significant-desire debts just before much less expensive debts, of program. But numerous own finance textbooks advise prioritising the smallest money owed initially as a self-assistance everyday living hack: grab individuals small wins, say the gurus, and you are going to start to realise that a route out of credit card debt is attainable.
If you feel that this will make any perception, it implies a blind location in the regular financial tips. People make mistakes: they are subject to temptation, misunderstand pitfalls and expenses, and can’t compute complicated investment rules. Fantastic money information will just take this into account, and ideally protect versus the worst mistakes. (Behavioural economics has loads to say about these types of errors, but has tended to emphasis on policy instead than self-aid.)
There is an additional detail that the regular economic assistance tends to get wrong: it copes improperly with what the veteran economists John Kay and Mervyn King time period “radical uncertainty” — uncertainty not just about what may occur, but the sorts of points that may come about.
For example, the conventional financial assistance is that we really should smooth usage around our everyday living cycle, accumulating debt even though younger, piling up savings in prosperous center age, then shelling out that wealth in retirement. Great, but the plan of a “life cycle” lacks imagination about all the items that could materialize in a life span. Individuals die younger, go by means of high-priced divorces, quit nicely-paid out work opportunities to abide by their passions, inherit tidy sums from wealthy aunts, gain unexpected promotions or put up with from long-term sick well being.
It’s not that these are unimaginable outcomes — I just imagined them — but that lifestyle is so uncertain that the thought of optimally allocating usage above quite a few many years begins to look very weird. The very well-worn financial suggestions of conserving 15 for each cent of your money, no make any difference what, may be inefficient but has a selected robustness to it.
And there is a closing omission from the typical economic see of the entire world: we may only squander money on things that do not matter. Numerous money sages, from the extremely-frugal Economic Independence, Retire Early (Fire) movement to my possess colleague at the Fiscal Occasions, Claer Barrett (her guide What They Really do not Train You About Funds will ideally soon be outselling Kiyosaki), emphasise this very simple notion: we devote mindlessly when we need to expend mindfully. But even though the strategy is crucial, there is no way even to categorical it in the language of economics.
My training as an economist taught me plenty of worth about funds, supplying me justified assurance in some parts and justified humility in other individuals: I am considerably less probable to tumble for get-loaded-fast techniques, and considerably less probably to feel I can outguess the inventory marketplace. Still my training missed a large amount too. James Choi justifies credit for realising that we economists have no monopoly on economical wisdom.
Tim Harford’s new reserve is ‘How to Make the Environment Increase Up’
Follow @FTMag on Twitter to discover out about our latest stories initially
Egyptian monetary organization Speak to wants to endorse sustainability with a new product dubbed “Green Finance.”
In accordance to a Monday (Dec. 26) information release, the merchandise will fund assignments this sort of as solar panels, irrigation programs, and greenhouses, as very well as sustainable farming endeavours.
Green Finance allows buyers fork out in installments – with payment ideas of up to five yrs – with “monthly and quarterly reimbursement programs reflecting Contact’s comprehending of agricultural exercise and its income circulation cycle.”
The release adds that Call hopes to introduce other environmentally friendly goods “to reach modern-day developments that the country seeks, in terms of preserving the surroundings, shielding agricultural locations, reconstructing infertile parts, and converting them into inexperienced spaces which qualified prospects to a much better foreseeable future.”
Speak to is launching this application at a time when provide chain funding is heading green as enterprises around the world do the job towards their sustainability objectives, as PYMNTS wrote past 7 days.
The significantly well-known exercise, known as “sustainable offer chain finance,” involves assessing and delivering financial loans that acquire into account suppliers’ environmental, social and governance (ESG) overall performance.
For substantial companies, it is an more and more vital aspect of their broader ESG initiatives and assists them ensure sustainable sourcing and shrink the carbon footprint of their provide chains.
“But to pull it off, organizations have to have the assist of banking companies. Following all, banking companies provide the funds for most supply chain funding, not buyers themselves,” PYMNTS wrote.
For example, multinational financial institution Typical Chartered not long ago teamed with Middle Jap retail large Majid al Futtaim, which operates the Carrefour model in the MENA region, to reward the retailer’s suppliers that satisfy sustainability standards with far more favorable funding.
By attaching ESG issues to its finance answers, Majid al Futtaim can assistance empower MENA suppliers to spend in far more sustainable systems while accelerating the region’s change to a greener economic system.
That shift is occurring elsewhere as very well. The close of past month’s COP27 climate summit in Egypt saw some big weather tech expenditure offers signed by participating nations.
For case in point, the European Investment Fund (EIF), a personal fairness (PE) and venture funds (VC) financier owned by the EU member states, has pledged investments totaling €247 million, like €75 million qualified at escalating financing for greenfield vitality and round economic system jobs in Spain and giving financing for renewable electricity infrastructure improvement in Europe as a entire.
But even prior to COP27, 2022 was a superior yr for climate tech funding. A the latest report by PwC discovered that local weather tech financial commitment in the 12 months to Q3 2022 represented extra than a quarter of all VC invested throughout the world.
And even with a slowdown in VC investing in the second half of the year, local weather tech has remained resilient, with five of the 10 biggest VC promotions in the most current quarter likely to startups in the room.
How Consumers Fork out On line With Stored Credentials Usefulness drives some shoppers to shop their payment qualifications with retailers, while security concerns give other consumers pause. For “How We Pay Digitally: Stored Credentials Edition,” a collaboration with Amazon Internet Solutions, PYMNTS surveyed 2,102 U.S. shoppers to evaluate consumers’ predicament and reveal how merchants can acquire over holdouts.
See A lot more In: agriculture financing, B2B, B2B Payments, Get in touch with, Egypt, EMEA, ESG, Environmentally friendly Finance, Investments, MENA, News, source chain financing, Sustainability, What is actually Scorching, What’s Warm In B2B
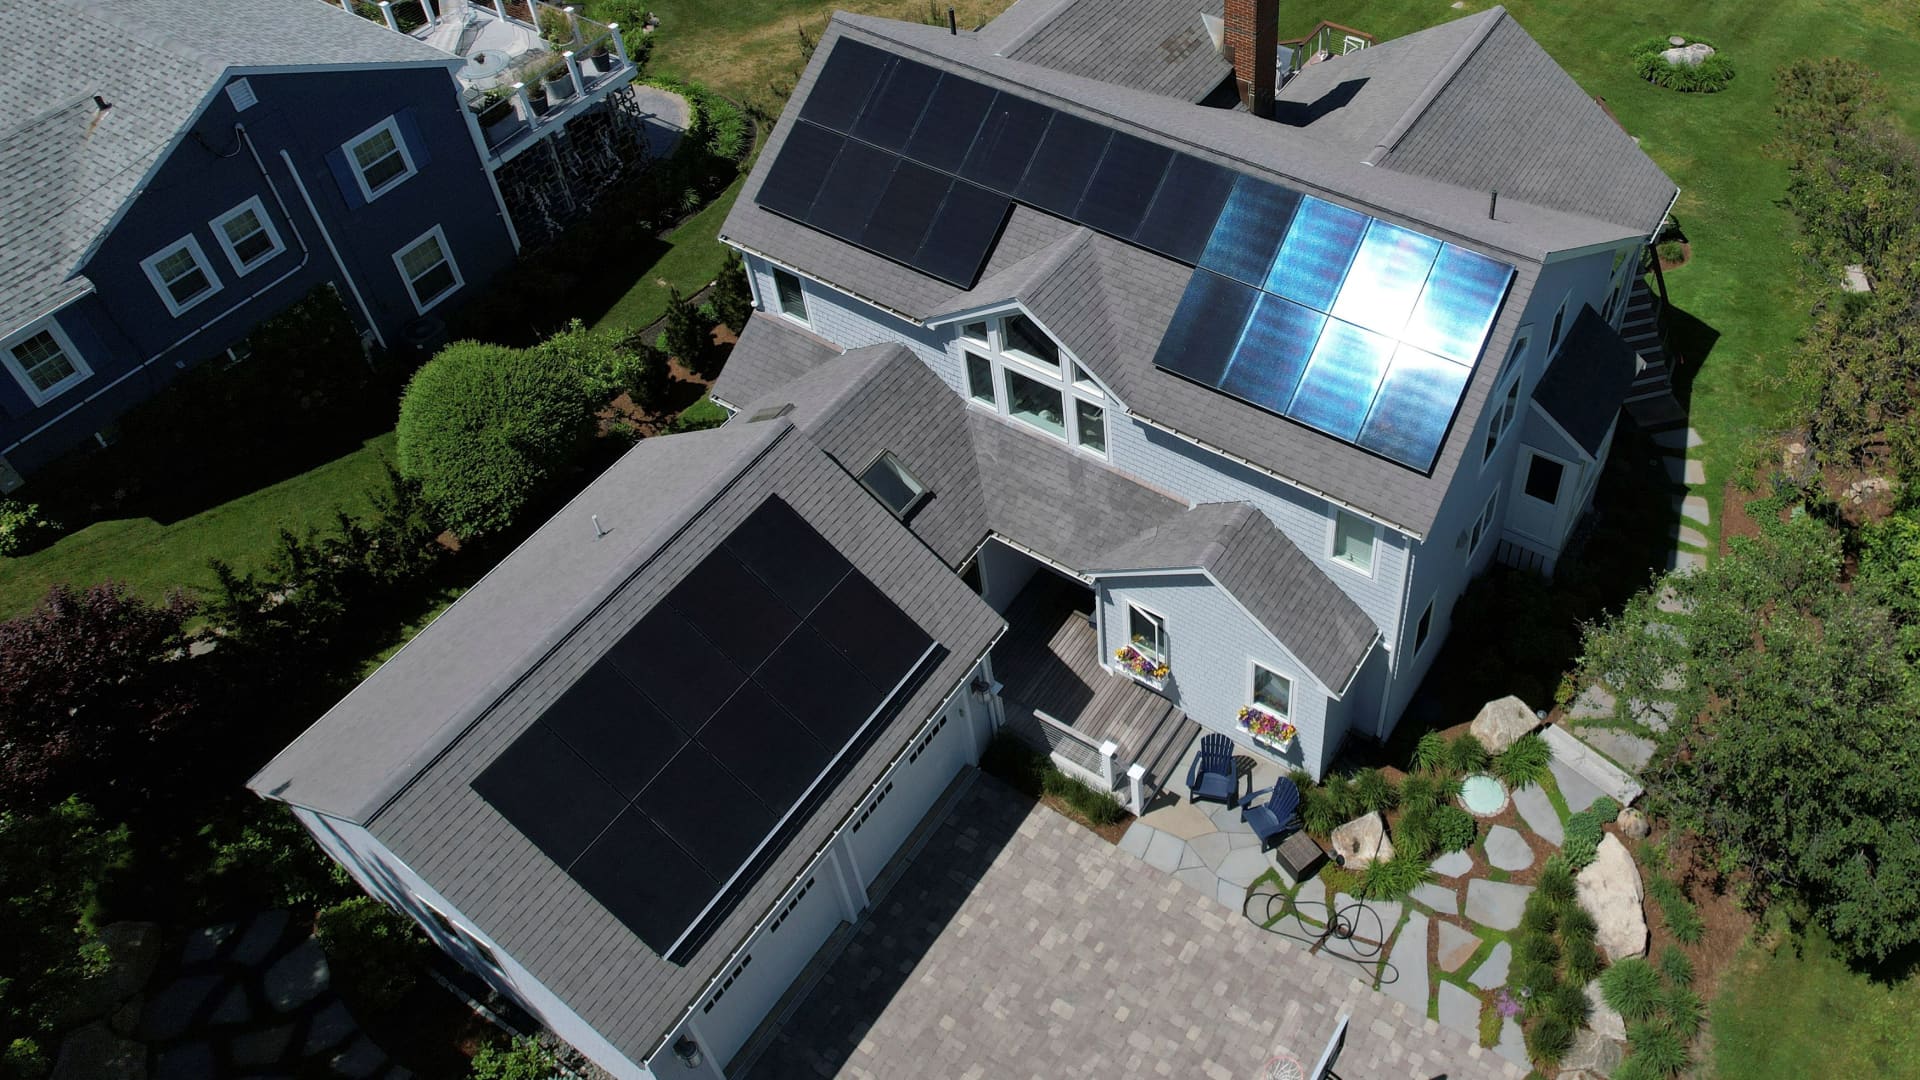
Solar panels create electricity on the roof of a house in Rockport, Massachusetts, U.S., June 6, 2022. Picture taken with a drone.
Brian Snyder | Reuters
When Josh Hurwitz decided to put solar power on his Connecticut house, he had three big reasons: To cut his carbon footprint, to eventually store electricity in a solar-powered battery in case of blackouts, and – crucially – to save money.
Now he’s on track to pay for his system in six years, then save tens of thousands of dollars in the 15 years after that, while giving himself a hedge against utility-rate inflation. It’s working so well, he’s preparing to add a Tesla-made battery to let him store the power he makes. Central to the deal: Tax credits and other benefits from both the state of Connecticut and from Washington, D.C., he says.
“You have to make the money work,” Hurwitz said. “You can have the best of intentions, but if the numbers don’t work it doesn’t make sense to do it.”
Hurwitz’s experience points up one benefit of the Inflation Reduction Act that passed in August: Its extension and expansion of tax credits to promote the spread of home-based solar power systems. Adoption is expected to grow 26 percent faster because of the law, which extends tax credits that had been set to expire by 2024 through 2035, says a report by Wood Mackenzie and the Solar Energy Industry Association.
Those credits will cover 30 percent of the cost of the system – and, for the first time, there’s a 30 percent credit for batteries that can store newly-produced power for use when it’s needed.
“The main thing the law does is give the industry, and consumers, assurance that the tax credits will be there today, tomorrow and for the next 10 years,” said Warren Leon, executive director of the Clean Energy States Alliance, a bipartisan coalition of state government energy agencies. “Rooftop solar is still expensive enough to require some subsidies.”
California’s solar energy net metering decision
Certainty has been the thing that’s hard to come by in solar, where frequent policy changes make the market a “solar coaster,” as one industry executive put it. Just as the expanded federal tax credits were taking effect, California on Dec. 15 slashed another big incentive allowing homeowners to sell excess solar energy generated by their systems back to the grid at attractive rates, scrambling the math anew in the largest U.S. state and its biggest solar-power market — though the changes do not take effect until next April.
Put the state and federal changes together, and Wood Mackenzie thinks the California solar market will actually shrink sharply in 2024, down by as much as 39{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. Before the Inflation Reduction Act incentives were factored in, the consulting firm forecast a 50{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} drop with the California policy shift. Residential solar is coming off a historic quarter, with 1.57 GW installed, a 43{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} increase year over year, and California a little over one-third of the total, according to Wood Mackenzie.
For potential switchers, tax credits can quickly recover part of the up-front cost of going green. Hurwitz took the federal tax credit for his system when he installed it in 2020, and is preparing to add a battery now that it, too, comes with tax credits. Some contractors offer deals where they absorb the upfront cost – and claim the credit – in exchange for agreements to lease back the system.
Combined with savings on power homeowners don’t buy from utilities, the tax credits can make rooftop solar systems pay for themselves within as little as five years – and save $25,000 or more, after recovering the initial investment, within two decades.
“Will this growth have legs? Absolutely,” said Veronica Zhang, portfolio manager of the Van Eck Environmental Sustainability Fund, a green fund not exclusively focused on solar. “With utility rates going up, it’s a good time to move if you were thinking about it in the first place.”
How to calculate installation costs and benefits
Here is how the numbers work.
Nationally, the cost for solar in 2022 ranges from $16,870 to $23,170, after the tax credit, for a 10-kilowatt system, the size for which quotes are sought most often on EnergySage, a Boston-based quote-comparison site for solar panels and batteries. Most households can use a system of six or seven kilowatts, EnergySage spokesman Nick Liberati said. A 10-12 kilowatt battery costs about $13,000 more, he added.
There’s a significant variation in those numbers by region, and by the size and other factors specific to the house, EnergySage CEO Vikram Aggarwal said. In New Jersey, for example, a 7-kilowatt system costs on average $20,510 before the credit and $15,177 after it. In Houston, it’s about $1,000 less. In Chicago, that system is close to $2,000 more than in New Jersey. A more robust 10-kilowatt system costs more than $31,000 before the credit around Chicago, but $26,500 in Tampa, Fla. All of these average prices are as quoted by EnergySage.
The effectiveness of the system may also vary because of things specific to the house, including the placement of trees on or near the property, as we found out when we asked EnergySage’s online bid-solicitation system to look at specific homes.
The bids for one suburban Chicago house ranged as low as $19,096 after the federal credit and as high as $30,676.
Offsetting those costs are electricity savings and state tax breaks that recover the cost of the system in as little as 4.5 years, according to the bids. Contractors claimed that power savings and state incentives could save as much as another $27,625 over 20 years, on top of the capital cost.
Alternatively, consumers can finance the system but still own it themselves – we were quoted interest rates of 2.99 to 8.99 percent. That eliminates consumers’ up-front cost, but cuts into the savings as some of the avoided utility costs go to pay off interest, Aggarwal said.
The key to maximizing savings is to know the specific regulations in your state – and get help understanding often-complex contracts, said Hurwitz, who is a physician.
Energy storage and excess power
Some states have more generous subsidies than others, and more pro-consumer rules mandating that utilities pay higher prices for excess power that home solar systems create during peak production hours, or even extract from homeowners’ batteries.
California had among the most generous rules of all until this week. But state utility regulators agreed to let utilities pay much less for excess power they are required to buy, after power companies argued that the rates were too high, and raised power prices for other customers.
Wood Mackenzie said the details of California’s decision made it look less onerous than the firm had expected. EnergySage says the payback period for California systems without a battery will be 10 years instead of six after the new rules take effect in April. Savings in the years afterward will be about 60 percent less, the company estimates. Systems with a battery, which pay for themselves after 10 years, will be little affected because their owners keep most of their excess power instead of selling it to the utility, according to EnergySage.
“The new [California rules] certainly elongate current payback periods for solar and solar-plus-storage, but not by as much as the previous proposal,” Wood Mackenzie said in the Dec. 16 report. “By 2024, the real impacts of the IRA will begin to come to fruition.”
The more expensive power is from a local utility, the more sense home solar will make. And some contractors will back claims about power savings with agreements to pay part of your utility bill if the systems don’t produce as much energy as promised.
“You have to do your homework before you sign,” Hurwitz said. “But energy costs always go up. That’s another hidden incentive.”
The guarantee was very simple: Comply with them and get rich.
8 influencers, based mostly from California to Florida, promoted on their own on social media as monetary gurus who could decide on winning stocks.
But in reality, federal authorities explained, it was a “pump and dump” plan, in which the perpetrators perform to inflate the charges of shares while pushing them as excellent investments before dumping them for gain.
In parallel cases filed by the U.S. attorney’s office for the Southern District of Texas and the U.S. Securities and Exchange Commission, authorities said the 8 influencers raked in a lot more than $100 million by offering the shares they’d promoted at artificially inflated rates.
With a combined 1.5 million followers on Twitter, the defendants utilised their social media attain to deliver out “false and deceptive information” about the shares they pumped and dumped as component of the scheme, federal prosecutors stated Wednesday.
“In addition to their Twitter presence, the defendants also allegedly ran an on-line local community for personal inventory traders named Atlas Investing, which defendants promoted as just one of the most significant, free on line communities in the world for unique stock traders and which had a chatroom identified as Atlas Buying and selling Discord,” prosecutors explained.
Authorities think that the defendants built at minimum $114 million by the scheme from January 2020 to April 2022.
In accordance to the SEC, 7 of the defendants — together with Beverly Hills people Thomas Cooperman, 34, and Gary Deel, 28 — carried out the plan by coordinating the acquisition of shares, endorsing shares to followers and dumping them for “substantial revenue.”
The SEC also alleged that an eighth defendant co-hosted a stock-buying and selling podcast that promoted the other defendants as skilled traders and “provided a system for other defendants to deceptively encourage the shares they meant to dump.”
On Twitter, Cooperman and Deel billed on their own as multimillionaire day traders and co-founders of the YouTube channel “Goblin Gang.”
“As further alleged in the indictment, the defendants applied their social media reliability to optimize their have profits at the expense of their followers, holding on their own out as proficient inventory traders by putting up shots showcasing their revenue and extravagant existence and encouraging people to adhere to them on social media in get to share in their financial gains,” prosecutors claimed.
All eight defendants have been charged with conspiracy to commit securities fraud.
Edward Constantinescu, aka Constantin, 38, of Montgomery, Texas, also faces three counts of securities fraud and a single depend of participating in financial transactions in property derived from specified illegal action, prosecutors claimed.
Deel and Perry “PJ” Matlock, 38, of the Woodlands, Texas, are each charged with five counts of securities fraud, prosecutors stated. John Rybarczyk, 32, of Spring, Texas, faces four counts of securities fraud.
Cooperman Stefan Hrvatin, 35, of Miami and Mitchell Hennessey, 23, of Hoboken, N.J., had been each and every billed with two counts of securities fraud, authorities claimed.
The defendants made their first courtroom visual appeal Tuesday, prosecutors mentioned. If convicted, they confront greatest sentences of 25 years in federal prison, prosecutors stated.
Constantinescu faces an more most penalty of 10 years in prison if he’s convicted of partaking in illegal monetary transactions, authorities said.