House Republicans are location up a vote next week on laws aimed at maintaining biological males out of girls’ and women’s sports activities at schools, universities and public colleges throughout the country.
The Protection of Women of all ages and Girls in Athletics Act was introduced by Rep. Greg Steube, a Florida Republican who states it can be time to “conserve women’s sports activities” from biological males who have “no position” competing towards ladies.
The vote arrives as the debate more than transgender legal rights and the impact of those people legal rights on American tradition go on to stoke controversy. Just very last 7 days, NCAA champion swimmer and Impartial Women’s Discussion board spokesperson Riley Gaines was assaulted by protesters at San Francisco Point out University as she argued in opposition to transgender female athletes currently being permitted to contend from organic female athletes.
RILEY GAINES BLASTS SF Point out College MEMBER WHO Named PROTESTS AT Coronary heart OF INCIDENT ‘PEACEFUL’
Home Speaker Kevin McCarthy will convey up a vote this thirty day period on laws backed by NCAA champion swimmer Riley Gaines to continue to keep transgender feminine athletes from getting permitted to contend from biological feminine athletes.(Tom Williams/CQ-Roll Contact Inc. by using Getty Illustrations or photos/File | Prosperous von Biberstein/Icon Sportswire through Getty Photographs/File)
Gaines reported she supported Steube’s invoice when he introduced it this 12 months.
“As an athlete who has professional the injustice of competing towards a male firsthand, I’m grateful for the management of Representative Steube,” Gaines wrote. “He has created it obvious that he will struggle for fairness, privateness, and security for ladies and ladies in sports.”
Below Steube’s bill, instructional institutions that obtain Title IX funding from the federal authorities would not be authorized to “permit a person whose intercourse is male to take part in an athletic method or action that is created for females or girls.”
The bill claims that the intercourse of an athlete would be regarded only by their “reproductive biology and genetics at birth.” The legislation would let transgender feminine athletes to coach or observe in a girls’ athletic program, but only if no organic woman athlete is deprived of a roster spot.
RILEY GAINES ‘AMBUSHED AND Physically HIT’ Immediately after Saving WOMEN’S Sporting activities SPEECH AT SAN FRANCISCO Point out
Rep. Greg Steube suggests transgender women have “no put” competing from biological woman athletes, and he desires to have to have all Title IX institutions to ban their participation.(Patrick Semansky/AP Photo/Bloomberg by using Getty Images/File)
Steube said his invoice is wanted to combat again from an invasion of “woke” policies across the nation that go against the spirit of Title IX, which was meant to really encourage women’s sporting activities.
“The insurance policies of the woke, progressive Left have invaded faculties and campuses throughout The united states,” Steube wrote in March. “Making it possible for biological males on women’s athletics groups and in their locker rooms results in an unfair competitive natural environment for feminine athletes.”
“Us citizens should have the chance to see where by their elected associates stand on this exceptionally crucial issue,” he extra. “I appear forward to voting in favor of this laws to help save women’s sporting activities on the House ground very before long.”
ATHLETE RILEY GAINES PROTESTED AT College OF PITTSBURGH: ‘I’M Accomplishing Anything RIGHT’
The laws has now break up Congress as Democrats have built it very clear that most or all of them will oppose the monthly bill on the flooring. The Household Schooling and Workforce Committee authorized the laws in a 25-17 vote – each individual Republican voted for it, and only Democrats voted in opposition to it.
Republicans argued that the Biden administration is harming women’s athletics not just by supporting participation by transgender women of all ages but by trying to find a improve to Title IX that would cement the thought that athletic courses need to permit transgender athletes to participate in the sport that matches their gender id.
Republicans say the Biden administration is destroying women’s sports by allowing for transgender women to contend against biological females.(Anna Moneymaker/Getty Photos/File)
The Dwelling Training and Workforce Committee accepted the invoice together with a report on the evaluate that states tries to allow transgender women of all ages to participate in along with biological girls erodes the objective of Title IX.
“Making it possible for gentlemen to compete in women’s athletic activities undermines the progress created by ladies and women since Title IX’s enactment and makes use of a groundbreaking antidiscrimination statute to discriminate from the really people today it was built to guard,” the report reported.
Click on Below TO GET THE FOX Information App
Property GOP leaders are allowing all customers to propose amendments to the invoice, which must be submitted by this 7 days in order to be deemed.
Pete Kasperowicz is a politics editor at Fox Information Electronic.
In spite of the tumult of the past year, the U.S. economy is closing out 2022 in much the same condition it was in at the end of last year, with inflation running around 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, an ultra-tight labor market and vibrant levels of consumer spending.
But where it’s been over the past 12 months, and where it’s headed in the year ahead, is the result of an unprecedented set of factors precipitated by the impacts of a global pandemic and policymakers’ collective struggles to navigate new problems with old tools and strategies.
Phil Dean, public finance senior research fellow at the University of Utah’s Kem C. Gardner Policy Institute, said inflation issues were foremost on the minds of economists and policy makers in 2022 as the impacts of higher prices hit lower income families the hardest.
“Obviously, record inflation and the policy responses to inflation have been the big economic story of 2022,” Dean said. “On the consumer side, it’s created challenges for everyone, but especially for those at the low end of the earnings spectrum who spend most of their income on necessities, where we saw some of the biggest inflationary increases.”
U.S. inflation in January of 2022 came in at 7.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and climbed steadily until hitting a 40-year high of 9.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in July. Since then, the rate has ticked down with the latest report from the U.S. Labor Department pegging November inflation at 7.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. The U.S. Federal Reserve has pitched a yearlong battle against the elevated prices of goods and services, instituting the most aggressive series of rate hikes in decades in an attempt to cool off the red-hot economy.
Unleaded gas is advertised as $4.79 per gallon as gas prices hit a new record high outside of a Chevron in Salt Lake City on Tuesday, May 10, 2022.
Kristin Murphy, Deseret News
The rate hikes aim to raise the cost of debt for businesses and consumers which should, theoretically, reduce the amount of spending and overall economic activity, a shift in dynamics that typically brings inflation rates down.
But consumer spending has remained robust and the U.S. labor market has continued to run red hot, with unfilled jobs far outnumbering the number of available workers to fill them.
Dean noted high inflation on its own is usually enough to put a damper on rampant spending, but an unprecedented level of cash flowed into the pockets of consumers in the form of pandemic stimulus funding and that, along with other factors, continued to buoy spending throughout 2022, even in the face of record-high prices.
“Inflation and rising interest rates have created some challenges in the current economy,” Dean said. “But alongside that, consumer spending continues to be very strong in Utah and across the U.S. During the pandemic, fiscal stimulus checks flowed to consumers and many took advantage of low interest rates that facilitated refinancing of mortgages that freed up even more money. And, if you look at consumers overall right now, they still have a lot of money to spend.”
Homes in South Jordan are pictured on Monday, Oct. 10, 2022.
Scott G Winterton, Deseret News
The year the Fed went aggro
The nation’s premiere tool to control inflation lies in the hands of the Federal Reserve board of governors and its exclusive control of inter-bank lending rates. In 2022, the Fed made seven consecutive increases to its benchmark lending rate, including a 0.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} hike in December that brought its rate into the 4.25{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}-4.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} range. The December increase followed four 0.75{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} increases that represent the most aggressive series of boosts by the monetary body in decades.
But even the Fed’s top executive has acknowledged the weapons at its disposal to wage war on inflation are underpowered, at best.
Back in May, Fed Chairman Jerome Powell said the 0.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} rate hike levied that month by the board, along with a few subsequent 0.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} upward adjustments, had a “good chance” of cooling down inflation-driven consumer price increases.
“We need to do everything we can to restore stable prices as quickly and effectively as we can,” Powell said in a press conference held in May, per CNBC. “We think we have a good chance to do it without a significant increase in unemployment or a really sharp slowdown.”
But, Powell also acknowledged the Fed’s monetary toolkit is imprecise at best and the hoped-for outcome of stemming inflation is by no means guaranteed.
“We don’t have precision surgical tools. We have essentially interest rates, the balance sheet and forward guidance and they’re … famously blunt tools,” Powell said at the press conference.
“No one thinks this will be easy. No one thinks it’s straightforward. But there’s certainly a plausible path to this,” he added.
Still, inflation continued to shoot up and the Fed was later compelled to go to the jumbo boosts of 0.75{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} for four meetings in a row.
At a press conference following the Fed board’s final meeting of the year in December, Powell signaled that more rate hikes were likely in 2023 even as Labor Department data continues to show U.S. inflation inching down.
“The worst pain would come from a failure to raise rates high enough and from us allowing inflation to become entrenched in the economy, so that the ultimate cost of getting it out of the economy would be very high in terms of employment, meaning very high unemployment for extended periods of time,” Powell said. “I wish there were a completely painless way to restore price stability. There isn’t. And this is the best we can do.”
Jill Reid writes a check for her groceries at Reams Food Store in Sandy on Friday, Sept. 23, 2022.
Jeffrey D. Allred, Deseret News
Here’s how Utahns felt about the economy in 2022
A Deseret News/Hinckley Institute of Politics poll conducted in October found a whopping 93{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of Utahns said they’re concerned about inflation, while only 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} said they’re not concerned.
More specifically, 64{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} said they’re “very concerned,” 29{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} said they’re “somewhat concerned,” 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} said they’re “not very concerned” and only 1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} said they’re “not at all concerned.”
The number of Utahns citing inflation as a top worry had been on the rise since a July 2021 Deseret News poll that found 85{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of Utahns were very or somewhat concerned about inflation. Another poll in February 2022 showed 93{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of survey participants had concerns about the rising costs of goods and services.
October’s reading was only slightly down from a September poll, which found 96{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of Utahns said they were very or somewhat concerned about inflation and 4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} were not very or not at all concerned.
Another September Deseret News/Hinckley Institute of Politics poll got a more specific measure of how inflation was impacting Utah households.
When asked “how much more per month are you paying for basic goods,” 32{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of survey participants said they were spending $201-$400 more per month now, 28{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} said they were spending $101-$200 more, and 22{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} said increased prices were impacting their budgets by more than $400 per month.
While 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} said they weren’t sure how much more they were spending, 12{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} estimated their extra costs for basics at $0-$100 per month.
Utahns saw more inflationary burdens than most of the country in 2022 as rates in the Mountain West, which includes the Beehive State, were at or near the highest in the nation throughout the year.
The latest reflection of that imbalance came in the Labor Department’s November inflation report, released on Dec. 13. While overall U.S. inflation was at 7.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} over the same time in 2021, the Mountain West region saw inflation running at an annual rate of 8.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in November, the highest regional rate in the country.
Produce for sale at Reams Food Store in Sandy on Friday, Sept. 23, 2022.
Jeffrey D. Allred, Deseret News
Is a 2023 recession a sure thing?
Rumors and prognostications about an economic recession have been swirling for months but the same dissonant factors that made the 2022 economy so difficult to predict, and control, will continue into 2023.
“Historically, when you have high inflation, and the Fed is jacking up interest rates to quell inflation, that results in a downturn or recession,” Mark Zandi, chief economist at Moody’s Analytics, told CNBC last week. “That invariably happens — the classic overheating scenario that leads to a recession. We’ve seen this story before. When inflation picks up and the Fed responds by pushing up interest rates, the economy ultimately caves under the weight of higher interest rates.”
Zandi is in the minority of economists who believe the Federal Reserve can avoid a recession by raising rates just long enough to avoid squashing growth. But he said expectations are high that the economy will swoon.
“Usually recessions sneak up on us. CEOs never talk about recessions,” Zandi said. “Now it seems CEOs are falling over themselves to say we’re falling into a recession. … Every person on TV says recession. Every economist says recession. I’ve never seen anything like it.”
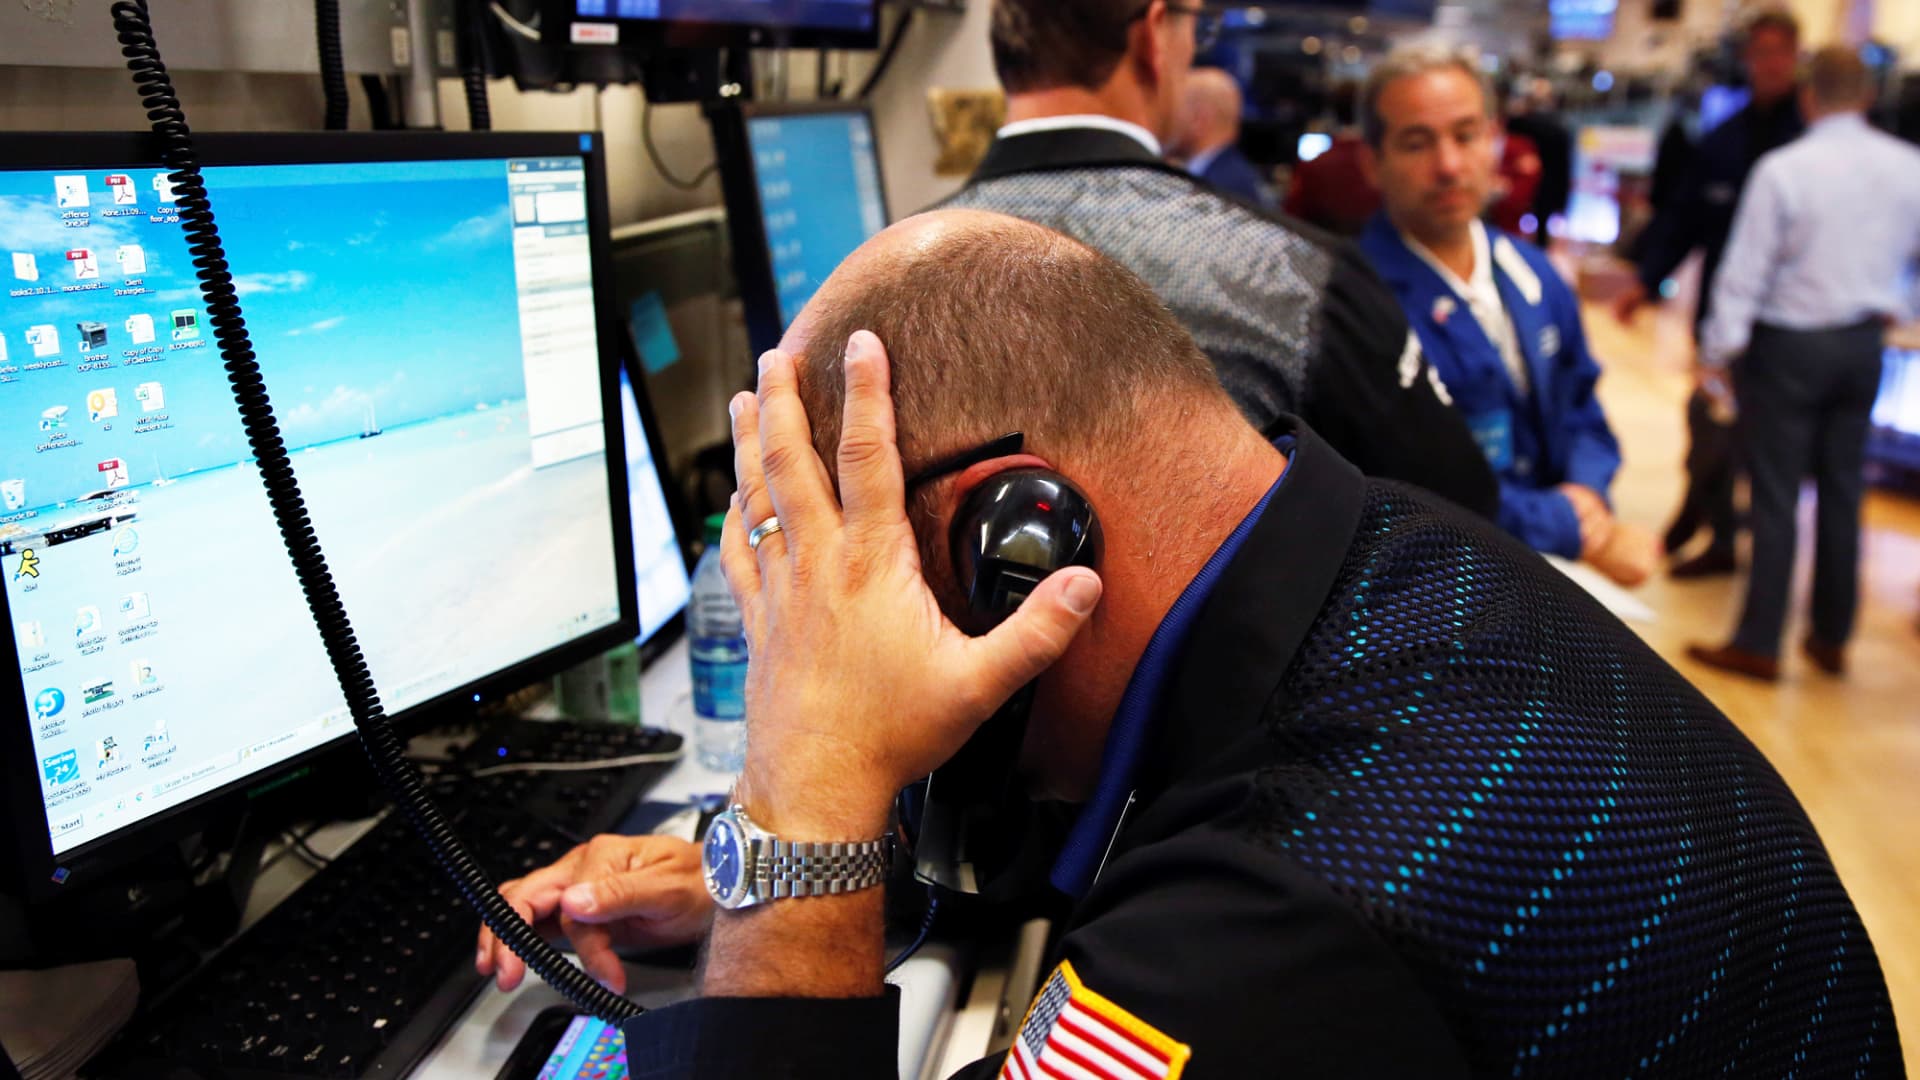
A trader is effective on the flooring of the New York Inventory Trade.
Lucas Jackson | Reuters
Each individual time the inventory current market has rallied off a lower in 2022, it truly is headed appropriate again down once more. Significant hopes among investors that the worst is in have turned into head fakes amid the optimum interest costs in 15 several years. The present-day slump for shares ending the calendar year is just the past instance, and the marketing just isn’t about still.
The latest injury to the Dow Jones Industrial Average will get worse just before it will get greater, and even as the Fed’s battle with inflation is foremost to achievement, it will appear at the cost of a tricky landing for the economy up coming calendar year, in accordance to a new study of main economical officers executed by CNBC.
The final results of the hottest quarterly survey of CFOs are not a shock. Through 2022, conversations with specific CFO Council members have additional often than not tended to the check out that the economic system is headed for a difficult landing. At the current yearly summit in Washington, D.C. on Nov. 30, polling in the space showed that the vast majority of CFOs remained of this check out.
The CNBC CFO Council Q4 2022 study is a sample of the present-day outlook amongst leading financial officers. It was executed between 23 chief fiscal officers at key companies involving Nov. 30 and Dec. 20.
In this article are a number of of the specifics.
Economic downturn is coming
It can be been remarked that no economic downturn has been more predicted than the one that continue to hasn’t strike the overall economy. Involve CFOs in this camp of prognosticators. More than 80{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of respondents to the Q4 survey anticipate a recession in 2023. That percentage has elevated quarter above quarter as a lot more CFOs pushed back before forecasts that the economy now had entered a economic downturn. CFOs are divided on the timing, with equal percentages (43{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}) saying the economic downturn will hit in the 1st 50 {515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} or second fifty percent of the yr.
When a economic downturn hits, the timing is significantly less crucial than the survey finding that a lot less than 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of CFOs believe a tender landing — the idea that the Federal Reserve can cool economic ailments, bring down inflation and deliver up unemployment without the need of sinking the overall economy — is doable.
A lot more Dow providing
CFO views on economic downturn imply extra ache for a inventory marketplace that is ending the yr with a different risky transform down in benefit. More than fifty percent of CFOs (56{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}) polled assume the Dow Jones Industrial Regular to slide back underneath 30,000 again in advance of it at any time reaches 40,000 for the to start with time, and which is near to triple the quantity of CFOs (21{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}) who consider the worst is in for the marketplace or chose not to make a phone on shares in the study.
But the outlook isn’t really all gloomy. In a couple essential areas for the financial state and marketplaces, CFOs do feel the worst is in. For illustration, with inflation.
Inflation has peaked
Whilst it stays the best external possibility factor cited by CFOs — and cited by much more CFOs in Q4 — just about two-thirds of respondents now say inflation has peaked. And CFOs do believe that regardless of the price to the economic system and inventory market place, the Fed is accomplishing a much better career. Extra than fifty percent of CFOs now amount the Fed’s managing of inflation as “great” or “outstanding,” a main enhancement. CFOs who explained the Fed’s endeavours to command inflation as inadequate dropped from approximately 1-quarter of respondents in Q3 to less than 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} who keep this view now.
Political challenges will not tank the industry
One particular cause why inflation was cited by additional CFOs as the major exterior risk factor their corporations deal with: a different possibility went down 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} quarter about quarter, the hazard of about-regulation. The midterm elections and divided government could be liable for this diminished concern.
On other key political threats on the horizon in 2023, CFOs imagine the headlines will be even worse than the reality. A extensive greater part of CFOs (about 80{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}) say a authorities shutdown is unlikely in 2023, and they also assume that it is not likely – a lot more than 50 {515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} say it is “very unlikely” – that Congress would fail to raise the credit card debt ceiling, a watch held by above 90{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of respondents. That mirrors the view made available by Kevin Brady, the outgoing prime Republican on the Household Means and Signifies committee, who advised main economic officers at the current CNBC CFO Council Yearly Summit in Washington, D.C., that it was “financial anxiety-mongering.”
“The bottom line is our debt will be paid out on time. … I never anticipate a 2011 or even 2018,” Brady explained.
Businesses will continue to commit and retain the services of
As the economic predicament and stock marketplace weakened this year, 1 set of findings that has been regular in the CFO study is reasonably stable paying and expenditure programs. This continues to be the case in Q4.
Much less than one particular-quarter of CFOs assume their company’s paying and headcount to be lessened in 2023. Which is not to say businesses are not remaining more careful. An equivalent proportion (around 40{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}) of CFOs say their expending and headcount will continue being the same up coming year as these who assume it to increase.
Nestled inside the $1.7 trillion govt expending monthly bill, which has handed Congress and is headed to President Biden’s desk for a signature, is a suite of significant reforms to the non-public retirement procedure.
The adjustments to come will thrust businesses to get more of their staff members enrolled in savings plans and also give latest retirees a crack. The bill also has provisions that help people saddled with university student loans, military services spouses, section-time personnel who are keen to preserve for retirement.
Several of the variations — totaling $53 billion — start off following 12 months with supporters hoping it will support avert what lots of call a burgeoning retirement personal savings disaster in the U.S., specifically amongst poorer People in america who are too normally still left out of the procedure altogether.
“This is historic,” House Ways and Signifies Chairman Rep. Richard Neal (D-MA) said on Thursday, incorporating that the new guidelines will assist deliver Us citizens with “considerable independence down the highway.”
House Approaches and Implies Committee Chairman Rep. Richard Neal (D-MA). (REUTERS/Evelyn Hockstein)
Neal was one of lots of lawmakers guiding the monthly bill together with figures like Rep. Kevin Brady (R-TX), Sen. Ron Wyden (D-OR), Sen. Mike Crapo (R-ID), and some others. The monthly bill was finalized more than two yrs of discussion throughout a number of congressional committees in what all sides are hailing as a model of bipartisanship.
“As the financial state bargains with the results of the worst inflation in practically 40 decades, doing work people want all the assist they can get when it comes to saving for the next chapter in their life and we are now one particular stage nearer to producing that attainable,” Sen Rob Portman (R-OH) added this 7 days.
Listed here are a few of the key provisions from the bill.
Breaks for latest savers
The invoice is a follow up to 2019’s Safe Act, which represented the initial major retirement laws because 2006.
A single closely viewed provision will modify the age when folks have to start out getting mandatory distributions from their private retirement ideas. The Protected Act elevated the so-called RMDs from age 70 to its latest level of 72. Now, the requirement will rise once more to 73 starting on Jan. 1, 2023 and then up to 75 in 2033.
The new procedures replicate the fact that People are residing longer and rising the age allows them to maintain their revenue tax cost-free for more time and continue to keep earning returns.
The Senate Finance committee – led by Chairman Ron Wyden (D-OR) and rating member Mike Crapo (R-ID) held retirement hearing this summer months to press the legislation forward. (Caroline Brehman/CQ-Roll Phone, Inc by way of Getty Pictures)
Some want Congress to go even further in the many years ahead. Rep. Brady said in 2020, throughout an occasion simulcast on Yahoo Finance, that “my objective is to get rid of it fully.”
The monthly bill also boosts the so-identified as “catch-up” contributions that are allowed for older savers who are at the rear of on discounts and want to place extra dollars absent in their ultimate doing work many years. Those people provisions will kick in in 2024.
Provisions to get additional people today to conserve
A different large swath of the monthly bill consists of a assortment of tries to prod enterprises to get far more people enrolled into retirement programs.
The essential provision, according to numerous lawmakers, is the new rule all around automatic enrollment.
It is the to start with segment of the monthly bill and will mandate organizations to instantly signal up new workers for the employer-sponsored a retirement prepare (if a single is presented) as element of the onboarding approach. The rule would choose impact in 2025 and would use to organizations that supply a 401(k) or 403(b) plan.
New hires could choose out, but the default would be price savings. Reports have revealed that employers with automobile-enrollment retirement programs have much greater fees of participation.
“We’ve determined to start out with computerized enrollment and make it hard to decide out,” Rep. Neal stated. “I feel automated enrollment is a large deal for suitable participants.”
There are also a host of sections in the invoice centered on small corporations, which have a more difficult time supplying retirement options because of their measurement. These companies will access to startup tax credits and new inducements to pool their resources into multi-employer programs in the a long time in advance.
The monthly bill also aims to help aspect-time workers at organizations of all dimensions. These workers typically have to hold out a few decades ahead of they can enroll in a retirement program. The new guidelines lessen the hold out to two a long time starting in 2025.
All explained to, Chris Littlefield, the president of retirement and profits solutions at Principal, estimates that “Safe 2. will aid deliver roughly $40 billion in retirement personal savings for new contributors about the upcoming 10 yrs.”
Novel concepts all over college student loans and crisis discounts
Also in the monthly bill is dealing with scholar loans as deferrals for the intent of retirement personal savings. What that signifies in observe is that scholar loans and retirement cost savings will now correctly be connected if an employer chooses to provide the advantage.
Commencing in 2024, an staff could shell out their pupil bank loan, but in the system receive a “match” from their employer with that income heading into a 401(k) or 403(b) or Simple IRA account.
There is also a comparable plan in the bill all over linking retirement and unexpected emergency savings. Companies could offer you their staff an alternative of placing income into an unexpected emergency fund along with their retirement account. Workforce would be in a position to help save up to $2,500 in an emergency fund — which they can tap anytime — with additional financial savings and probable matches heading towards retirement.
University student bank loan debt holders acquire element in a demonstration outside of the White House in July. (Jemal Countess/Getty Visuals for We, The 45 Million)
A further section of the monthly bill would make it a lot easier for people to entry their existing retirement programs for emergencies without shelling out the onerous tax penalties that frequently appear with withdrawing early. The invoice offers an “exception for selected distributions employed for crisis costs,” in accordance to a summary of the legislation.
“I’ve read from so several folks who experienced to raid cost savings intended for the foreseeable future, not to point out plenty of many others who have never experienced access to an employer-sponsored retirement plan,” Sen. Patty Murray (D-WA), the chair of the Senate’s Help committee, mentioned this 7 days. “That’s why these reforms are so vital.”
As for the huge photo, “there’s some folks that have been remaining on the sidelines of the retirement personal savings recreation,” American Council of Everyday living Insurers Vice President Kathleen Coulombe a short while ago explained to Yahoo Finance Live. She represents a person of quite a few outside groups that aided press the bill over the end line.
“It really seeks to assistance a great deal of these vulnerable populations,” she mentioned.
Other noteworthy areas of the before long-to-be legislation
Other alterations coming before long involve updates to the SAVERS credit to make it additional generous and enhance recognition of the benefit. The credit score permits selected reduced-earnings workers to get more tax breaks when they save for retirement.
Yet another provision aims to make it easier for army spouses who from time to time are not used long adequate to be suitable to help save to speedily be part of a place of work discounts program when they enter or re-enter the workforce. The provision also offers a tax credit rating of up to $500 to assistance these spouses jumpstart their savings.
One more major-line provision would create a national “lost and found” database operate by the Section of Labor for retirement accounts. Sen. Elizabeth Warren (D-MA) pushed this provision alongside Sen. Steve Daines (R-MT), and she claimed this week that the provision will “make it a lot easier for People to hold monitor of their retirement cost savings and for businesses to join their previous staff with the accounts they have still left at the rear of.”
What the invoice won’t handle is the obstacle of Social Protection, which could operate very low on funds as early as 2034. But lawmakers have lengthy been wary of any changes to Social Protection by itself, generally referred to as “the third rail of American politics.”
Ben Werschkul is a Washington correspondent for Yahoo Finance.
Go through the most up-to-date monetary and company information from Yahoo Finance
When it’s very apparent that pressurized housing affordability has triggered some deflation in the U.S. housing current market, sector insiders remain divided on what the ongoing house price correction will appear like in 2023. The explanation? Need and supply are sending blended alerts.
On the housing need entrance, factors keep on being slumped with mortgage order programs (down 38{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} calendar year-around-calendar year) presently just under their lowest point throughout the 2000s housing crash. On one hand, if money circumstances ease and property finance loan premiums slide in 2023, homebuyer desire would enhance. On the other hand, the pandemic’s housing desire boom could’ve experienced a pull-forward outcome that benefits in a slower than anticipated post-pandemic housing sector.
On the housing supply entrance, factors keep on being rather tight nationally. When spiked property finance loan prices corresponded with a huge decrease in demand from customers, it has not prompted sellers to hurry for the exits. In reality, new listings on Real estate agent.com are down 17.25{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} on a 12 months-above-12 months basis. Quite a few prospective buyers who would generally be seeking to move up to a even bigger residence have postponed the swap because they don’t want to give up their fastened 2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} or 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} mortgage loan charges they have for their present residence.
So do prospective buyers (for whom very low demand is a possible tailwind) or sellers (for whom tight offer is a likely tailwind) have the higher hand? 1 of the ideal indications could be the direction of inventory—and its speed of transform. At very first glance, it may well be easy to suppose that stock (i.e. lively listings for sale) is only a measurement of source, nonetheless, it’s also a measurement of demand from customers. If homebuyers pull again, and residences sit on the sector extended, that can raise inventory levels (at present up 46.8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} calendar year-in excess of-calendar year) even if new listings (at present down 17.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} calendar year-over-calendar year) decline.
Let us acquire a nearer look at inventory information in the nation’s 400 largest marketplaces.
Shortly following home finance loan fees spiked this spring, the overheated U.S. housing sector cooled. That swift pullback in customer desire last but not least gave inventory breathing home to rise.
Though nationwide inventory ranges on Real estate agent.com are up 46.8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} 12 months-about-12 months, the photograph may differ noticeably by market. Towns like Austin and Phoenix have observed their respective stock stages soar 160.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and 176{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. Meanwhile, markets like Chicago and New York Metropolis stay effectively unchanged.
Why are stock concentrations spiking in some marketplaces and flat in some others? Nicely, for starters, fundamentals.
Each quarter, Moody’s Analytics assesses no matter if regional fundamentals, together with area profits levels, can support area household charges. If a regional housing industry is “overvalued” by more than 25{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, Moody’s Analytics deems it “noticeably overvalued.” The Pandemic Housing Boom noticed the “substantially overvalued” camp skyrocketed from 3 marketplaces in the next quarter of 2019 to 210 marketplaces by the next quarter of 2022. These frothy marketplaces contain destinations like Boise (“overvalued” by 74{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}) and Austin (“overvalued” by 61{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}).
Speedy-ahead to today, and individuals “substantially overvalued” markets, on combination, are shifting speedier. The inflow of high-earning distant employees saw dwelling rates in boomtowns, like Boise and Idaho Falls, detach from local incomes. Of class, that gets to be a issue when both of those remote employee migration slows and a 1981-degree property finance loan price shock triggers several neighborhood would-be borrowers—who must satisfy lenders’ stringent credit card debt-to-cash flow ratios—to eliminate their mortgage loan eligibility. Cue slipping house selling prices.
In overall, there were 751,544 energetic listings on Realtor.com in November 2022. Which is up from 511,899 listings in November 2021 and 683,606 energetic listings in November 2020. Even so, the amount even now remains far under the pre-pandemic active listing rely of 1.14 million in November 2019.
Some firms, like CoreLogic and Residence.LLC, question that U.S. residence charges will fall in 2023 with inventory becoming this limited. Scientists at Morgan Stanley say those housing bulls should reconsider their stance.
“The point that we count on home price ranges to begin slipping on an annual foundation in March 2023 in spite of tight stock demonstrates how unparalleled this affordability predicament is in the U.S. housing market place,” writes Morgan Stanley researchers who assume U.S. home selling prices to decrease by all around 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from peak-to-trough even even though provide stays below 6 months of inventory.
How can residence prices slide even if stock levels remain beneath pre-pandemic concentrations?
“When desire abruptly falls off a cliff, the absolute stage of supply is not as related. This is where by watching the level of modify on both equally supply and desire independently is significant,” Rick Palacios Jr., director of research at John Burns Genuine Estate Consulting, tells Fortune. “Traders accounted for the highest proportion of purchasers ever this [housing] cycle in a lot of markets. The lion’s share of those prospective buyers are now on the sidelines, with some needing to sell provided overleveraged and actually have been just taking a flyer on dwelling selling price appreciation continuing to rip increased. These days are now around, and these sellers really don’t show [the] identical psychological/behavioral traits involved with traditional proprietor-occupiers, which traditionally keeps house costs fairly sticky on the downside. Builders also account for approximately twice their historical sector share norm when it will come to for sale housing supply in the technique (denominator there is resale source as well as new home offer less than construction and concluded inventory). Builders meet the industry on price whilst conventional house owners usually are not as fast to drop prices.”
“It really is quite probable we see provide increase come spring, which is common. New property supply in specific should really increase, as we know finished properties (completions) are now expanding and builders have a large amount far more unsold properties continue to below building doing the job by way of the program,” Palacios tells Fortune. “This will be the 1st spring offering year considering the fact that 2008 wherever house loan prices are ~6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, so we are expecting a bumpy trip in common for sellers, especially if the economy is formally in a economic downturn.”
When a group like Morgan Stanley or John Burns Actual Estate Consulting suggests U.S. property charges, they’re conversing about a nationwide combination. What ever arrives next will certainly fluctuate by market place.
Between the country’s 400 most significant housing marketplaces, 36 markets are again to pre-pandemic housing levels. The searchable chart (in alphabetical get) higher than displays those 36 markets.
In theory, higher inventory amounts could depress home price ranges in individuals markets.
Among the country’s 400 largest housing marketplaces, 364 marketplaces stay under pre-pandemic inventory amounts. The searchable chart (in alphabetical purchase) higher than displays all those 364 marketplaces.
Even though Morgan Stanley scientists do not feel restricted inventory will protect against dwelling price ranges declines, they do consider tight inventory amounts will prevent a 2008-type crash.
“Whilst source won’t retain dwelling value progress floored at zero, we do believe that it helps prevent property cost declines from turning into way too big” writes Morgan Stanley scientists.
Want to stay updated on the housing downturn? Stick to me on Twitter at @NewsLambert.
Our new weekly Influence Report publication examines how ESG information and traits are shaping the roles and responsibilities of today’s executives. Subscribe below.




/cdn.vox-cdn.com/uploads/chorus_asset/file/24038847/merlin_2934735.jpg "2023 predictions: Is the U.S. economy headed for a recession?")