Homes purchased by all-cash buyers: How is this trend unfolding in the U.S. real estate market?

Homes purchased by all-cash buyers: How is this trend unfolding in the U.S. real estate market?

STATEN ISLAND, N.Y. — At the top of the coronavirus (COVID-19) pandemic, hordes of frenzied dwelling buyers snapped up real estate at an alarming amount, swooping in with astounding all-money provides to secure property in a rather unconventional way.

But according to some new real estate data and modern reporting, sidestepping a property finance loan is no for a longer time an offbeat move: Very last 12 months, virtually a third of U.S. homes were obtained with dollars. Which begs the question — how are such exorbitant purchases attainable?

“Only the wealthy are in essence getting residences,” Lawrence Yun, main economist at National Affiliation of Realtors, a short while ago explained to the Wall Street Journal, responding to knowledge provided by the realty business Redfin, which indicates a unexpected increase in all-income revenue. “If this development was to continue, that implies some thing essentially is mistaken with modern society.”

The pattern isn’t going on similarly throughout the nation, but extra accurately in pockets, the Journal documented. In Washington, D.C., and its fast environment, practically a fifth of properties ordered in 2022 were purchased with funds. Forty miles north, in Frederick, Md., that level practically doubled. A small nearer to residence, in Nassau and Suffolk counties, almost fifty percent of all households procured since 2020 were being acquired in money. Most possible for the reason that hard cash-wealthy town-dwellers dwelling in condos and flats suddenly needed extra.

“What we uncovered was those who presently were being much more perfectly-off were equipped to get gain of the sturdy housing market place and increase to their prosperity, though all those attempting to far better their situation were being normally pushed to the facet,” Ali Wolf, main economist at Zonda, a housing details and consulting business, instructed the Journal.

Retirees, buyers who relocated employing household-fairness proceeds, overseas prospective buyers, traders and high-prosperity people today are the kinds who are major this charge, the actual estate skilled advised the media outlet, employing all-dollars gives as a way of sidestepping climbing interest premiums.

Redfin’s info famous that the share of households acquired with cash is now at concentrations not seen considering the fact that 2014, when the housing current market was on the rebound soon after the foreclosures disaster and the Great Economic downturn. But in which does that depart bidders who want the enable of financial institutions to finance their obtain?

“FHA financial loans, which ordinarily let for decrease down payments, have ticked up in popularity in response to the slowdown in housing-current market opposition,” Redfin pointed out, detailing authorities-backed home loans insured by the Federal Housing Administration.

But even although it’s much easier for customers to now use FHA loans — which demand decreased bare minimum credit score scores and down payments than numerous conventional loans — the website said that affluent all-cash buyers are continue to in a extra fiscally useful circumstance, mainly because they don’t want to take out a bank loan with 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}-furthermore property finance loan curiosity prices.

Which presents superior reason for the all-cash development to continue on.

“All-funds buys are prevalent with today’s affluent prospective buyers, mainly mainly because mortgage loan prices have doubled from a calendar year ago,” Redfin famous. “Buyers who don’t use financial loans steer clear of higher interest payments that exacerbate residence rates, which stay near file highs.”

And simply because U.S. home values have skyrocketed, longtime homeowners are having advantage of the rise and relocating to a lot more cost-effective cities.

“Americans who market a dwelling in a expensive place like San Francisco might use fairness to shell out funds in a more reasonably priced space like Las Vegas,” Redfin concluded.

More Company News

This Staten Island physical fitness coach and her FDNY partner are using kickboxing to new ranges

Staten Island genuine estate company named just one of the nation’s top rated brokerages

Proposed laws would ban design of lithium-ion battery storage web sites on Staten Island

Housing market correction wipes out $2.3 trillion in value

Housing market correction wipes out .3 trillion in value

For 124 consecutive months, spanning the bottom of the housing crash in February 2012 through the prime of the Pandemic Housing Growth in June 2022, U.S. house price ranges posted constructive month-around-thirty day period development. That streak, of class, arrived to an abrupt conclude past calendar year as the Fed’s inflation combat established off a correction in home rates.

On one hand, because their peak, countrywide home price ranges have only fallen by a several share factors via November, according to the seasonally modified Case-Shiller National Home Price tag Index. On the other hand, the ongoing housing correction is previously commencing to have a fiscal, and psychological, impression on homeowners.

On Wednesday, Redfin revealed a report obtaining that the full value of U.S. houses has fallen $2.3 trillion considering the fact that the start out of the dwelling price tag correction.

“The full value of U.S. homes was $45.3 trillion at the finish of 2022, down 4.9{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} ($2.3 trillion) from a history significant of $47.7 trillion in June. That’s the largest June-to-December fall in percentage conditions considering the fact that 2008,” writes Redfin researchers.

Let us be clear: While there’s unquestionably a home value correction rolling through several marketplaces nationwide, most homeowners are even now up huge-time considering that the pandemic’s onset.

“The housing market has lose some of its value, but most home owners will continue to reap huge benefits from the Pandemic Housing Boom,” Redfin researchers stated in the report. “The full price of U.S. houses remains about $13 trillion better than it was in February 2020, the thirty day period ahead of the coronavirus was declared a pandemic.”

Is this dwelling price tag correction just about more than? It is dependent on who you inquire.

Between the 29 significant real estate forecasters, 6 corporations consider national dwelling selling prices will both increase or continue to be flat in 2023. Meanwhile, 23 significant true estate forecasters imagine countrywide house costs will drop additional this year.

Fed officials have acknowledged that they are having to pay close interest to the correction.

On Wednesday, minutes unveiled from the the latest FOMC conference showed that Federal Reserve officials feel “valuations in the two residential and professional property markets remained high” and “that the likely for massive declines in assets price ranges remained greater than normal.”

Every time a group like Redfin says “U.S. residence price ranges,” it means a national combination. On a regional stage, this house selling price correction (or absence thereof) continues to differ.

Among the country’s 400 premier housing markets tracked by Zillow, 276 have noticed local dwelling price ranges slide from their seasonally altered 2022 peak. Yet another 124 marketplaces stay at their 2022 peak price tag.

The marketplaces with the greatest declines, which include areas like Bend, Ore. (down 9.2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}) and Phoenix (down 6.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}), are disproportionately positioned throughout the Pacific Coast and Southwest.

Heading forward, Goldman Sachs expects this West and East divide to go on.

“On a regional foundation, we job more substantial declines throughout the Pacific Coast and Southwest regions—which have noticed the greatest increases in inventory on average—and more modest declines across the Mid-Atlantic and Midwest—which have managed greater affordability around the previous couple many years,” wrote Goldman Sachs in a recent report.

Want to stay up to date on the housing correction? Follow me on Twitter at @NewsLambert.

Master how to navigate and reinforce have confidence in in your company with The Trust Aspect, a weekly newsletter examining what leaders need to have to realize success. Indication up in this article.

Cox Automotive Analysis: Stellantis’ Q4 2022 Market Performance

Cox Automotive Analysis: Stellantis’ Q4 2022 Market Performance

Stellantis has steered skillfully through the global computer chip shortage, maintaining the most abundant vehicle inventory in the U.S. auto industry for the past year while other automakers struggled with skimpy supply. Still, Stellantis posted a decline in U.S. sales in the fourth quarter while also cutting incentives. Its average transaction price rose to over $55,000, thanks mostly to a pair of pricey new Jeeps and strong Dodge pricing increases.

Europe and the U.S. are Stellantis’ most important markets. Here are some data points from Cox Automotive on Stellantis’ U.S. Q4 market performance.

Stellantis’ Q4 Sales Pulled Down by Jeep

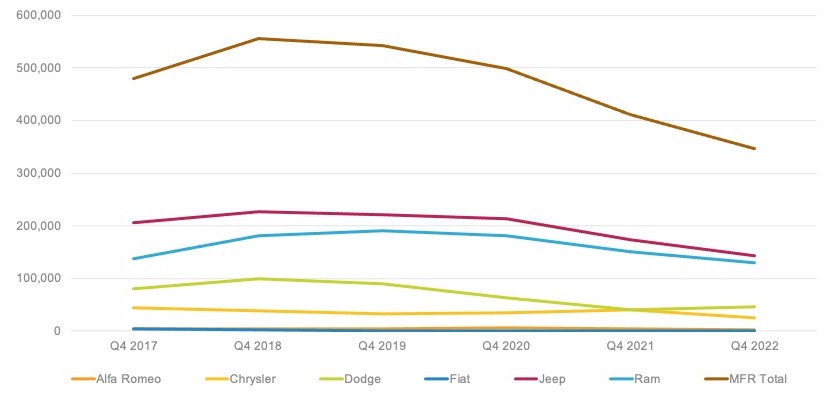
Stellantis Q4 sales totaled 347,649 vehicles, down 15.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from Q4 2021. That compares with a high of 542,519 sales in pre-pandemic Q4 2019.

STELLANTIS U.S. SALES PERFORMANCE FOR Q4 2022

Jeep, Stellantis’ highest-volume brand, saw a significant sales decline of 18{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 143,317 vehicles. That was its lowest sales for the quarter in at least six years. Pre-pandemic, Jeep sold over 200,000 in the quarter.

Almost all Jeep models saw declines except for the Compass and Wagoneer, which saw year-over-year sales increases of 9{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and 12{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, respectively. The biggest drop was the Grand Cherokee at a 32{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} decline or 50,800 units, followed closely by the Renegade with a decline of 27{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. The newer Grand Wagoneer and Wrangler were both down 14{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} year over year in Q4.

Ram sales dropped by 14.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 129,873 units, the lowest sales for the quarter in six years. The volume-leading Ram 1500 pickup truck saw a decline of 22{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 105,255 units. Promaster van sales increased 33{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 18,905.

Dodge sales jumped by 15{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 46,278. All three of the brand’s models gained in the quarter: Charger was up 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 17,414 cars; Durango sales climbed 22{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 15,890 SUVs, and Challenger rose 28{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 12,966 units. The Charger and Challenger are in their final year in their current form, and Dodge is selling special editions to commemorate their final run.

The Chrysler brand, with only two models, had the steepest decline of all major Stellantis brands, with a 39{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} drop to 25,052 units, driven by the 42{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} drop in Pacifica minivan sales. Sales of the 300 sedan, popular with fleets, were up 15{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 2,300 units.

Alfa Romeo sales fell 25{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 3,031 vehicles. Fiat had quarterly sales of a mere 118 units of the 500X, the only model sold in the U.S., down 56{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from a year ago.

With the sales drop, the total Stellantis market share was 9.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, the first time the automaker’s share dropped below 11{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} for the quarter in the past several years. Market share slipped for Stellantis’ highest-volume brands. Jeep share was 4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, down more than a full percentage point from a year ago. Ram dipped one percentage point to 3.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and Chrysler was down 0.5 points to 0.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.

Incentive Spending Slashed to Lowest Level in Six Years

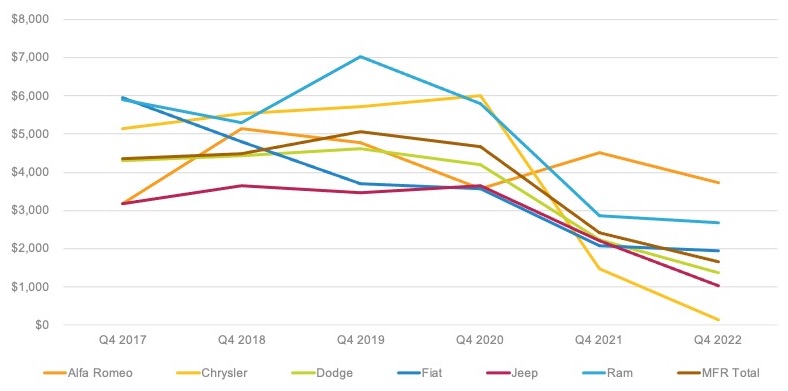
Stellantis slashed incentive spending by 31{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in Q4 2022 compared to the prior year. Its average incentive was $1,658 per vehicle, according to Cox Automotive calculations. That’s the lowest in six years by a wide margin. In the pre-pandemic Q4 2019, Stellantis spent over $5,000 per vehicle on incentives.

STELLANTIS U.S. INCENTIVES FOR Q4 2022

Stellantis significantly cut incentives for all brands. Chrysler incentives were down over 90{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to just $144, marking the first time incentives for the brand were under $1,000 for the quarter. Incentives for Jeep and Ram were down 53{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and 38{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, respectively. Alfa Romeo incentives were down 18{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, and the Ram brand saw the lowest decline with a drop of 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.

Average Transaction Prices Jump to Over $55,000

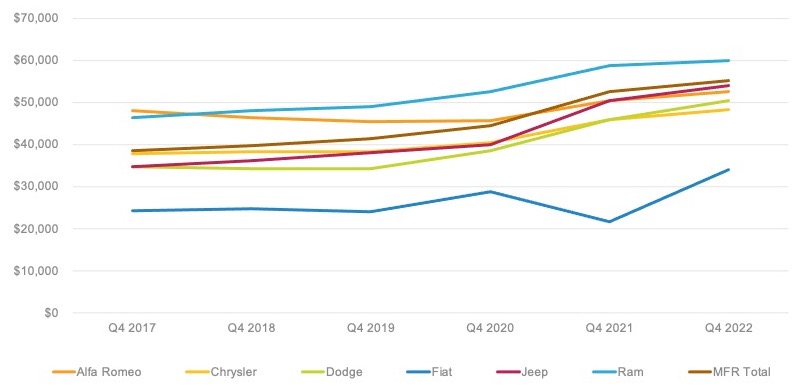
Stellantis’ average transaction price (ATP) jumped 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to $55,281, according to Cox Automotive calculations. By comparison, Stellantis’ ATP was $38,458 in Q4 2017.

STELLANTIS U.S. AVERAGE TRANSACTION PRICES FOR Q4 2022

Ram generates the highest ATPs, up 2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to $59,903. The Ram 1500 got a 4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} boost to $63,363. Promaster gained 16{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to $48,309.

Jeep’s ATP jumped 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to $53,968 on the strength of the new higher-priced Wagoneer, with its ATP of $74,461, and even pricier Grand Wagoneer at $95,152. Grand Cherokee  had a nearly 12{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} gain in ATP to $57,262. ATPs for Wrangler and Gladiator also rose.

All three Dodge models had healthy increases, putting the brand’s ATP at $50,369, up 9.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from a year ago. The Charger had the biggest increase, up 13{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to $47,118. The Durango had the highest ATP for Dodge at $53,431, up 4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.

The Chrysler Pacifica had a 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} increase in its ATP, pushing it to $48,976.


Rebecca Rydzewski is a research manager for economic and industry insights for Cox Automotive.

Housing market hits lockdown low.

Housing market hits lockdown low.

Housing market correction just took a new turn

Housing market correction just took a new turn

“Depending on market place dynamics and backlog concentrations in each and every group, we are acquiring much more aggressive with our pricing forward of the spring selling time, in buy to make new orders,” KB Residence told buyers again in January soon after publishing its disappointing fourth-quarter result.

Rapid-ahead to February, and it seems like we’re by now looking at the housing market correction—which noticed new- and present-property revenue contract at just about history speed in the 2nd 50 {515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of last year—move into a new period. What’s heading on? Aggressive builder value cuts coupled with incentives, like mortgage amount invest in-downs, are supporting builders get profits going up once more.

This uptick in new-residence sales could mean the residence rate correction on the new-development aspect is losing steam. Or at the very least shedding steam for now.

“Builders have taken their medication for the most aspect appropriate now on pricing. And we imagine nationally, dwelling prices—on the new-dwelling aspect, web of incentives—are down about 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from peak,” Rick Palacios Jr., head of investigation at John Burns Authentic Estate Consulting, said in a video clip posted on Saturday. “There’s probably not a ton of runway there still left.”

Let’s be distinct: Palacios is chatting about the residence price correction on the new-home aspect. On the existing or “resale” aspect, he thinks the house selling price correction has a way yet to go.

“We continue to feel that there is a lot more [home] rate correction to come on the resale facet, although. And the resale market place is constantly stickier to the draw back when it will come to [home] rates,” Palacios states.

Contrary to homebuilders, who need to have to reduce selling prices in purchase to transfer unsold inventory, existing home owners are commonly much more resistant to these cuts. That resistance is why present-house charges generally base out very last in a housing industry downturn.

Let us acquire a closer glance at the ongoing correction on the current side. Here’s the info.

For 124 consecutive months, spanning the bottom of the earlier housing bust in February 2012 as a result of the top of the Pandemic Housing Growth in June 2022, the price of U.S. existing one-family members houses, as measured by the seasonally altered Situation-Shiller Nationwide Home Value Index, posted favourable thirty day period-above-month home selling price development.

That streak is around now.

By means of the most up-to-date studying in November 2022, present solitary-family dwelling prices are down 2.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from that June 2022 all-time large. On the a single hand, that drop marks the second-biggest household price correction of the post–World War II era. On the other hand, it can be a gentle correction when compared to the 26{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} peak-to-trough home rate drop concerning 2007 and 2012.

It will be a further six months until finally the Scenario-Shiller reading through for January is released. On the other hand, preliminary knowledge shows that the property price correction on the present-property side may possibly also be losing some steam in 2023.

An evaluation of Zillow House Worth Index information by Fortune (see chart over), finds that 79{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of the nation’s 200 premier housing marketplaces noticed a thirty day period-over-month property value decline in September. That figure has because been dropping, slowly and gradually but definitely.

In October, 76{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of those people key marketplaces saw a home price tag decline. In November and December, it was down to 64{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and 67{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, respectively. Even so, in January, just 47{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of the nation’s 200 largest housing markets registered a thirty day period-in excess of-month dwelling price drop.

Very last year’s mortgage loan level shock, which saw the ordinary 30-yr fastened house loan level spike from 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to over 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, has in truth established off a home price correction. That mentioned, the correction carries on to be bifurcated: Some markets are looking at a sharp correction, even though other marketplaces haven’t viewed substantially of just about anything.

“If you happen to be anyplace in Texas or west of Texas, you’re possibly down extra. If you are any where east of Texas, you might be probably not down that a lot, if at all,” Palacios states.

That bifurcated housing correction is why KB Dwelling, which has a large concentration of organization in rapid-correcting West Coast and Mountain West markets, noticed a cancellation fee that exceeded people of its peers, which do more company in the Midwest and Northeast.

When it arrives to the home price correction, there does stay a single massive wild card: home finance loan rates.

“Before value cuts that now merged with considerable level acquire-downs are serving to on the new-home price stability side [in some markets]. If [mortgage] prices stick close to 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} or break above, further [new and existing] value cuts may perhaps be demanded,” Palacios told Fortune.

Want to continue to be up to date on the housing current market correction? Adhere to me on Twitter at @NewsLambert.

Understand how to navigate and fortify believe in in your organization with The Trust Variable, a weekly publication examining what leaders require to triumph. Indication up here.

Seattle-based Zillow, Redfin post losses after housing market slowdown

Seattle-based Zillow, Redfin post losses after housing market slowdown

Seattle’s genuine estate tech companies are emotion the consequences of the cooling housing market on their bottom lines.

Even with cutbacks and layoffs in 2022, calendar year-conclusion earnings experiences from Zillow and Redfin confirmed considerable losses and declines in gross earnings.

The benefits reflect the chill that strike the housing market previous yr, as interest premiums shot up and kept a lot of potential homebuyers from buying. Nationwide, the number of house profits dropped 18{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from 2021 to 2022, according to the National Association of Realtors.

The market change was “the situation we experienced feared could happen,” Zillow CEO Prosperous Barton advised investors Wednesday. “Thirty-calendar year property finance loan fascination fees practically doubled … meaningfully slowing turnover and dwelling-rate appreciation in the housing marketplace.”

Both Seattle-primarily based companies faced plummeting share charges and economical challenges while attempting to flip properties above the final two yrs.

Zillow, which operates a listing website and sells exposure on its internet site to true estate brokers, reported a web reduction of $101 million in 2022. That was a wide improvement from 2021, when the organization shuttered its home-flipping enterprise, began laying off a quarter of its employees and documented a calendar year-finish reduction of $528 million. 

Redfin, a listing web page and brokerage with brokers on employees, adopted accommodate in late 2022, closing down its household-flipping division and laying off 13{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of its employees. 

Redfin reported a internet reduction of $321 million in 2022, a lot more than double its $110 million decline in 2021. The organization reported a $62 million net decline in the qualities part of its company, which principally included the flipping operation, RedfinNow.

Redfin is even now doing the job to offload 19 remaining houses, CEO Glenn Kelman informed investors Thursday. The business sold a total of 2,044 RedfinNow properties in 2022, according to SEC filings.

Redfin’s complete revenues greater 19{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} calendar year more than 12 months to $2.3 billion. At the same time, its gross earnings declined 29{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.

Zillow observed total revenues drop about 8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from 2021 to 2022. Gross earnings declined 12{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.

In a indication of the sluggish sector past fall, Zillow noted earnings from its home loan organization dropped 65{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in the fourth quarter of 2022, in contrast to the same time in 2021. Earnings from Premier Agent, its promotion small business, declined 20{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in the fourth quarter, even though the organization reported that even now outperformed expectations. 

Both of those companies’ share cost took a strike previous calendar year following peaking in February 2021. And equally laid off personnel in 2022. Zillow’s head rely dropped by virtually 2,300 employees from the conclusion of 2021 to the stop of 2022. Redfin’s dropped by about 900. The cuts leave Zillow and Redfin with just about matching workforces, 5,700 and 5,600 respectively.

Kelman, Redfin’s CEO, explained going through the “near-dying knowledge of trading at $3 or $4 a share” past fall led Redfin to look at a core section of its small business: utilizing serious estate brokers.

Unlike Zillow, Redfin has very long defended its exercise of directly using agents, even with the bigger fees of paying for employees, HR and instruction.

But this calendar year, Redfin will lean much more on husband or wife agents, who function at common brokerages and get referrals from Redfin in exchange for paying Redfin a referral charge when a sale closes. The business plans to increase the share of homebuyers doing the job with non-Redfin brokers from 37{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2022 to 42{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2023. That will enhance gains and restrict future layoffs, Kelman said.

Citing geographic focus as an difficulty, Kelman stated Redfin will also focus on expanding exterior of the West Coast. “When we do hire anyone, it’s likely to be in states like Texas, Georgia and Florida,” he claimed.

Barton explained to buyers Wednesday Zillow is concentrated on creating what they call a “super app” to inspire homebuyers and sellers to use Zillow products and solutions in the course of the procedure of purchasing or advertising a home. 

“After a yr of important folks-linked and other price reductions in 2022, we are now investing during a rough housing sector though many others retrench,” Barton and CFO Allen Parker wrote in a letter to shareholders.

As for the broader housing market, which began to pick up a little bit in January?

“We aren’t out of the woods still,” Barton stated.

The graphic in this story was up to date to correct the profits legend, an previously version misstated it as net earnings.