The housing market correction, as told by 4 charts

The housing market correction, as told by 4 charts

Speaking to consumers in spring 2022, researchers at John Burns Serious Estate Consulting built their circumstance for why the crimson-incredibly hot U.S. housing market place would shortly plunge into a correction in which rates would drop by double digits in numerous overheated marketplaces. The connect with was daring, looking at that at the time Zillow economists were predicting that U.S. household values would skyrocket an additional 17.8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in between February 2022 and February 2023.

It turns out JBREC scientists weren’t just proper, they had been location-on.

Not extended just after the Fed commenced increasing curiosity prices, spiked house loan charges prompted the U.S. housing industry to slip into what Fed Chair Jerome Powell calls a “difficult [housing] correction.” That abrupt slowdown prompted dwelling transaction volumes to crash across the country in the second half of 2022. Furthermore, U.S. dwelling selling prices as calculated by the seasonally adjusted Situation-Shiller National Property Price Index, which prior to 2022 hadn’t fallen on a month to month basis because 2012, declined 2.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} among June and November.

On one particular hand, a 2.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} drop in U.S. property selling prices could look insignificant contemplating U.S. residence rates roared 41{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} through the Pandemic Housing Increase. On the other hand, the reality that researchers at companies like Lender of America and KPMG feel property price declines will go on through 2023 usually means the correction should really unquestionably be viewed.

To get a improved comprehending of what’s going on regionally, Fortune reached out to researchers at John Burns True Estate Consulting. They supplied us with obtain to their proprietary Burns House Benefit Index (BHVI).

Even though nationwide property price ranges deflated a little bit in the next 50 {515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of 2022, the tale varies significantly by industry. You could even call it a bifurcated house price correction: Some regional markets have fallen sharply, although other individuals have scarcely moved.

Among the the 150 significant housing marketplaces tracked by Burns Residence Price Index, 100 markets finished 2022 with local dwelling price ranges down below their 2022 peak. In the meantime 50 marketplaces, together with spots like Milwaukee and Miami, ended 2022 with area property selling prices remaining at all-time highs.

Amongst the down markets, 24 regional housing markets ended 2022 with home costs down at minimum 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from their respective 2022 peak price tag.

The large bulk of the marketplaces with sharp cost drops, like areas like Seattle (-8.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}) and Santa Cruz (-8.2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}), are on the West Coast. One particular explanation is affordability: Quite a few West Coast housing markets ended up now strained affordability-wise, and spiked property finance loan charges only pushed those people marketplaces above the edge.

There is a further explanation: A higher share of homes in overheated West Coastline housing marketplaces are owned by iBuyers and homebuilders. Not like most important owners, investors and builders are extra most likely to slash rates if income prevent.

The best illustration of the bifurcated housing correction could possibly be the distinction amongst Chicago and San Francisco.

For the duration of the Pandemic Housing Boom, Chicago and San Francisco had equivalent paths. The two marketplaces observed a surge of outmigration as distant perform took keep. Both equally markets also even now had a massive operate-up in residence selling prices as demand for “room” soared in the course of the lockdowns.

Nonetheless, the trajectory of property costs in Chicago (down .1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}) and San Francisco (down 10.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}) diverged just as mortgage charges crossed 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2022. It all boils down to affordability: Homebuyers in San Francisco ended up previously in the vicinity of their economic restrictions, though Chicago purchasers continue to had a little much more breathing area to absorb the level shock.

The sharp house price tag corrections aren’t just happening in superior-expense West Coast markets. They’re also happening in “bubbly” housing marketplaces, including places like Austin (-9.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from its 2022 peak), Boise (-8.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}), Las Vegas (-8.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}), and Phoenix (-8.9{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}).

All through the pandemic boom, household prices in these so-referred to as Zoomtowns soared far outside of what fundamental fundamentals (i.e. local incomes) would traditionally support. At the time distant migration slowed and mortgage loan fees spiked, individuals “bubbly” or “frothy” boomtowns slipped into sharp corrections.

Exactly where does the home price tag correction go future? When true estate scientists continue being divided, they do agree that the trajectory of home loan premiums in excess of the coming yr is the greatest uncertainty. If house loan rates remain elevated, it only will increase the odds that national house prices will drop even further.

“Household costs are ordinarily the final indicator to find a flooring in a housing downturn, and we nonetheless think there’s a great amount of money of time forward of us right until that transpires as extended as [mortgage] charges keep 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}-as well as,” Rick Palacios Jr, director of analysis at John Burns Real Estate Consulting, tells Fortune. The new-home facet, he states, will proceed acquiring hit the toughest. “The price tag cuts considering that the 2022 peak for homebuilders are generally substantially more significant than resale, specially if you take into account the expenditures incurred by builders spending to acquire down the charge for homebuyers.”

Hunting for extra housing details? Adhere to me on Twitter at @NewsLambert.

Study how to navigate and improve have confidence in in your enterprise with The Belief Component, a weekly e-newsletter examining what leaders need to triumph. Sign up here.

Americans prefer to cling to cash after shaken by stock market volatility

Americans prefer to cling to cash after shaken by stock market volatility

Last year’s stock market volatility rattled Americans so much that almost 2 in 3 prefer to have their money sit in cash on the sidelines rather than endure market swings.

That is the latest finding from Allianz Life, which asked this question for the first time in a recent survey of 1,005 adults over 18 in December.

And data released in January by the Department of Commerce shows that Americans are again starting to sock away more cash. The savings rate for December was 3.4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} — the highest level in seven months and the biggest month-over-month jump since July 2021.

While cash savings look more attractive now given the higher yields on safer investments, some experts worry that if Americans pull money from the stock market to try to avoid losses, they may end up missing the returns on the way back up.

“If you are keeping money in cash in an attempt to time the market, don’t,” Kelly LaVigne, Allianz’s vice president of consumer insights, told Yahoo Finance. “Trying to time the market will be a failure. What we know is that as the market improves, the bulk of those gains will be made in just a few days. So, if you miss those big days, you’re going to be behind.”

Man in his work office worried about the decline in the value of his business

(Getty Creative)

‘Comfort with investing’ declined

The reality is that investing in the stock market is worrisome for many Americans right now.

“We don’t have a comparison of the number of people who are sitting on cash rather than investing back to 2020 and 2021, but one point we can look at is comfort with investing,” LaVigne said.

Just 19{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of Americans say they are comfortable with current market conditions and ready to invest now, according to the report. That’s down from 26{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in the third quarter of 2022 and 29{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} at this time last year.

And more than three-quarters of Americans think the market will continue to be very volatile in 2023. In fact, if markets continue to be shaky in 2023, 65{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} say they will have to adjust their retirement and investment plans, up from 57{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} at this time last year.

“The volatility in today’s market is scary, especially for people who are approaching or in retirement,” LaVigne said. “But money kept in cash isn’t helping your long-term finances. Cash in an everyday checking account isn’t growing, so with today’s inflation, you’re losing money.”

Whispers of a looming recession coupled with still-high inflation also aren’t helping Americans feel the need to take more risk when investing.

More than three-quarters of Americans are more concerned about paying bills right now than saving for their financial future, according to the report’s findings. As a result, the majority of Americans (55{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}) say they have either stopped or reduced their retirement savings due to rising inflation last year and nearly half (45{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}) say they have had to dip into their retirement savings to pay bills.

Staying out of the stock market can backfire

NEW YORK, NEW YORK - JANUARY 19: Traders work on the floor of the New York Stock Exchange during morning trading on January 19, 2023 in New York City. The stock market opened lower continuing yesterday's slide that saw the Dow Jones closing below 600 points and the S& P having it's worst day in more than a month after disappointing December retail sales and concerns over the debt ceiling and looming recession fears.   (Photo by Michael M. Santiago/Getty Images)

Traders work on the floor of the New York Stock Exchange during morning trading on January 19, 2023 in New York City. (Photo by Michael M. Santiago/Getty Images)

But skipping the market now could also mean that these Americans could miss the upside when the pendulum swings back, which happened after the Great Recession when investors fled the market quickly and re-entered belatedly.

The market’s worst days tend to be followed by its best days. Since 1980, after each instance of big market declines, the market never failed to recover and make new highs, according to research from J.P. Morgan Asset Management.

In the past 20 years alone, the S&P 500 annualized 9.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, but missing just 10 of the market’s best days, which tend to occur within less than one month of the 10 worst days, would have reduced that annualized return to 5.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, according to the research.

Already, the S&P 500 is up more than 8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} year to date, following a 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} gain in the final three months of 2022. That was, of course, after the index tanked almost 25{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in the three preceding quarters.

“We’re definitely seeing some market jitters right now,” Rachel Elson, a financial advisor at Perigon Wealth in San Francisco, told Yahoo Finance.

“We don’t see a lot of folks who bailed out of the markets, although there’s plenty of data to show that people tend to sell at the exact wrong time. We do, however, have some new clients who’ve been stockpiling cash and are nervous about investing; last year reinforced all their worries about the markets.”

Taking a pragmatic approach

One way to slowly move your cash back into the market is dollar-cost-average over a three- to six-month period, Elson said.

“The best way to keep your brain from sabotaging yourself is to make a plan in advance,” she said.

If you have, say, $100,000 in cash, you could invest it in four chunks of $25,000 on a specific day each month. And it’s crucial to diversify your stock portfolio over a range of sectors, such as international, U.S. equity, big and small cap stocks. That spreads your risk.

“Then stick to the plan,” Elson said. “Don’t psych yourself out about buying on an up day or a down day.”

That also doesn’t mean you can’t put some of your cash into safer investments.

(Getty Creative)

(Getty Creative)

“Many market observers expect there could be further pain ahead in the stock market, especially if corporate earnings start to disappoint in the face of a recession,” Michael Wagner, a certified financial planner and co-founder of Omnia Family Wealth, said in an interview. “Allocating a portion of your portfolio to a three-month T-bill paying 4.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} effectively allows you to kick the can down the road while getting paid to wait and see.”

Finding safer investments with decent returns isn’t too hard right now, thanks to the Federal Reserve’s rate hikes. In addition to the three-year T-bill Wagner cited, a six-month T-bill and one-year T-bill are now yielding around 4.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and nearly 4.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, respectively. And it’s possible to find a one-year certificate of deposit, or CD, offering a 4.25{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} yield.

You can also use some of your cash toward a guaranteed, 100{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} return on your money: Paying off high-interest debt like credit card bills.

“That way,” LaVigne said, “you are still improving your overall financial situation.”

Kerry is a Senior Reporter and Columnist at Yahoo Finance. Follow her on Twitter @kerryhannon.

Click here for the latest economic news and economic indicators to help you in your investing decisions

Read the latest financial and business news from Yahoo Finance

Download the Yahoo Finance app for Apple or Android

Follow Yahoo Finance on Twitter, Facebook, Instagram, Flipboard, LinkedIn, and YouTube

Rivian Automotive (RIVN) Outpaces Stock Market Gains: What You Should Know

Rivian Automotive (RIVN) Outpaces Stock Market Gains: What You Should Know

In the hottest trading session, Rivian Automotive (RIVN) closed at $19.71, marking a +1.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} go from the previous working day. The inventory outpaced the S&P 500’s every day attain of 1.05{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. Elsewhere, the Dow obtained .02{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, though the tech-weighty Nasdaq added 9.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.

Heading into nowadays, shares of the a manufacturer of motor vehicles and passenger autos had attained 11.88{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} above the earlier thirty day period, lagging the Vehicle-Tires-Vans sector’s attain of 17.96{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and outpacing the S&P 500’s achieve of 6.27{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in that time.

Wall Road will be on the lookout for positivity from Rivian Automotive as it methods its next earnings report date. This is envisioned to be February 28, 2023. The organization is expected to report EPS of -$1.88, up 22.63{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from the prior-year quarter. Our most latest consensus estimate is contacting for quarterly income of $710.8 million, up 1216.29{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from the year-ago interval.

Any new improvements to analyst estimates for Rivian Automotive need to also be observed by traders. These revisions generally mirror the latest small-term small business traits, which can change often. As a outcome, we can interpret good estimate revisions as a superior indication for the company’s business outlook.

Our research displays that these estimate adjustments are specifically correlated with in close proximity to-expression stock rates. We made the Zacks Rank to capitalize on this phenomenon. Our method takes these estimate variations into account and delivers a apparent, actionable rating design.

The Zacks Rank technique ranges from #1 (Strong Obtain) to #5 (Potent Offer). It has a amazing, outside the house-audited monitor report of results, with #1 shares delivering an common once-a-year return of +25{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} because 1988. In excess of the previous thirty day period, the Zacks Consensus EPS estimate has moved 1.09{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} reduce. Rivian Automotive is keeping a Zacks Rank of #3 (Keep) ideal now.

The Automotive – Domestic market is portion of the Vehicle-Tires-Vans sector. This group has a Zacks Marketplace Rank of 88, putting it in the major 35{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of all 250+ industries.

The Zacks Industry Rank consists of is outlined in purchase from very best to worst in phrases of the regular Zacks Rank of the particular person firms within just every single of these sectors. Our analysis demonstrates that the major 50{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} rated industries outperform the bottom fifty percent by a issue of 2 to 1.

You can obtain extra info on all of these metrics, and much extra, on Zacks.com.

Want the most up-to-date tips from Zacks Financial investment Exploration? Currently, you can download 7 Very best Stocks for the Next 30 Times. Click to get this cost-free report

Rivian Automotive, Inc. (RIVN) : Cost-free Inventory Evaluation Report

To study this short article on Zacks.com click here.

Zacks Expenditure Research

The housing market wakes from the dead

The housing market wakes from the dead
Illustration of a zombie's hand emerging from a grave, clutching keys.

Illustration: Shoshana Gordon/Axios

The housing market place is demonstrating signals of lifestyle following veering into a useless zone late very last year.

Why it matters: These eco-friendly shoots are a very good indication for the overall economy total, and operate counter to some of the dire predictions produced past tumble when home loan rates were being skyrocketing.

What’s happening: Residence consumers are producing peace with greater home finance loan prices, and sellers are producing peace with the will need to lower costs and make concessions.

  • Whilst dwelling prices will possible keep falling, you can find purpose to consider a restoration in sale action is now underway.

By the quantities: Pending dwelling income had been up 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in December, in accordance to Redfin’s proprietary measure. That was the initially regular monthly boost considering that October 2021. (They are however down 31{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} considering the fact that previous calendar year.)

  • In a report titled, “The Housing Current market Has Started to Recover” Redfin also notes that additional people are using home excursions than during the slide.
  • The market’s at a turning level, Taylor Marr, Redfin’s deputy chief economist explained to Axios.

Zoom out: The change is all about mortgage rates. They went up so rapid, and to these a high amount, it was really hard for buyers to even hold up. When prices started out slipping back a little bit, some of these prospective purchasers perked up.

  • Immediately after peaking at over 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in November and crushing demand for houses, costs then fell at the fastest pace because 2009, as the market started off to really feel the Fed was slowing down its level hikes.
  • The common level on the 30-year home loan is now 6.13{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, for each Freddie Mac knowledge out Thursday. That is the cheapest degree given that mid-September.
  • Some prospective buyers are even able to get premiums that commence with a 5 — “an significant psychological threshold,” Redfin notes.

Concerning the lines: Dwelling consumers and sellers modified their expectations. What the moment appeared large now appears to be like type of a deal.

What they’re stating: When Stefanie McFall, an architect in Atlanta, started seeking for properties with her partner and youngsters in the suburbs previous March, they ended up outbid continuously — many properties sold for $250,000 more than inquiring. By early slide, they stopped looking.

  • This calendar year, with mortgage loan charges turning down, they waded again in. Achievements! They’re closing on a five-bedroom house future thirty day period with a 5.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} mortgage loan — the sellers even lined some closing costs. “That would not have took place final spring,” she said.
  • “We didn’t intellect spending a tiny increased fascination rate mainly because it felt like we experienced a very little more purchasing energy,” McFall stated in a concept. The property is most likely $100,000 fewer than it would’ve been past calendar year, she additional.

  • Eric Morales, a tech employee in Alexandria, Va., just little bit the bullet on a 6.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} property finance loan price when he purchased a a few-bed room home with his wife. The price was “agonizing,” but he reported he place on his “macro hat” and looked at the previous 20 decades, and assumed: “This is just not so terrible.”
  • They had been in a position to negotiate the cost down from about $900,000 to $850,000.

The bottom line: When home loan charges commenced climbing last yr, achieving degrees not witnessed for decades, the problem seemed grim. Observers, even all those who knew this was not heading to be like the ’08 crash, braced for the worst.

  • But the small stock of residences for sale, as properly as a continuing need from individuals for more room to operate remotely, is assisting to prop up sale volumes.

What to look at: The Countrywide Affiliation of Realtors will release its measure of pending dwelling revenue, which is extra commonly applied, later this early morning.

Red-hot Miami housing market expected to defy 2023 cost correction as blue state exodus continues

Red-hot Miami housing market expected to defy 2023 cost correction as blue state exodus continues

Florida’s red-incredibly hot actual estate market place is not expected to interesting anytime shortly as scientists predict Miami household selling prices will defy a 2023 charge correction and carry on to increase. 

U.S. current dwelling profits slowed for the 11th consecutive month in December as increased property finance loan costs, surging inflation and steep dwelling charges sapped shopper demand from the housing market. 

But Miami looks to be the exception to the rule as People in america keep on to abandon blue condition tax guidelines.

“As very long as California and states like Massachusetts move steps like the mansion tax or the millionaire’s tax and continue to travel ultra-substantial web value folks out of their states, I imagine that this year is likely to demonstrate wholesome progress for Miami and South Florida,” actual estate expert Dina Goldentayer explained to “Mornings with Maria” Friday. 

Research Claims Wealthy BLUE Condition IS AMERICA’S MOST Economical, BEATING STATES Countless numbers ARE Going TO

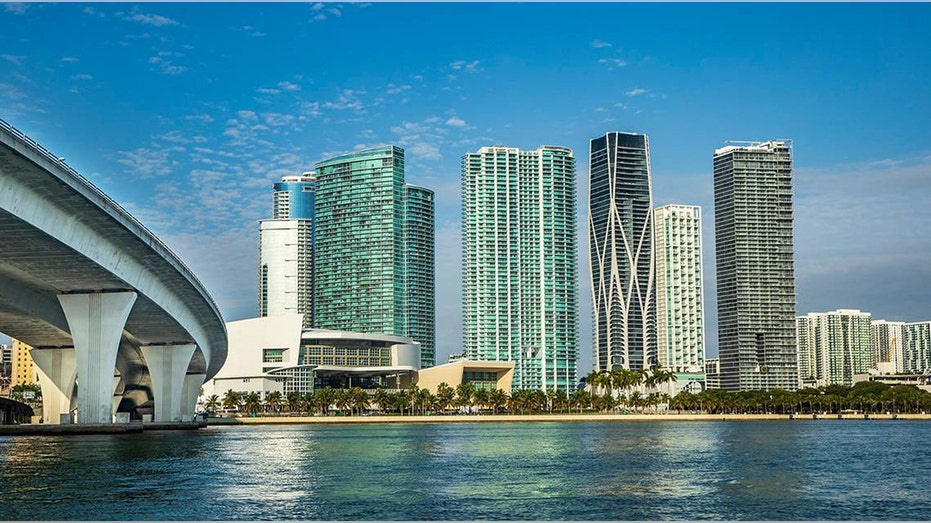
Miami high-rise condo buildings

Solitary-family property and condo rates carry on to climb in South Florida, in spite of a slowdown in sales action. In 2023, housing selling prices in Miami are anticipated to increase, in accordance to a analyze from Goldman Sachs. (Pedro Portal/Miami Herald/Tribune Information Serv (Pedro Portal/Miami Herald/Tribune News Assistance by means of Getty Pictures / Getty Pictures)

Goldentayer, the govt director of revenue at Douglas Elliman, observed an “encouraging” new paper released by Goldman Sachs scientists very last week forecasting Miami will be 1 of only two key housing U.S. markets to escape a staggering countrywide household cost correction in 2023.

In accordance to the U.S. Census Bureau’s Classic 2022 population estimates, Florida is the quickest-growing point out with a 1.9{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} populace enhance involving 2021 and 2022. 

Harsh WARNING ON US Authentic ESTATE Sector ISSUED: ‘AMERICA Demands Much more HOUSING’

But with an unparalleled total of homebuyers flocking to the Sunshine State, realtors are nevertheless grappling with an stock difficulty. 

“Stock is continue to fairly constrained. You know, a 12 months ago, if I experienced a buyer fly in, we may perhaps be ready to see five to eight houses. Now, I could see I could demonstrate that similar purchaser eight to 12 residences. But the inventory is continue to rather restricted,” Goldentayer stated Friday. 

“And there’s considerably from an oversupply in the sectors of the marketplace in which there is much more inventory. In a natural way, you happen to be going to see much more leverage for prospective buyers out there.”

home sales

According to a new paper completed by Goldman Sachs researchers, the Miami metropolitan spot is anticipated to be 1 of the two housing marketplaces to see rate raises in 2023.  (iStock / iStock)

An more issue that is fueling Florida’s housing marketplace is the surge in global purchasers. Goldentayer shared that several global consumers have come from all about the globe to get a piece of the Sunshine Condition – having said that, the “bread and butter” for the Miami marketplace stays purchasers leaving blue states. 

DESANTIS WARNS In excess of CHINA Actual ESTATE INVESTMENTS: ‘GOBBLING UP LAND’ NOT IN FLORIDA’S Very best Interest

“The primary intercontinental buyer for the Miami marketplace remains Canadians. I have a large amount of clientele from Toronto and Montreal. I am unquestionably operating this year with far more European potential buyers,” she ongoing.

“The bread and butter for my market stays potential buyers from blue states like California, like New York. They nevertheless quite considerably fuel the extremely market market.”

GET FOX Business enterprise ON THE GO BY CLICKING Here

FOX Business’ Megan Henney contributed to this report.

Up from here? The free fall in housing market demand just concluded, says Capital Economics

Up from here? The free fall in housing market demand just concluded, says Capital Economics

But there could at last be some good information for builders and brokers: Scientists at Cash Economics consider housing sector activity is bottoming out.

“There are developing indicators that housing industry activity may be near to a trough. The decline in house loan costs around the past pair of months has led to a little enhancement in affordability and a increase in homebuyer sentiment, albeit from a report low. Corroborating this, mortgage loan applications for household buy have ticked greater in the previous couple of months, which ought to feed by means of to increased product sales,” writes Sam Corridor, assets economist at Funds Economics.

It is not just Cash Economics. There is a increasing optimism among brokers and brokers across the place. They’re hoping that loosening economical ailments, which noticed the regular 30-yr fastened mortgage charge drop from 7.37{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 6.09{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} over the earlier two months, will assist to give the looming spring year a minimal juice.

Let us be obvious: Even if housing industry activity (i.e. residence gross sales) has in fact bottomed out, it doesn’t guarantee that household sales will have a swift restoration. Immediately after all, housing affordability remains “pressurized” to a historic diploma. That will happen when U.S. home costs soar 41{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in just over two a long time and mortgage prices spike from 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to over 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in just a 12-thirty day period span.

“But any recovery in housing market place action this year will be tepid. Stretched affordability, a weakening overall economy, and falling residence charges will all weigh on activity. As a end result, we assume 2023 will be the weakest year for gross sales given that 2011 and for starts since 2014,” generate Cash Economics scientists.

Just because U.S. dwelling profits might be nearing a base will not suggest we need to also pencil in the bottom for U.S. property charges.

“Affordability will continue being stretched,” compose Funds Economics scientists. “We believe residence prices will have to have to slide by a further 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} or 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to convey affordability again to a degree that will support additional usual amounts of need.”

Via October, the Circumstance-Shiller Countrywide Residence Cost Index has U.S. house price ranges down 2.4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from the June 2022 peak. In 2023, Funds Economics expects U.S. dwelling rates to fall 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} whilst the ordinary 30-calendar year home loan charge slips to 5.75{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} by yr-stop. Peak to trough, Money Economics expects U.S. dwelling rates to fall among 8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}

Moody’s Analytics chief economist Mark Zandi also thinks U.S. residence product sales are nearing their base though countrywide home charges have further to drop.

“Housing desire [home sales] is near to a trough housing supply [housing starts and completions] has however to hit bottom and [U.S.] residence prices have a way to go in advance of achieving their nadir,” Zandi tells Fortune.

Peak to trough, Zandi expects U.S. household price ranges to fall 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}—with “overvalued” housing marketplaces out West having hit the toughest.

Let us say Capital Economics and Moody’s are proper and countrywide home costs slide 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from peak to trough. If that takes place, household rates as calculated by Circumstance-Shiller would slide again to Oct 2021 stages. On one hand, that would mark the 2nd-most important residence price tag correction of the put up-WWII era. On the other hand, it would be relatively tame in contrast to the 26{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} nationwide house price tag correction observed among the housing bubble’s best in 2007 and the housing crash’s base in 2012.

Seeking for additional housing facts? Stick to me on Twitter at @NewsLambert.

Master how to navigate and fortify trust in your business with The Rely on Element, a weekly newsletter analyzing what leaders want to triumph. Signal up below.