Real-Estate Agents Face a Reckoning As Housing Market, Home Sales Slow

Real-Estate Agents Face a Reckoning As Housing Market, Home Sales Slow

When Chrystina Arnold shut her to start with sale as a true-estate agent in December, she hoped it would supply a springboard to much more specials and the commence of a promising profession. But almost 4 months later on, Arnold is nevertheless seeking to near a next sale.

Arnold, who life in Port Huron, Michigan, paid $89 in October 2021 for a self-paced online study course to become a true-estate agent. But by the time she obtained her license, in June, the regular property finance loan amount experienced approximately doubled, major to a dramatic slowdown in obtaining exercise.

That drop-off has built the earlier calendar year a wrestle, Arnold advised me. The first provider she enlisted to enable her locate clients cheated her out of $600, and that December deal didn’t offer the fiscal windfall she required. Even nevertheless Arnold represented both of those the customer and the seller, the $57,000 sale netted her only a $2,300 commission — barely sufficient to include the numerous service fees she pays to her brokerage, the National Association of Realtors, the organization that sends her leads, and the numerous-listing assistance, a databases where by she can see properties for sale in her area. She’s once in a while labored at a bar or sent pizzas to supplement her fiancé’s profits and aid her 6-12 months-aged son. Even with the setbacks, she’s not offering up hope however.

“I really like my task. I like the overall flexibility of it,” Arnold advised me. “The only matter I never like is the economical insecurity that arrives with it.” 

Although she remains optimistic, Arnold knows the odds are not in her favor — brokers with less than two several years of experience earned a median gross income of just $8,800 in 2021, analysis from the National Association of Realtors located. But overwhelming figures like that didn’t halt a wave of hopeful dealmakers from testing the waters before in the pandemic, when booming home costs promised hefty fee checks. The quantity of Realtors grew by a lot more than 156,000 in the blended many years of 2020 and 2021, according to the NAR, and peaked at a document substantial of 1.6 million in Oct. 

As the pandemic’s homebuying fad now appears like a distant memory, the slowdown in profits has forced a reckoning among the actual-estate agents who need to determine whether or not the shrinking returns are really worth the 1000’s of dollars and plenty of hrs they’re pouring into their organizations. The worries are most pronounced for more recent agents who are still setting up up their networks, deal with fierce competitors from their veteran counterparts, and have not yet weathered a downturn these as this 1.

The spring homebuying period, when income normally choose up and go on increasing through the peak summertime months, will be a crucial exam for agents of all knowledge degrees. A mounting tide is no extended lifting all boats, and the business is bracing to locate out who’s in it for the very long haul.

‘A very low barrier to entry but a significant barrier to success’

Jessica Reinhardt has viewed this ahead of. 

A second-generation Realtor, she’s viewed a lot of folks appear and go from the business enterprise. Reinhardt started functioning at a title business in 1999 in advance of having her genuine-estate license in 2005. She survived the housing market’s 2008 crash, one thing of a badge of honor amid seasoned agents, and is now the president of the Denver Metro Affiliation of Realtors. The organization’s membership rose to a history 9,500 in September, a 20{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} boost from two several years prior, prompting the group to maintain packed orientation sessions for new members 2 times a thirty day period, Reinhardt claimed. Now DMAR is scaling back again the frequency of those people orientations and budgeting for a 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} reduction in membership this calendar year.

“We know there’ll be a minimize,” Reinhardt instructed me. “We went by means of the exact same issue back again in ’06, ’07. There was just an unprecedented quantity of Realtors coming in.”

Just as the housing market place goes by booms and busts, so do the ranks of real-estate agents. Choose the chaotic 2008 cycle: In 2006 on your own, NAR extra practically 100,000 members and achieved a peak of approximately 1.4 million. By early 2012, just after the bubble burst, membership had plummeted to 964,000. And just as the range of Realtors swelled for the duration of the pandemic increase, the ensuing slowdown has now led to a reduce of about 74,000 members in the five months due to the fact the Oct peak. It can be far too early to say no matter whether this is a seasonal dip, which usually occurs in the winter season each and every year, or a indication of a extensive-long lasting reduction. But Lawrence Yun, the main economist for the Nationwide Affiliation of Realtors, acknowledged that these “more durable instances” for brokers could guide to a lesser head depend. 

“The serious estate sector is fiercely competitive with quite a few business owners competing for clientele,” Yun reported in an emailed assertion. “Normally, with much less residence product sales, some will go away the sector.”

Even in advance of property finance loan charges began their climb very last year, the frenzied industry offered its own troubles for agents. A 10 years of underbuilding left very first-time homebuyers scrambling to compete against investors and more mature, wealthier repeat potential buyers, which designed it more durable for brokers to help their clientele get into the households of their desires. Desperate purchasers could make as quite a few as 30 gives and devote innumerable hours elbowing through open up residences right before they last but not least gained out. Reinhardt described it as “chaos.”

“You happen to be seeing purchasers who want to waive inspection and protect appraisal gaps, and every single intuition in you is likely, ‘Oh, my gosh,'” Reinhardt instructed me. “It can be difficult to sit back and observe men and women be that vulnerable.”

However all those were nevertheless growth occasions for agents. In 2021, the common agent experienced 12 transactions, up from 10 in 2020, and their median gross sales volume amplified to $2.6 million, a year-more than-calendar year leap of about 24{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, according to the NAR. Brokers with 16 decades or extra of experience observed their median gross profits rise to $85,000, up from $75,000 in 2020.

That all commenced to adjust in late spring 2022, when the Federal Reserve began elevating fascination premiums to tamp down inflation. That translated to increased home loan premiums, ominous financial forecasts, and a lack of listings, which have spooked both potential buyers and sellers in the calendar year since. Each individual month, Fannie Mae’s Residence Acquire Sentiment Index actions how consumers are feeling about house selling prices, mortgage premiums, their position stability, and, most importantly, irrespective of whether they think it really is a excellent time to purchase or promote a residence. The index, which ranges from to 100, came in at a middling 61.3 in March, in the vicinity of the all-time reduced established in October and down from a COVID-era peak of much more than 80 in summer season 2021. 

“It truly is just a horrible time for potential buyers,” Shantih Moriarty, a veteran authentic-estate agent in Silicon Valley, told me. “Individuals are even now striving to hold on. They’re however striving to claw and scrape their way into a property.”

The gloomy marketplace temper is pushed by a confluence of things that all discourage homebuying exercise. Just as many customers were incentivized in 2020 and 2021 by house loan rates that were being at or in the vicinity of record lows, the surge in charges above the previous 12 months has considerably cooled purchaser fascination. The usual price for a 30-year mortgage loan has surged above 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} — extra than double the ordinary at the exact same place in 2021. For a median-priced residence of $470,000, that big difference would mean roughly $1,000 far more in home finance loan payments each month. And even when a purchaser has ample money in the lender to abdomen the greater premiums, the residences simply just usually are not there. When the number of properties for sale has been on the upswing in the latest months, nationwide stock was nonetheless 43.2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} reduced in March compared with normal degrees from 2017 to 2019, in accordance to Realtor.com. The hesitancy on the element of both customers and sellers contributes to a familiar, self-satisfying cycle — home owners fret they is not going to be in a position to discover a different residence, or are in no rush to give up their favorable property finance loan amount, so they maintain off on listing, which can make the circumstance worse for purchasers.

This has still left true-estate brokers combating around a dwindling pool of listings. In actuality, there have been additional than two times as several Realtors in March as energetic homes listed on the market place — a full of roughly 1.5 million agents compared with just 563,000 homes.

The sluggish marketplace has thrown what was when viewed as a beneficial occupation pivot into question. In Cha, a 46-year-previous previous style designer, bought her authentic-estate license in the tumble following relocating to a suburb of Pittsburgh with her partner and 9-yr-old son. The initially residence she promoted on behalf of an owner bought within just a number of times of listing in November. But now she and the much more experienced agents at her brokerage share a popular trouble: They can not obtain ample properties for their shoppers who are looking to get.  

“There are enough prospective buyers, but you can find not more than enough sellers,” Cha informed me. “It is irritating.”

Only 4 in 10 new true-estate agents are confident they’re going to be capable to have a lengthy-phrase career in the sector, a survey conducted previous yr by Realtor.com observed. The preliminary outlay to come to be an agent may possibly be tiny — generally a couple hundred dollars to take a system and exam — but acquiring shoppers can be particularly tough for individuals who do not have a strong network at the commencing. The time dedication expected to make a living at it can also occur as a surprise. 

“Having into the sector as an agent, there is a reduced barrier to entry but a substantial barrier to success,” Meghan Brown, the director of information and neighborhood for Realtor.com, instructed me.  

A very long-time period investment

Of study course, for every single housing-current market downturn, you can find an upswing on the horizon. Yun, the NAR main economist, argued that the shrinking quantity of Realtors could in the end advantage those people who are capable to dangle on, considering the fact that the thinning ranks will reduce competition as points stabilize.

“In a feeling, Realtors like to see much less Realtors because of to the huge total of industry level of competition,” he told me. 

And not just about every true-estate agent is struggling correct now. Mary Gibler, a 28-calendar year-outdated real-estate agent in Naples, Florida, received her license in Oct 2021 immediately after doing work for various months as a broker’s assistant. She experienced a productive very first six months, closing 9 offers, but took time off to target on her coming child once she could see that charges had been soaring and prospective buyers were being retreating late past spring. She began working once again in January, a normally hectic season in her location. Gibler received off to a slower start off than final 12 months, she stated, but she started to uncover a groove all around mid-February. She at the moment has a few contracts pending and is doing work with two other sellers. 

“It took me a moment to comprehend that residences were not traveling off the industry in the exact way,” Gibler told me. “The consumers I worked with were being a lot more selective and took their time with their selections.”

No two true-estate marketplaces are the exact. But when price ranges have been climbing across the board for the duration of the peak of the pandemic, it started to sense that way. As the market normalizes, it truly is starting to be increasingly tricky to paint the national housing current market in wide strokes — rates are now slipping in some parts though continuing to rise in many others — and these diverging traits are supporting some Realtors in steadier marketplaces discover their footing. A recent Wall Avenue Journal evaluation of details from the home loan-info company Black Knight identified that residence price ranges were however increasing on an once-a-year basis in major markets east of Colorado but slipping in western markets. 

“We are no for a longer time just one market,” Moriarty, the agent in Silicon Valley, explained to me. The earthshaking distortions of the pandemic manufactured the “entire United States, and really, to some extent, the total planet, act really similarly,” she claimed, introducing: “Now we’re damaged up into a good deal of person markets once again in a really profound way, and they are not likely to reply the very same.”

That makes the position of a regional real-estate agent trickier and more nuanced than it was a calendar year back. A very good agent will know the sector like the back of their hand — what a very good present will search like and what it usually takes to win. But those skills by yourself are no promise of good results in the business enterprise. 

“What helps make a thriving agent is any person who appreciates how to marketplace themselves and get referrals,” Moriarty stated. “What helps make a fantastic authentic-estate agent and what tends to make a productive actual-estate agent have nearly no crossover.” 

If you are new to the organization, that information might be encouraging or dismaying, relying on how you glimpse at it. Arnold, the agent in Michigan who has only shut just one offer, explained to me she’d observed it hard to get her name out there and secure purchasers. She joined a women’s guidance group for serious-estate brokers on Facebook, in which she found quite a few others were being encountering equivalent troubles. A great deal like acquiring a residence, she thinks she’s generating an investment decision that will one particular day pay off. 

When I caught up with Arnold in mid-April, a handful of weeks after I initial spoke with her, she had encouraging news: Just one of her customers, whom she satisfied at an open up residence, had just experienced an offer acknowledged on a $274,000 dwelling. Arnold claimed she expected the offer to near in early Could. 

“I am not the type of human being to give up conveniently,” Arnold instructed me. “I form of like the odds against me. It just presents me additional generate to defeat these odds.”


James Rodriguez is a senior reporter for Insider.

Celebrity real estate agent says LA market taking ‘slow’ turn as mansion tax goes into effect

Celebrity real estate agent says LA market taking ‘slow’ turn as mansion tax goes into effect

Immediately after “extraordinary” consumer and vendor frenzies through the thirty day period of March, a person of the greatest names in Los Angeles genuine estate has warned the sector has by now taken a transform for the worst in the early times of L.A.’s “mansion tax.”

“About the very last month, two months, we’ve been looking at a big rush to consider to get men and women to offer. We essentially had an extraordinary March, a ton of high-conclude households bought in March. And correct now, the pipeline heading ahead is really, actually reduced and actually gleam,” The Agency founder and CEO Mauricio Umansky explained on “The Base Line” Tuesday night.

The authentic estate mogul – who stars in his possess Netflix show and has been married to “Genuine Housewives of Beverly Hills” star Kyle Richards for extra than 25 several years – spelled out how the area’s recently-enacted mansion tax has already impacted the sector.

Officially commencing on April 1, the “United to Household L.A.” (ULA) measure in California adopts a so-termed mansion tax on assets gross sales or transfers in excess of a sure price to pay back for economical housing.

STUART VARNEY: CALIFORNIA’S NEW ‘MANSION TAX’ IS JUST One more WAY TO BASH THE Abundant

Homes offered higher than $5 million but underneath $10 million are topic to a 4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} profits or transfer tax, whilst qualities that offered for a lot more than $10 million will experience a 5.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} tax, according to the metropolis clerk’s voter information pamphlet.

Mauricio Umansky on mansion tax

The Agency CEO Mauricio Umansky stated why Los Angeles mansion tax is coming at the completely wrong time for the actual estate market place on “The Bottom Line” Tuesday, April 4, 2023. (Fox News)

At least 92{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of taxpayers’ dollars would “fund very affordable housing underneath the Reasonably priced Housing Plan and tenant aid applications underneath the Homeless Avoidance Plan,” the pamphlet also clarified.

“I will not imagine they are pondering proper now. I feel this arrives at a truly terrible time. It is coming throughout the time exactly where we are already attempting to sluggish down the housing marketplace. The interest premiums are going up a great deal they have gone up by 500 basis points [in] the final 6, seven months,” Umansky discussed.

“And appropriate now, we are all of a unexpected incorporating this mansion tax,” he ongoing, “and this mansion tax is place on prime of a truly slow industry in which all of a unexpected, it would not make a difference regardless of whether you are earning funds, losing funds, you are heading to owe this tax.”

To stay clear of staying subject matter to these taxes, L.A.-spot homebuyers and sellers rushed to near multi-million-greenback deals and offload homes. But now, Umansky claimed much less people are shopping for, offering or even checking out a assets move.

“It truly is really going to gradual down the housing marketplace a large amount more in Los Angeles than it presently is. And it is previously gradual below,” The Agency CEO explained.

For people L.A. inhabitants at the moment offering their households, the broker advised not raising your listing pricing when noting it could be valuable to go “off the market.”

“It really is a truly unusual and tough time that we are having difficulties with. And the dilemma is that we don’t even know if this funds is in fact going to assist the men and women,” Umansky pointed out. “The way that they offered this on the ballot, it was actually, ‘Let’s tax the wealthy and let us go correct the problem with the homeless.’ And now, they are just putting in the council in get to try to determine out what they are going to do with the income, how considerably cash they are likely to have.”

GET FOX Organization ON THE GO BY CLICKING Below

The mogul’s clients are not reportedly way too delighted about the tax, possibly.

“The full general public genuinely voted on a proposition that wasn’t even completely imagined out. It was so badly published. Most individuals do not even know about it,” Umansky said. “When I am conversing to my purchasers about it, they cannot feel where by it came from. They never comprehend it. They never know how it got on the ballot, and it can be a genuine mess.”

Go through Extra FROM FOX Small business

Fed’s Powell says SVB collapse may slow the economy through tighter credit

Fed’s Powell says SVB collapse may slow the economy through tighter credit

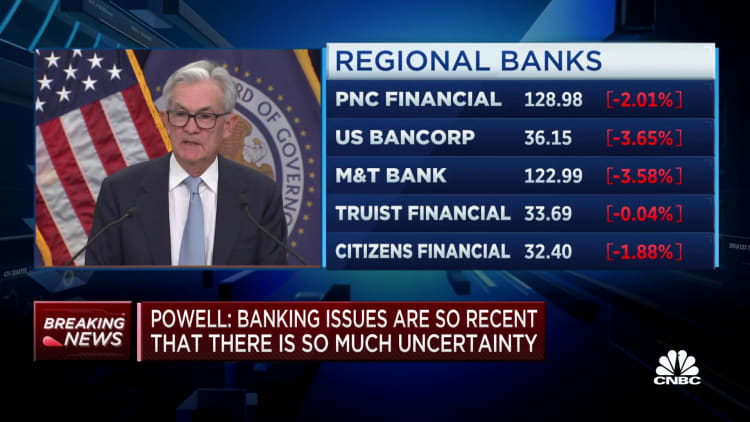
Federal Reserve Board Chair Jerome Powell speaks through a news conference at the Federal Reserve in Washington, DC, on March 22, 2023.

Olivier Douliery | AFP | Getty Pictures

Federal Reserve Chair Jerome Powell reported Wednesday that the U.S. banking sector is powerful but that the current failure of some regional financial institutions could cause ripple effects that gradual down the financial state.

At a press meeting right after the most recent Federal Open Marketplaces Committee meeting, Powell described the banking technique as “audio and resilient” but said the central bank was monitoring a improve in the availability of credit score for customers and organizations.

“Monetary problems appear to have tightened, and possibly by a lot more than the regular indexes say. … The query for us although is how substantial will that be — what will be the extent of it, and what will be the period of it,” Powell explained.

“We are going to be looking to see how serious is this and does it glimpse like it is really likely to be sustained. And if it is, it could conveniently have a significant macroeconomic impact, and we would element that into our plan selections,” he extra.

Our response was how did this happen, says Fed Chair Powell of SVB failure

The Fed hiked its benchmark desire charge by a quarter of a percentage stage on Wednesday, but its projections referred to as for just just one extra hike above the relaxation of the 12 months. The central bank chief mentioned that tighter monetary conditions induced by more stringent lending choices from banking companies could have a very similar effects as further more hikes from the Fed.

Powell’s responses appear after regional financial institutions have appear less than significant tension this thirty day period. Silicon Valley Financial institution collapsed, making it the next premier failure in U.S. heritage, in part simply because the speedy increase in desire costs devalued its bond portfolio and designed significant paper losses for the financial institution.

SVB’s administration “unsuccessful poorly” in handling its desire amount dangers, even though other financial institutions have managed to deal with the hikes, Powell reported.

Other banking institutions like Very first Republic and PacWest have witnessed considerable outflows of deposits. The Fed set up a new Financial institution Phrase Funding Software to aid financial institutions entry funds, but the stocks for regional financial institutions have fallen in volatile buying and selling given that the facility was created on March 12.

Powell explained that deposit flows have stabilized more than the previous 7 days and that Americans really should sense confident that their money is harmless, however he stopped quick of explicitly stating that all deposits are now confirmed.

“What I am stating is you’ve got noticed that we have the applications to shield depositors when there is a risk of serious harm to the economy or to the financial technique, and we’re geared up to use individuals applications. I think depositors ought to assume that their deposits are risk-free,” he mentioned.

The collapse of Silicon Valley Financial institution has led to much more scrutiny on the Federal Reserve’s supervisory part in excess of banking companies, in particular from Sen. Elizabeth Warren (D-MA).

The Fed is conducting an internal critique of possible regulatory concerns all around SVB, led by Vice Chair for Supervision Michael Barr, and Powell mentioned he expects investigations from outdoors the central bank as effectively.

IMF managing director says U.S. economy will slow, but could avoid recession

IMF managing director says U.S. economy will slow, but could avoid recession

International Monetary Fund managing director Kristalina Georgieva says the U.S. economic system will sluggish this year, but a soft landing is doable. 

“The U.S. economic system is also going to slow down this year. But, at the very least based mostly on the details we have right now, we assume U.S. would be ready to go by the yr narrowly averting slipping into recession,” Georgieva informed Lesley Stahl on 60 Minutes. “That implies a possibility for a delicate landing for the United States.”

And what about U.S. work?

“Our expectation in direction of the end of yr is to see somewhat weaker labor markets,” Georgieva reported. “But let’s be pretty very clear, we are not scared of some big unemployment wave swiping by means of the United States.”

Georgieva’s interview arrived as the IMF produced its new report on 2023. Following gloomy predictions of a darkish future, the most recent report has a a bit brighter outlook. 

“The biggest surprise is that the photograph, even though it stays extremely concerning, is significantly less dire than it was just two months back,” Georgieva said. “We are nevertheless heading for a 12 months of slowing growth. We are even now going to have interest charges fairly substantial simply because inflation has not evaporated. So it is not substantially greater. It is just fewer lousy.” 

“The report says we are gonna go down, usually, the world,” Stahl stated. “And then we are gonna relieve up?”

“This is what we are anticipating to see,” Georgieva claimed. “That inflation globally would shrink from 8.8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2022 to somewhat more than 4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2024.”

“So what is your assistance to the U.S. Fed?” Stahl questioned. “Need to they continue on increasing prices?”

“Our tips to the Fed is to remain the system till main inflation begins turning down,” Georgieva reported. “The Fed has to be very very careful not to start easing economical situations prematurely.” 

And that is vital, simply because the Fed, like all other financial institutions, relies on the IMF report.

“What about American politics? I am talking of the financial debt ceiling specifically,” Stahl asked. “Guaranteed you’ve got factored that in. Are you assuming that the United States could go into default due to the fact Congress refuses to lift the debt ceiling?”

“A default of the US would induce major injury to the worldwide overall economy,” Georgieva explained. “But If you glimpse at record, commonly following a ton of back again and forth, a option is staying located. So I set my hope and have confidence in that historical past would be recurring.”

“So your assumption is that the unthinkable will not occur,” Stahl reported.

“COVID has taught us to be far more open minded, that the unthinkable can happen. Even far more-so the war in Ukraine,” Georgieva said. “And this is why it is really significant for all people worried to take this conversation quite seriously. It will be really damaging for U.S. individuals if the U.S. defaults, that would thrust interest premiums up. And if people you should not like inflation nowadays, they are not going to like at all what may possibly materialize tomorrow.”

Global economy going into recession, 2023 growth to slow

Global economy going into recession, 2023 growth to slow

Why the World bank slashed its global growth outlook

The World Bank slashed its global growth forecasts from projections it made in mid-2022 on the back of what it sees as broadly worsening economic conditions.

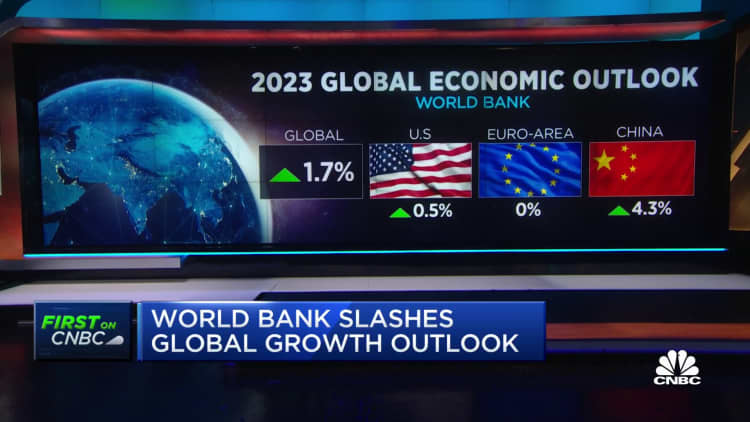
The international development institution downgraded almost all of its forecasts for advanced economies in the world, cutting its growth outlook for the global economy to 1.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} for 2023, it said in its latest report, Global Economic Prospects. The organization earlier projected the world economy to expand by 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2023.

related investing news

Investors could find better stock market returns outside the U.S. in 2023

CNBC Pro

The adjustment was led by a significant downgrade to its prospects for the U.S. economy — it now forecasts 0.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} growth from an earlier projection of 2.4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.

The World Bank cut its growth outlook for China for 2023 from 5.2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 4.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, Japan from 1.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} , and Europe and Central Asia from 1.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 0.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.

“Global growth has slowed to the extent that the global economy is perilously close to falling into recession,” the World Bank said, attributing an “unexpectedly rapid and synchronous” global monetary policy tightening behind the sluggish growth.

The downgraded estimates would mark “the third weakest pace of growth in nearly three decades, overshadowed only by the global recessions caused by the pandemic and the global financial crisis.”

Global growth has slowed to the extent that the global economy is perilously close to falling into recession.

The World Bank said that tighter monetary policies from central banks around the world may have been necessary to tame inflation, but they have “contributed to a significant worsening of global financial conditions, which is exerting a substantial drag on activity.”

“The United States, the euro area, and China are all undergoing a period of pronounced weakness, and the resulting spillovers are exacerbating other headwinds faced by emerging market and developing economies,” it said.

The global financial organization adjusted its 2024 forecasts lower as well, to 2.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from an earlier prediction of 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} growth.

China is ‘key variable’

A faster-than-expected China reopening poses great uncertainty for its economic recovery, the World Bank said in its report.

“The economic recovery [in China] may be delayed if reopening results in major outbreaks that overburden the health sector and sap confidence,” the report said. “There is significant uncertainty about the trajectory of the pandemic and how households, businesses, and policy makers in China will respond.”

A pedestrian in Pudong’s Lujiazui Financial District in Shanghai, China, on Tuesday, Jan. 3, 2023.

Bloomberg | Bloomberg | Getty Images

World Bank President David Malpass said on CNBC’s “Closing Bell” on Tuesday that “China is a key variable and there may be an upside for China if they push through Covid as quickly as they seem to be doing.”

“China’s big enough by itself to really lift global demand and supply,” he said.

“One of the questions for the world would be, which does it do most — if it’s mostly putting upward pressure on global demand, then that raises commodity prices. But it also means that the Fed will be hiking for a longer period of time,” he said.

Read more about China from CNBC Pro

Why the U.S. economy will avoid a recession, but freight will slow in 2023

Why the U.S. economy will avoid a recession, but freight will slow in 2023

The total U.S. financial system may well not be as certain for a recession in 2023 as the mainstream media has warned a lot of this 12 months. But the freight overall economy could have to start out the new year functioning its way out of a hole.

If you watch cable news, you are going to see and listen to a great deal economic negativity likely into 2023. But FTR Transportation Intelligence analysts are not as bitter on the future as the talking heads filling up space on your Tv.

“We get questioned a large amount about why aren’t we more detrimental than we are,” Todd Tranausky, FTR’s VP of rail and intermodal, reported for the duration of his firm’s December Condition of Freight webcast. “Yes, there’s gradual progress, but we really don’t have a economic downturn in our forecast. It never ever turns damaging again.”

Citing actual GDP quarterly changes on history, FTR tracked damaging development in the 1st two quarters of 2022, adopted by 2.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} advancement in Q3. Its forecast sees growth amongst .8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and 1.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in excess of the next five quarters—including the ultimate quarter of 2022.

But Tranausky observed that while GDP is a good metric to see how the basic financial system is faring, “it doesn’t drill down into what that usually means for transportation. There are things of GDP that—even if they are positive—do not always help transportation. And vice versa.”

Truckload volumes began the year at a better degree after good growth in 2021.

“Coming into 2022, we ended up managing at a rather good clip, forward of the pandemic ranges,” according to Avery Vise, FTR’s VP of trucking. “However, at any time due to the fact the end of Q1, it is been all downhill—at a very gradual slope.”

The FTR truckload forecast for 2023 is flat, Vise said. “But it’s flat from a rather potent stage,” he mentioned. “So it truly comes down to irrespective of whether you’re a glass-half-total or glass-50 percent-vacant person.”

3 good U.S. economic system signals for 2023

In this article is a look at three beneficial financial signals heading into the new yr and two indicators that need to give freight movers pause as they seem forward to 2023:

Payroll work growth continues

A single of the reasons FTR is fewer pessimistic than other prognosticators is the sound payroll development the U.S. overall economy has found all calendar year. “If you have examine the headlines or you noticed the careers report just very last week, you have listened to a great deal of dialogue around how that is going to make it more difficult for the Fed to gradual fascination fee hikes,” Tranausky defined. “And absolutely, payroll positions go on to operate at a healthy level—not as powerful as they have been—but they’re nevertheless chugging together at healthful levels.”

This implies People nonetheless are making cash to devote, he explained. “That’s a superior signal for the underlying economic climate and one thing that definitely provides us hope that we’re not likely to turn detrimental. We really don’t see a recession on the horizon.”

Industrial demand from customers has not been achieved

Continuous career advancement isn’t the only reason FTR is much more optimistic for 2023. Pent-up industrial desire is also driving the transportation sector forecast. Just after leveling off before this year, new orders for created goods are back on the rise, Tranausky mentioned.

“It’s surely much better than anything at all we saw prior to the pandemic,” he explained of industrial demand from customers. “The output actually hasn’t adjusted to that. It’s rising—but it’s undoubtedly rising a good deal slower.”

He stated the delta concerning orders and output would ultimately have to be achieved. “It’s likely to sustain ongoing financial activity—even if we see the economy downshift, you’re going to have some of that demand from customers that’s heading to have to do the job its way through the system,” Tranausky spelled out.

He said it could get at the very least 50 percent of next 12 months for the output to catch up with desire. “Even if we do get a even more downturned economic climate, there is continue to heading to be some time right before it truly flows via the numbers and flows by way of transportation.”

Buyers continue on to eat

A third cause FTR is a lot more bullish on the 2023 financial system is the American client. “We however really do not have any indication that use has fallen,” Tranausky explained. “Even with substantial inflation. Even with mortgage loan premiums likely up. Even with all the explanations to be detrimental out there, the facts does not however present that consumption is going down. We haven’t observed paying definitely take part in those declines.”

Using inflation into account, consumer paying out on goods and solutions is out-doing pre-pandemic trendlines, Tranausky famous. “So expending proceeds to hold in. At some stage out there in the potential, this just cannot keep on. But for the minute, it is keeping up extremely well and reveals no signals of holding again. It demonstrates no indications of likely again. It shows no signals of declining. 

“So that provides us hope as we assume about client investing, we imagine about usage, we think about demand in the overall economy,” he ongoing.

Why the freight financial state isn’t solid heading into 2023 

There is a “but,” Tranausky explained. “The over-all overall economy is performing pretty very well. But the economic climate is not so good for freight. We’re not seeing the exact form of fundamentals supporting the freight sector.”

Two good reasons freight could be much more sluggish in 2023 are that buyer consumption of providers is outpacing merchandise, and the sharp drop in imports assists out total GDP advancement but not the countrywide freight market place, according to FTR.

That sluggish freight, as Vise famous, is in contrast to just one of the busiest freight economies on record, which started off through the pandemic. 

Individuals expend a lot more on expert services than goods

The consumer paying that retains the total overall economy afloat has shifted from COVID-period merchandise investing to write-up-pandemic service shelling out, which added benefits items transportation significantly less than the e-commerce explosion did.

“If you search at the trucking side, if you glance at the rail facet, if you drill down into the distributors, that should not shock any one,” Tranausky said. 

Vise explained that while retail stock-to-sales ratios surged in 2022, the quantity has fallen in latest months. “I see this as a favourable because that suggests that vendors are presently reducing back—they’re not waiting for usage, which hasn’t fallen off however, to slide off,” he stated. “They know that it is going to, and they absolutely know it won’t increase. So they’re commencing to reduce back again on inventory.”

He mentioned this would slash into freight quantity in the around term but also reduces the likelihood of extra drastic “inventory correction, which I assume would certainly be a even larger trouble.”

Imports are down 

Right after the 12 months began with enormous West Coast port bottlenecks, imports have fallen sharply, “which individuals in the intermodal place undoubtedly have seen—particularly on the West Coast,” Tranausky reported. “That’s not essentially a positive indication for transportation ability as we go forward.”

The over-all U.S. Serious GDP followed up adverse quarters in the center of 2022 with growth in Q3, and FTR forecasts continued development in excess of the next five quarters through the stop of 2023. 

The picture is not as “rosy” for FTR’s GDP “goods transport sector,” which contracted in Q2 and Q3 this 12 months and forecasts far more contraction as a result of Q1 of 2023. 

“That’s four consecutive quarters of declines in phrases of GDP items transport,” Tranausky mentioned. “You see factors certainly holding in adverse territory but finding improved as we get to the end of this yr and into 2023. It’s undoubtedly a slower modify in outlook than we noticed in authentic GDP.”

But by the center of following yr, FTR is forecasting development in the merchandise transport sector in Q2 by way of Q4 of 2023.