A $3 Trillion Threat to Global Financial Markets Looms in Japan

A  Trillion Threat to Global Financial Markets Looms in Japan

(Bloomberg) — Study this in Japanese: 3兆ドルの日銀黒田レガシーが逆回転の恐れ、世界の金融市場に衝撃も

Most Read from Bloomberg

Financial institution of Japan Governor Haruhiko Kuroda altered the program of world-wide markets when he unleashed a $3.4 trillion firehose of Japanese income on the expense earth. Now Kazuo Ueda is probable to dismantle his legacy, setting the stage for a move reversal that challenges sending shockwaves by the international overall economy.

Just more than a week just before a momentous management adjust at the BOJ, buyers are gearing up for the seemingly inevitable close to a decade of ultra-minimal curiosity rates that punished domestic savers and despatched a wall of funds overseas. The exodus accelerated immediately after Kuroda moved to suppress bond yields in 2016, culminating in a mountain of offshore investments truly worth more than two-thirds Japan’s financial system.

All this threats unraveling below the new governor Ueda, who may have minimal option but to conclude the world’s boldest straightforward-money experiment just as increasing curiosity prices elsewhere are previously jolting the worldwide banking sector and threatening economic security. The stakes are enormous: Japanese buyers are the largest foreign holders of US govt bonds and individual every thing from Brazilian financial debt to European electrical power stations to bundles of risky financial loans stateside.

An increase in Japan’s borrowing charges threatens to amplify the swings in global bond markets, which are getting rocked by the Federal Reserve’s 12 months-extensive marketing campaign to beat inflation and the new danger of a credit score crunch. Versus this backdrop, tighter financial coverage by the BOJ is likely to intensify scrutiny of its country’s lenders in the wake of latest bank turmoil in the US and Europe.

A adjust in policy in Japan is “an further power that is not being appreciated” and “all G-3 economies in just one way or the other will be minimizing their harmony sheets and tightening policy” when it occurs, said Jean Boivin, head of the BlackRock Expenditure Institute and former Deputy Governor of the Financial institution of Canada. “When you management a price and loosen the grip, it can be difficult and messy. We believe it’s a major offer what happens following.”

The move reversal is previously underway. Japanese investors sold a history sum of abroad financial debt past year as regional yields rose on speculation that the BOJ would normalize plan.

Kuroda additional gas to the fire final December when he calm the central bank’s grip on yields by a portion. In just several hours, Japanese government bonds plunged and the yen skyrocketed, jolting all the things from Treasuries to the Australian greenback.

“You’ve presently seen the get started of that cash currently being repatriated again to Japan,” claimed Jeffrey Atherton, portfolio manager at Person GLG, section of Gentleman Group, the world’s major publicly traded hedge fund. “It would be rational for them to bring the cash property and not to consider the international exchange possibility,” mentioned Atherton, who runs the Japan CoreAlpha Equity Fund that’s crushed about 94{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of its friends in the previous calendar year.

Coming Household

Bets for a shift in BOJ coverage have eased in latest times as the upheaval in the banking sector raises the prospect that plan makers could prioritize money stability. Investor scrutiny of Japanese lenders’ stability sheets has developed, on concern they could echo some of the stresses that have floored quite a few regional US banking companies.

But current market members anticipate chatter on BOJ tweaks to resume when tensions dissipate.

Why Japanese Banking companies Are Properly Placed to Stand up to Banking Crisis

Ueda, the first at any time educational to captain the BOJ, is largely envisioned to speed up the pace of policy tightening sometime later on this year. Section of that may well contain further more loosening the central bank’s regulate on yields and unwinding a titanic bond-acquiring application developed to suppress borrowing prices and enhance Japan’s moribund economic system.

The BOJ has purchased 465 trillion yen ($3.55 trillion) of Japanese governing administration bonds considering the fact that Kuroda implemented quantitative easing a ten years ago, according to central financial institution information, depressing yields and fueling unparalleled distortions in the sovereign financial debt industry. As a final result, community cash sold 206 trillion yen of the securities during the period to search for greater returns elsewhere.

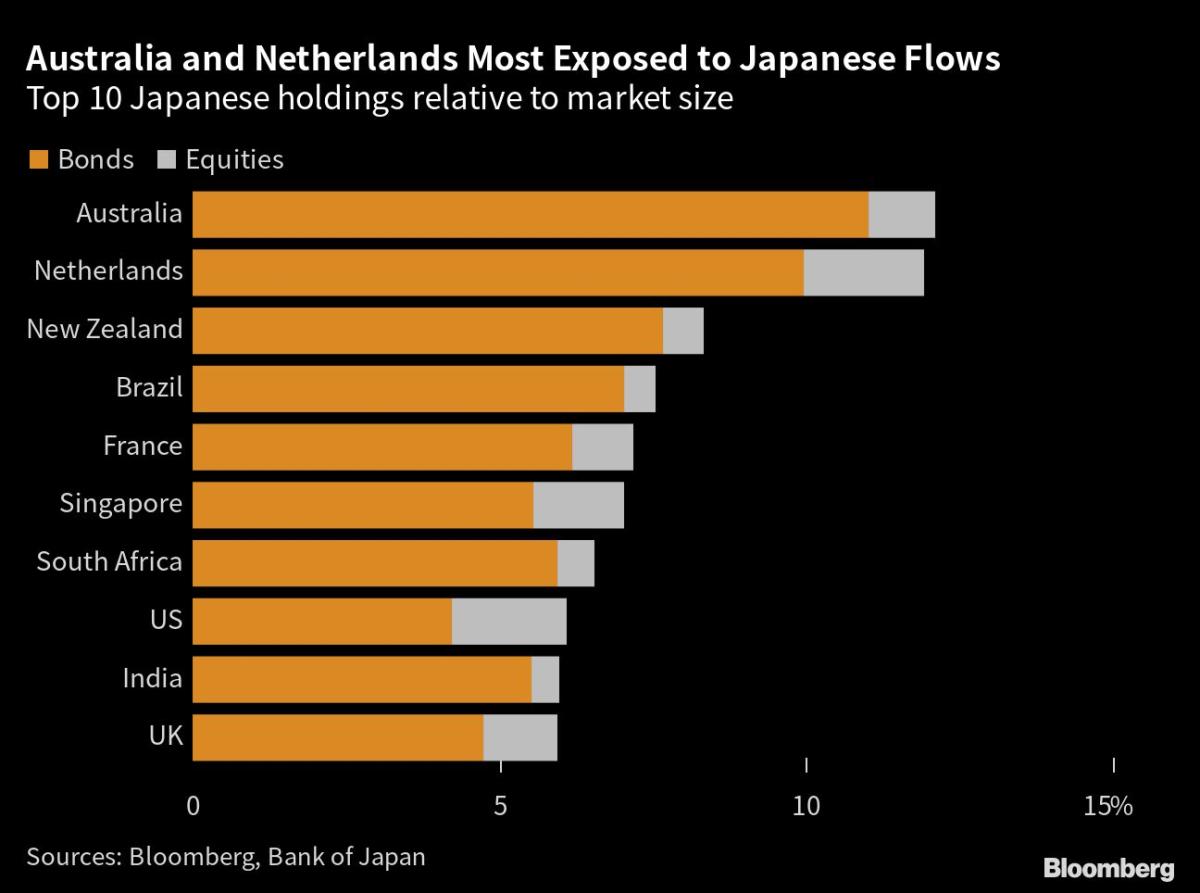
The shift was so seismic that Japanese investors turned the largest holders of Treasuries outside the house the US as effectively as house owners of about 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of Australian credit card debt and Dutch bonds. They also own 8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of New Zealand’s securities and 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of Brazil’s debt, calculations by Bloomberg show.

The attain extends to stocks, with Japanese traders obtaining splashed out 54.1 trillion yen on global shares given that April 2013. Their holdings of equities are equal to between 1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and 2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of the stock markets in the US, Netherlands, Singapore and the Uk.

Japan’s extremely-lower charges have been a big cause the yen tumbled to a 32-year small past calendar year, and it has been a top possibility for profits-seeking carry traders to fund buys of currencies ranging from Brazil’s real to the Indonesian rupiah.

“Almost undoubtedly it contributed to a considerable decline of the yen, a enormous dysfunctioning of the Japanese bond current market,” previous United kingdom federal government minister and Goldman Sachs Team Inc. main economist Jim O’Neill stated of Kuroda’s policies. “Much of what occurred in Kuroda’s time will partially or completely reverse” ought to his successor pursue coverage normalization, although the banking disaster may well bring about authorities to proceed more cautiously, he extra.

The forex has pulled back from last year’s lows, assisted by a see that normalization is inevitable.

Incorporate to that equation last year’s historic world bond losses, and Japanese traders have even more cause to flock home, in accordance to Akira Takei, a 36-calendar year current market veteran and money supervisor at Asset Administration One Co.

“Japanese debt traders have had bad encounters outdoors the place in the past 12 months since a considerable leap in yields forced them to cut losses, so lots of of them even don’t want to see foreign bonds,” said Tokyo-centered Takei, whose agency oversees $460 billion. “They are now wondering that not all funds have to be invested abroad but can be invested domestically.”

The incoming president of Dai-ichi Lifetime Holdings Inc., a single of Japan’s largest institutional buyers, confirmed it was shifting a lot more income to domestic bonds from overseas securities, right after intense US level hikes created it highly-priced to hedge versus currency risks.

To be sure, several are geared up to go all out in betting Ueda will rock the boat at the time he will get into office.

A the latest Bloomberg survey confirmed 41{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of BOJ watchers see a tightening phase getting location in June, up from 26{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in February, when former Japan Vice Finance Minister Eisuke Sakakibara claimed the BOJ may well increase premiums by Oct.

A summary of views from the BOJ’s March 9-10 assembly confirmed the central lender stays cautious about executing a plan pivot before acquiring its inflation concentrate on. And that was even just after Japan’s inflation accelerated outside of 4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to set a fresh new 4-decade high.

The next central bank conference, Ueda’s to start with, is scheduled to get place April 27-28.

Richard Clarida, who served as Vice Chairman at the Federal Reserve from 2018 to 2022, arguably has a lot more perception than most following getting recognised “straight shooter” Kuroda for several years and weighed Japan’s impression on US and worldwide monetary policy.

“Markets expect pretty early less than Ueda that yield-curve control is dismantled,” mentioned Clarida, who is now worldwide economic advisor at Pacific Financial commitment Administration Co. From in this article Ueda “may want to go in the course to shrink the harmony sheet or reinvest the redemptions, but that is not a person for day a single,” he said, including Japan’s tightening would be a “historic moment” for marketplaces nevertheless it could not be a “driver of world-wide bonds.”

Gradual Shift

Some other industry watchers have additional modest expectations of what will occur when the BOJ rolls again its stimulus application.

Ayako Sera, a market strategist at Sumitomo Mitsui Have faith in Financial institution Ltd., sees the US-Japan price hole persisting to a degree as the Fed is unlikely to supply substantial fee cuts if inflation remains higher and the BOJ isn’t anticipated to elevate fees considerably in the around time period.

“It’s vital to evaluate any tweaks and outlooks of the BOJ’s full monetary coverage package when wondering about their implication on the cross-border fund flows,” she reported.

Ryosuke Oshima, deputy common manager of product advertising team at Mitsubishi UFJ Kokusai Asset Administration Co. in Tokyo, is eyeing yield concentrations as a opportunity trigger for a change in flows.

“There may possibly be some urge for food for bond resources when the premiums transfer increased, like 1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} for the 10-year produce,” he reported. “But seeking at the knowledge, it is not likely they reverse all their investment decision back again household abruptly.”

For other people like 36-yr marketplaces veteran Rajeev De Mello, it is very likely only a issue of time prior to Ueda has to act and the consequences may perhaps have world repercussions.

“I thoroughly concur with the consensus that the BOJ will tighten — they’ll want to stop this policy as before long as possible,” explained De Mello, a money manager at GAMA Asset Management in Geneva. “It comes down to central bank trustworthiness, it will come down to inflation conditions being more and more fulfilled now — normalization will come to Japan.”

–With support from Winnie Hsu, Ayai Tomisawa, Hideyuki Sano, Yumi Teso, Emily Cadman and Jane Pong.

Most Go through from Bloomberg Businessweek

©2023 Bloomberg L.P.

China E-Commerce Giant Alibaba Outlines Future Strategy

China E-Commerce Giant Alibaba Outlines Future Strategy

HONG KONG (AP) — The CEO of Chinese e-commerce and fiscal large Alibaba stated Thursday that the organization is going toward giving up regulate of some of its enterprise models in a transition toward becoming a capital operator to enhance the price of its sprawling firms.

Daniel Zhang outlined facts of a approach announced before this week to break up Alibaba into six main groups as a prelude towards stock listings of some of its firms. The restructuring marks a new stage in Alibaba’s growth soon after a series of setbacks as regulators cracked down on it and other tech firms.

Alibaba, whose headquarters is in the jap city of Hangzhou, will be “in the mother nature of a holding organization that is the controlling shareholder of the business group organizations,” Zhang explained in a convention simply call.

Alibaba’s CFO, Toby Xu, said the company would keep on to evaluate the strategic significance of group firms just after they go public and make your mind up no matter if or not to retain command. He declined to say when they could possibly go community.

“We believe that the industry is the very best litmus exam, so every enterprise team organization can go after unbiased fundraising and IPOs as and when they are ready,” Xu explained.

Political Cartoons

Alibaba’s stock rates in Hong Kong and New York have rallied approximately 15{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} considering that the restructuring was declared Tuesday. The firm’s Hong Kong-outlined stock was up .9{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} by midday Thursday.

The plan, and the latest return of Alibaba founder Jack Ma to China following months overseas seem to mark a turnaround after many hard yrs. Chinese regulators singled out Alibaba for scrutiny in a crackdown on technology and net providers, placing the brakes on a prepared original public featuring in 2020 of Alibaba’s fiscal affiliate Ant Team.

Ma had retained a lower profile with handful of public appearances considering the fact that Nov. 2020, when he experienced publicly criticized China’s regulators and monetary techniques all through a speech in Shanghai.

Ant had been set to elevate $34.5 billion in what would have been the world’s biggest share providing at the time. Alibaba was later on investigated and fined $2.8 billion for breaching antitrust procedures as Chinese authorities cracked down on the the moment-freewheeling engineering marketplace.

“The looser connections amongst the business enterprise units is in line with the regulatory stance of encouraging levels of competition,” said an analyst’s observe from Moody’s Trader Services.

Amid other issues, the restructuring prepare could possibly allay this sort of antitrust concerns, because as Zhang discussed, just about every Alibaba company unit would be empowered to make its have decisions and increase funds independently. He claimed that obtaining business enterprise models work independently should really also foster innovation and growth soon after a long time of severe COVID-19 constraints that battered China’s economic system.

Alibaba’s restructure — the to start with of its kind in the Chinese technologies sector — also could provide as an illustration for comparable corporations these types of as on the internet games enterprise Tencent to adhere to go well with. Tencent’s shares rallied following Alibaba’s announcement on Monday.

“We imagine that Alibaba’s new organizational composition could be made use of by Chinese regulators as a template for other Chinese Significant Tech firms,” stated a report by CreditSights.

Copyright 2023 The Affiliated Press. All rights reserved. This substance may possibly not be revealed, broadcast, rewritten or redistributed.

Blood pressure checks to fight Black maternal mortality : Shots

Blood pressure checks to fight Black maternal mortality : Shots

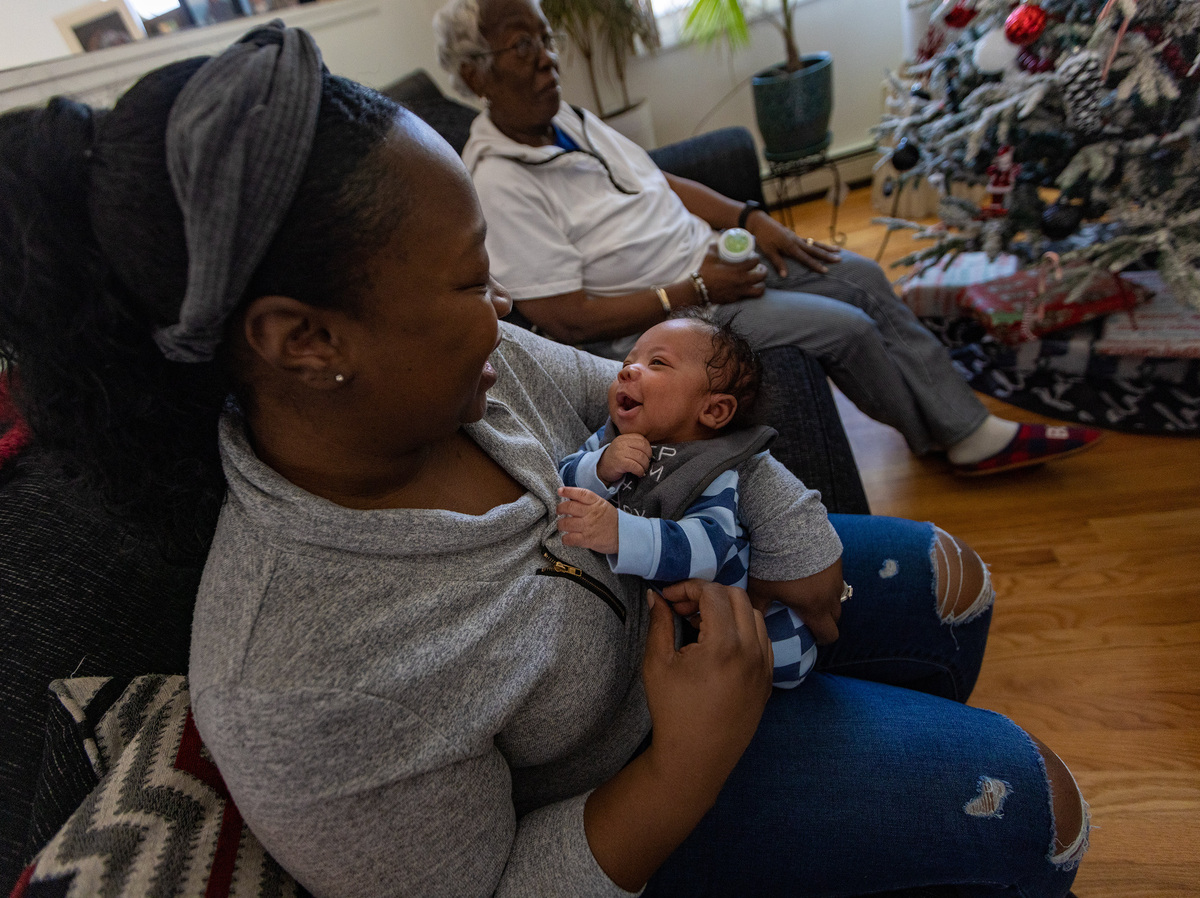
Kennise Nevers holds her son, AJ, in her arms at household. Nevers’ mother, Nancy Josey, seems on.

Jesse Costa/WBUR


hide caption

toggle caption

Jesse Costa/WBUR


Kennise Nevers retains her son, AJ, in her arms at dwelling. Nevers’ mother, Nancy Josey, appears to be like on.

Jesse Costa/WBUR

With each feet flat on the flooring, Kennise Nevers settles into the couch in her residing home. She peels open up a blood stress cuff, and straps it around her left arm, exhaling as it squeezes her bicep.

Soon after a moment, she receives the reading through. “It is really fantastic,” says the mother of two from Brockton, Massachusetts.

Nevers, 37, tracked her blood force at home just about every working day for months as component of a plan for clients at Boston Health-related Middle who are pregnant or just lately experienced infants and are at hazard for hypertension. That best examining Nevers acquired was transmitted to her health care file and reviewed by a nurse.

Blood force is just just one way to evaluate a person’s well being, but all through being pregnant and quickly soon after, it can be a essential metric. Unchecked, superior blood tension can contribute to serious complications for the expecting female and little one, and increase the possibility of demise.

So for Nevers, it was a reduction to know that wellness treatment suppliers have been monitoring her quantities so carefully.

“Of program, you might be generally going to get worried: It truly is being pregnant. Issues improve all the time,” she states. “But it eased some of my worry. I experience like I had physicians often on my aspect, searching after me. I was not forgot about.”

Being pregnant-relevant loss of life

Scientific tests show that Black folks are far more than two times as likely as white men and women to knowledge significant being pregnant-similar difficulties, and practically 3 situations as probably to have a being pregnant-connected demise.

The U.S. has the worst maternal mortality price of superior-money nations around the world in the world — and the figures are climbing. New federal information demonstrates maternal deaths spiked 40{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2021.

Several significant challenges stem from higher blood stress, claims Dr. Tina Yarrington, director of maternal-fetal medicine at BMC.

“It is the root bring about for a lot of, several maternal wellbeing inequities,” she suggests. “People today who are marginalized by structural racism, individuals who are Black, African American, Latina, Hispanic, undergo bigger levels of hypertension and bigger concentrations of complications when that hypertension strikes.”

Blood pressure measures the power of blood pushing towards the artery partitions. When that drive is far too large through pregnancy — a issue named pre-eclampsia — it can lead to stroke, organ problems, pregnancy loss or small birth pounds for the child. It also raises the risk of death for the pregnant person and newborn.

Pre-eclampsia impacts about 14{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of BMC’s white sufferers, but 18{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of its Black clients — a compact but significant change.

“That is the gasoline for this hearth,” Yarrington states. “That is why we’re putting so much power and get the job done into pre-eclampsia, in the fascination of not just better outcomes, but much better results precisely for the populations that have experienced from inequities.”

Near enjoy, quick action

Higher blood stress is at times referred to as the “silent killer” since it can out of the blue increase to unsafe ranges without having causing agony or other indicators. That is why BMC has assigned a nurse, Megan O’Brien, to check out patients’ quantities everyday.

Every time a patient will take a examining at house, their blood pressure cuff sends the quantities straight to their electronic health file. The cuffs do not want an world-wide-web connection they use the sign of close by cell towers.

“The to start with factor I do each individual morning is search at all of the high readings that have arrive in considering that the evening before,” O’Brien says.

If she sees a about number, she follows up ideal absent — normally with the enable of interpreters for sufferers who don’t speak English.

The patient might require a new treatment. Or they may need to have to arrive to the healthcare facility to be monitored. In some cases, blood pressure spikes so rapidly that sufferers have to deliver their toddlers early to avoid serious complications.

After delivery, some sufferers are even now at hazard of establishing seizures, stroke, heart assaults or other issues. O’Brien displays their numbers, as well.

The every day at-house blood force checks enable nurses and doctors to spot troubles early and act sooner. “We are intervening so much more quickly in these possible problems that could be taking place at household,” O’Brien claims. “It truly is seriously about catching people as speedy as feasible.”

A mobile blood pressure monitoring procedure in its packaging. The check sends the details from every reading through right to Boston Clinical Centre for wellbeing employees to evaluation.

Jesse Costa/WBUR


conceal caption

toggle caption

Jesse Costa/WBUR


A cellular blood strain monitoring process in its packaging. The keep track of sends the knowledge from each and every reading immediately to Boston Healthcare Centre for health and fitness workers to overview.

Jesse Costa/WBUR

BMC’s property-checking method began for the duration of the COVID pandemic. The hospital started providing blood force cuffs to postpartum clients in 2020, when in-man or woman health-related visits were being disrupted, and last spring, expanded to include expecting sufferers.

‘Interrogate’ disparities

This hard work is section of a sweeping healthcare facility-wide initiative to just take superior treatment of men and women of shade and remove racial and ethnic disparities in overall health treatment.

Healthcare facility leaders dove into facts about their patients and uncovered stark disparities in being pregnant, as nicely as COVID, diabetic issues, cancer and behavioral wellbeing. They found, for example, that their Black clients had been 2 times as likely to develop being pregnant-associated troubles as white patients.

“You will find no way you can discover all those factors and not interrogate them and have an intentionality to improve them,” suggests Dr. Thea James, vice president of mission and co-executive director of the Wellbeing Equity Accelerator. “It is unethical to see people matters and leave them there.”

Some of the perform is in getting rid of the likely for bias and subjectivity throughout final decision-building — for instance, deciding when pregnant patients with pre-eclampsia must provide their babies.

“We noticed that it was taking two times as prolonged to make that final decision in Black females,” James says. “So the to start with point we did was to standardize the conclusion-generating course of action.”

BMC has enrolled hundreds of individuals in the initiative to keep track of blood force at residence throughout and soon after pregnancy about 80{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of them are Black or Hispanic, reflecting the makeup of the hospital’s overall affected person populace.

Basic, but not simple

It may perhaps look like a very simple intervention. But not all overall health care companies have funding to pay back for a residence-checking software and committed personnel to operate it. Well being insurance policy ideas ordinarily do not deal with these fees.

And though some individuals really don’t intellect examining their blood force at house, other individuals may come across it too stress filled or time-consuming.

“Making a routine is tricky for everything,” says Dr. Lara Kovell, director of the pregnancy and heart disease clinic at UMass Memorial Health care Heart in Worcester, Mass.

Kovell is element of a staff of researchers at UMass Memorial, Yale University and the College at Buffalo who are studying the use of at-home support, such as blood tension monitoring, for postpartum patients.

“Maternal mortality remaining three- to 4-fold larger in our Black ladies is just one thing that genuinely desires to transform,” Kovell claims. “And I consider hypertension is a single of the points that will get to that.”

Dr. Rose Molina, an OB-GYN at Beth Israel Deaconess Clinical Heart in Boston, reported analysis on house monitoring so far continues to be inconclusive — while there appears to be minor downside to providing people blood strain cuffs at household.

“I do not imagine that there is automatically harm,” she states, “but there is certainly still questions close to how do we develop the process close to self-monitoring that genuinely is substantial-benefit in conditions of acquiring a scientific effect, and also saving expenses, ideally, in some way.”

Health professionals at BMC are continue to learning the impacts of dwelling monitoring, but they have viewed some promising early success.

Infant AJ’s arrival

Kennise Nevers was eight months pregnant and cooking rooster for a major relatives dinner a person evening in October when her blood force instantly spiked.

“We were actually acquiring ready to enjoy playing cards,” Nevers recollects. “And I was like, ‘Oh, permit me just verify my blood pressure just before I engage in.’ And the evening ended fairly fast.”

She went to the healthcare facility suitable absent. The next working day, medical doctors induced labor, and her infant, AJ, was born.

He arrived 3 months early, but solid and nutritious.

“It was a relief,” Nevers claimed. “I was so fearful in the course of the pregnancy due to the fact of my blood strain.”

Nevers produced it past the high-risk postpartum times with no producing a complication.

But she has long-term hypertension, so she continue to retains a blood strain cuff close by.

Is the global economy deglobalizing? And if so, why? And what is next?

Is the global economy deglobalizing? And if so, why? And what is next?

The globalization of the world financial system continued even as a result of the COVID pandemic, but current variations in federal government coverage and community sentiment could herald a new period of deglobalization, implies a paper to be mentioned at the Brookings Papers on Economic Exercise (BPEA) conference on March 31.

The authors—Pinelopi K. Goldberg of Yale University and Tristan Reed of the Environment Bank—use knowledge on trade, capital flows, and immigration to present that, after advancing promptly for two a long time, globalization slowed, but continued, right after the 2008-2009 money crisis.

Authorities coverage and public sentiment began to change toward deglobalization all over 2015 with rising issue about the labor marketplace effect of U.S. imports from lower-wage nations fueling a trade war concerning the United States and China. But the financial consequences, although significant, had been not adequate to reverse decades-aged globalization trends, in accordance to the paper, Is the World-wide Overall economy Deglobalizing?

The pandemic lifted inquiries about the fragility of international offer chains and generated requires for “reshoring” generation domestically. But, just after a short-term drop in 2020, trade improved sharply. U.S. companies, for the most element, held on to their relationships with foreign suppliers and even pursued new kinds.

Goldberg and Reed Figure 1, BPEA Spring 2023

“If nearly anything, trade increased economies’ resilience in the course of the COVID pandemic,” the authors write. For case in point, imports of deal with masks from China and Korea achieved desire that could not be matched by U.S. suppliers.

Even so, Russia’s invasion of Ukraine in February 2022, by exposing Europe’s dependence on Russia for strength, established new demands for reshoring and “friendshoring” (trading only with welcoming international locations). For occasion, the United States in Oct 2022 imposed sweeping limits on semiconductor exports aimed at protecting against China from advancing technologically.

“We are in a shifting landscape.”

“These developments can plausibly be thought of the markers of a new period,” the authors create. They conclude their paper with “highly speculative” feelings about the very long-run probable consequences if deglobalization has, in simple fact, begun. Amid them:

  • Improved friendshoring could enhance countries’ resilience to geopolitical shocks, these types of as war, but reduce resilience to other shocks, this kind of as pandemics.
  • Expansion and innovation could gradual in a deglobalizing world overall economy, with a decoupling between the United States and China posing a specific risk.
  • Reduced foreign level of competition in the type of trade and immigration could add to bigger selling prices and wages in the United States.
  • As state-of-the-art economies transform inward, poverty reduction and enhancement could slow in little, low-earnings countries that have relied on exports.

“We are in a shifting landscape,” Goldberg explained in an job interview with The Brookings Establishment. “We evidently see a reversal in plan. We really do not see the outcomes in knowledge but, but given the reversal in plan, you would count on big consequences down the street.”


Citation

Goldberg, Pinelopi K. and Tristan Reed. 2023. “Is the Global Economic climate Deglobalizing? And if so, why? And what is future?” BPEA Convention Draft, Spring.

DISCLOSURE

The authors did not get economic assist from any company or man or woman for this short article or from any agency or particular person with a money or political desire in this short article. The authors are not at the moment an officer, director, or board member of any corporation with a monetary or political curiosity in this article.

Credit Suisse whistleblowers say bank has been helping Americans dodge U.S. taxes

Credit Suisse whistleblowers say bank has been helping Americans dodge U.S. taxes

Senate Finance Committee: Credit Suisse helped Americans commit tax fraud

Credit Suisse, the collapsed Swiss bank taken over by UBS Group in a hastily arranged bailout earlier this month, may bring with it a fresh set of regulatory and legal problems for its new owner.

For years, the bank has provided a safe haven for wealthy American clients to hide assets from the IRS — even after it was caught and prosecuted for doing the same thing more than a decade ago, according two former Credit Suisse bankers who spoke in exclusive interviews with CNBC and are working with the U.S. government as whistleblowers.

The bank notoriously pleaded guilty in 2014 to criminal charges for “knowingly and willfully” helping thousands of U.S. clients conceal their offshore assets and income from the IRS. It admitted at the time that it used sham entities, destroyed account records, and hand delivered cash to American clients to avert IRS detection — agreeing to crack down on U.S. tax dodgers going forward as part of its plea deal. Credit Suisse also agreed at the time to a host of reforms, including disclosing its cross-border activities and cooperating with authorities when they request information, among other things.

The now troubled bank appears to have violated that agreement, according to a new report by the Senate Finance Committee that details ongoing and rampant abuse since then. The report, released Wednesday, details the findings of the panel’s two-year investigation and takes on more urgency given the looming banking crisis. The Swiss National Bank, the country’s central bank, injected more than $100 billion of liquidity into Credit Suisse to keep it afloat earlier this month, while the Swiss government agreed to provide UBS with some $9 billion to backstop losses resulting from the takeover.

‘Still ongoing’

Senate investigators say the new revelations raise questions about just how much American money remains hidden inside the vaults of a bank whose collapse rattled the foundations of the global banking system.

The Senate report, which was prepared by the panel’s Democratic staff, accuses the bank of violating the terms of its 2014 plea agreement, which could trigger a host of repercussions if the Justice Department presses the case. It is unclear how much potential liability UBS is exposed to as a result of the report, but a lawyer for the whistleblowers argues the bank should pay as much as $1.3 billion.

Senate Finance Committee Chairman Ron Wyden, D-Ore., said his committee had received new information just this week from Credit Suisse about additional American undisclosed accounts that the bank held after 2014.

“It is still going on as of just the last couple of days — even more money has been found to have been concealed and there are very substantial issues here,” Wyden said. “Clearly, it’s time to prosecute and ensure that there are penalties that send a strong message.”

“Credit Suisse employees aided and abetted a major criminal tax evasion scheme,” a finance committee aide said, asking not to be named because the report had not been released yet. “To date, no Credit Suisse employees involved in the scheme have faced any consequences from the United States government for their participation.”

Hiding fortunes

Senate investigators say they discovered that Credit Suisse enabled as many as 25 American families to hide fortunes totaling more than $700 million in the bank in the years after Credit Suisse’s plea agreement.

“They thought they could get away with it, and they largely did,” the aide said. “It’s not a question of whether Swiss banks continue to do this, it’s a question of which Swiss banks still do this.”

In a statement to CNBC, a Credit Suisse spokeswoman said it does not tolerate tax evasion.

“In its core, the report describes legacy issues, some from a decade ago, and we have implemented extensive enhancements since then to root out individuals who seek to conceal assets from tax authorities,” the spokeswoman said, asking not to be identified because she was not authorized to speak on the record. She said the bank’s new leadership team has been cooperating with the committee. Credit Suisse has “supported the work of Senator Wyden, including in respect of suggested policy solutions to help strengthen the financial industry’s ability to detect undisclosed US persons.” She said the bank’s policy requires it to close undeclared accounts when they’re identified and discipline employees who don’t follow its policy.

A sign of Credit Suisse bank is seen at their headquarters in Zurich on March 20, 2023.

Fabrice Coffrini | AFP | Getty Images

The two former Credit Suisse employees, who worked as whistleblowers with the U.S. government and Senate investigators, told CNBC some of the bad behavior continued long after Credit Suisse’s 2014 plea agreement. CNBC agreed to mask their identities on camera and to maintain their anonymity because they say they fear retaliation from the bank. They were interviewed in the weeks before Credit Suisse collapsed earlier this month.

Although the bank did disclose and close many American accounts after its 2014 plea agreement, some bankers worked with high net worth clients to keep certain Americans at the bank, by changing the nationalities listed on their accounts and ignoring evidence that the account holders were Americans. In other cases, they helped American clients move money to other banks, without reporting those transfers to U.S. authorities, the whistleblowers say.

‘Tremendous pressure’

The report and interviews offer a rare look at the inner workings of the secretive Swiss banking, a world rarely penetrated by outsiders. And they show how compliance systems inside Credit Suisse broke down in the years before its collapse this month and rescue by the Swiss government and rival bank UBS.

Bankers are under constant pressure, the whistleblowers said, to keep and bring in deposits at the bank.

“You’re under tremendous pressure to bring in these net new assets, which ultimately translate into revenue,” the first whistleblower said in describing a culture where bankers were expected to keep the assets of wealthy clients inside the bank, even if they had to cheat to do it. “And that’s the reason for the fraud. You don’t want to lose assets. So, what you do is you try to maintain them in any way, shape, or form.”

Senior executives would call out individual bankers at quarterly meetings where they would read out the asset numbers for each banker. If a banker’s number declined, the second whistleblower said, “you’d get exposed in front of your colleagues.” And as a result, he said, “there may come moments where people simply omit saying things.”

“‘Don’t Ask, Don’t Tell’ is maybe a good explanation to what happened,” he said. “They would have clients that are Americans, but they would switch their passports around to show and flag as if they are not.”

Credit Suisse bankers, for instance, repeatedly flew to Miami to meet with American clients and yet failed to flag them as U.S. citizens, Senate investigators said.

Secrecy drives the entire Swiss banking industry, the first whistleblower said – to a point that the sector may not be able to survive without it.

“Swiss banks are much more expensive, and there’s a reason for that,” he said. “If you could choose anywhere in the world you want to be, why would you pay more? Why would you be in a place which underperforms in terms of your return on assets?”

If a client isn’t hiding assets in Switzerland, the first whistleblower said, “there’s no other reason to be there.”

‘Congratulation!!!!!’

Emails obtained by the Senate Finance committee show just how far the bankers went to keep identities secret and to ensure wealthy Americans were able to switch nationalities — at least for the bank’s internal record-keeping.

In one email, one of Credit Suisse’s banker writes to another bank employee, “please don’t write or document these topics.”

One American client, an heir to a $200 million fortune deposited at Credit Suisse, emailed to say they renounced their U.S. citizenship.

“I tried to reach you, congratulation!!!!!” their private banker emailed back. “This is a big step for you and I know it was not easy.”

The heir to the fortune replied, “Thanks … hopefully this should also make Credit Suisse now more relaxed.”

The heir closed the message with a smiley face.

The Family

“The committee’s investigation uncovered major violations of Credit Suisse’s plea agreement, including an ongoing and potentially criminal tax conspiracy involving nearly $100 million dollars and undeclared offshore accounts belonging to a family of dual U.S./Latin American citizens,” a committee aide told CNBC.

The aide said Credit Suisse closed accounts held by that family worth nearly $100 million in 2013 and moved funds to other banks in Switzerland and elsewhere, but did not inform U.S. authorities about the transfer of assets until 2021 – which was months after whistleblowers informed U.S. authorities of the existence of the accounts.

In the Senate report the clients are not named, but simply referred to as “The Family.”

While it’s legal for Americans to hold funds in foreign bank accounts, they must file forms with the IRS disclosing the assets and pay taxes on any relevant gains. Americans must file a disclosure document called a Report of Foreign Bank and Financial Accounts, which is referred to in the industry as an “FBAR.”

The committee said the family held assets at Credit Suisse dating as far back as 1979, and they found evidence Credit Suisse bankers visited members in the family in Miami as early as 2000, holding meetings at the Mandarin Oriental hotel and enjoying meals at The Capital Grille restaurant in Miami’s fashionable Brickell neighborhood overlooking Biscayne Bay.

But aides say they didn’t find any evidence the family ever filed required paperwork with the U.S. government or paid taxes on their assets. Instead, the assets were held under one family member’s dual Latin American passport.

Legal jeopardy

As a result, the aide said, “They’re potentially in legal jeopardy, to put it mildly.”

Committee aides say the family’s assets were overseen by a high-level Credit Suisse executive in its Latin American division, and that official participated in the meetings in Miami. That’s notable, aides said, because that same official was the supervisor of several other Credit Suisse bankers who were previously indicted in connection with the 2014 American offshore accounts.

Committee aides complained that Credit Suisse declined to provide the names of any of the employees involved or the Swiss banks that received the funds – but said they were able to determine that information through other sources.

The Miami case “is not small potatoes,” a Senate aide said. If proven, it “would be one of the largest FBAR violations in United States history.”

Former Justice Department prosecutor Jeffrey Neiman, who is representing the whistleblowers, said he believes fraud is still ongoing and the DOJ should claw back hundreds of millions of dollars in fines that the bank agreed to pay in 2014, but ultimately didn’t have to pay. The bank agreed to pay $2.6 billion, but a federal judge only imposed a penalty of $1.3 billion at the time.

“I think Credit Suisse is aware of Americans who are still hiding money today. And I think the bank is doing whatever it can to contain whatever this damage is,” Neiman said.

$1.3 billion

“At a minimum, the U.S. government needs to collect that $1.3 billion for the American taxpayers. This bank needs to be made an example of,” he said. “We hear tough talk out of the Justice Department about holding repeat corporate offenders accountable. Let’s see if those words have actual meaning.”

The whistleblowers stand to gain financially if there are further payments to the U.S. government. Under the law, whistleblowers stand to collect between 15{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and 30{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of any money recovered by the U.S. government as a direct result of information they provide.

The Senate Finance Committee doesn’t think U.S. prosecutors have gone far enough in holding Credit Suisse accountable, the aide said. The report is part of a campaign to up the pressure on the DOJ to crack down on the Swiss bank, and the recent takeover of the bank puts it squarely in the spotlight.

“DOJ must correct its lax oversight of Credit Suisse and hold Credit Suisse accountable for any violations of its plea agreement,” he said.

The aide cited recent indications of a white-collar crackdown. “DOJ said we will go after anybody at banks who commits tax evasion,” the aide said. “Then do it. We’re going to drop you twelve names in this report. Go after them.”

The Justice Department declined to comment when contacted for this story.

‘Never say never’

CNBC Politics

Read more of CNBC’s politics coverage:

J.D. Power: EVs affordable with tax incentives and more supply

J.D. Power: EVs affordable with tax incentives and more supply

Light-car price ranges have trended down through the very first quarter of this 12 months, but the drop for EVs is much steeper than gasoline cars.

The normal transaction cost for an EV has fallen 7.5 percent from $60,791 in January to $56,214 in March, in accordance to J.D. Electricity. In that exact same interval, the normal transaction rate for internal combustion gentle cars dropped 2.5 p.c to $45,274 from $46,412.

At the start out of the 12 months, buyers faced a 31 p.c top quality in the common transaction price tag to acquire an EV. That stands at 24 per cent now, according to J.D. Electric power data.

EVs are no for a longer period confined to luxurious buyers, claimed Jessica Caldwell, government director of insights at Edmunds.

“The selection of people who will shop for and take into consideration EVs will go up considerably with an expanded range of selections, human body variations and models,” she stated. “This is the 1st stage in direction of what requirements to come about for this rising technological know-how to strike the mainstream.”

Some EVs have arrived at price parity with similar gasoline models. Chevrolet slashed the cost of the 2023 Bolt EV by about $6,000. The Bolt’s starting selling price is $27,495, which includes shipping. J.D. Electric power expects the pricing slide to keep on industrywide as new models spark competition in the EV sector.

Tesla, the most important EV seller in the U.S., reduce selling prices in mid-January, just as its most well known autos turned suitable for the $7,500 federal tax credit score under the Inflation Reduction Act. Tesla has considering that produced scaled-down cost changes to the Design 3 sedan and Product Y crossover.

The base value of the Design 3 has fallen from $48,440 to $44,630 with shipping, when the foundation Design Y crossover sticker has fallen from $67,440 with shipping to $56,630. Registrations of each vehicles surged in January, according to Experian.

Condition tax credits also are a considerable driver of EV fascination. California has the optimum EV adoption score in the state. Buyers there get $2,000 for a order or lease of an electric vehicle and $4,500 for an electrical truck, SUV or van. State-level EV incentives helped increase adoption in Oregon, Colorado, New York and New Jersey.

Declining prices and broader preference are contributing to rapid EV revenue development. J.D. Energy expects a few in 4 customers to have a feasible EV choice by the conclude of 2026.

About 8.5 p.c of new-vehicle revenue and leases had been EVs in the very first two months of this calendar year, a report superior and virtually double the share from a 12 months in the past, J.D. Energy mentioned.

New EV registrations surged 57 {515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} final year to 756,534, while the overall U.S. sector fell 11 p.c to 13.6 million light-weight cars, according to Experian. EVs climbed to 5.6 {515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of registrations from 3.1 p.c a year previously.

The exploration firm’s EV affordability index rose to 87 on a 100-position scale in February, driven primarily by Inflation Reduction Act incentives. It hovered all around 82 late past calendar year. As soon as it climbs to 100, EVs will have attained cost parity with inside combustion motor vehicles.

In Northern California, EV need is “insatiable,” claimed David Lengthy, executive standard supervisor of Hansel Auto Group, which has Ford, Lincoln, BMW, Subaru, Honda, Acura, Volkswagen and Toyota franchises.

Long’s group sells every single EV the brand names ship, and he also has pre-orders. Hansel has extra EV shoppers than the two used-automobile and gasoline-powered new-automobile customers mixed, but the closing ratio for EV buyers is reduced than for gasoline-run car customers.

Prolonged claimed that many buyers are curious about EVs but usually are not all set to acquire a single.

Gasoline-powered vehicle consumers generally know what they want when they occur in to the showroom. With EVs, “there is certainly so lots of issues about charging and points that they truly want to listen to another human being explain to them and demonstrate them,” Prolonged claimed. “And I imagine that’s where the closing ratio will get eroded.”

Only 1 in 10 consumers will buy an EV by the close of this yr, J.D. Power reported, irrespective of the cost drop and boost in inventory.

Extensive stated that even with a reduce closing ratio, EV consumers nonetheless profit Hansel’s very long-time period business enterprise.

“We have experienced to turn out to be seriously, definitely superior at getting capable to present consumers with details,” he mentioned. “The more we can communicate to our customers, the extra comfy they will be [and] the much easier it will be for them to make that determination to transition from ICE to EV.”

Laurence Iliff contributed to this report.