Persons glimpse at the Volkswagen id excitement electric vehicle all through the push working day at the Los Angeles Car Exhibit in Los Angeles, California, November 17, 2022.
Mike Blake | Reuters
Volkswagen on Tuesday declared plans to devote 180 billion euros ($192.6 billion) between 2023 and 2027, with far more than two thirds concentrating on “electrification and digitalization.”
The German automotive large earlier this thirty day period posted a total-calendar year 2022 running financial gain of 22.5 billion euros, up 13{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from the past 12 months, with battery and electric car or truck (BEV) deliveries mounting 26{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.
similar investing news
The BEV expansion was driven by a 68{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} spike in China, whilst the organization also done the landmark electrification of its plant in Chattanooga, Tennessee.
Nonetheless, general shipping and delivery quantities declined by 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 8.3 million vehicles in 2022 and the automotive division’s internet funds flows lowered to 4.8 billion euros from 8.6 billion euros in 2021.
In Tuesday’s once-a-year report, the company attributed this to “an boost in performing money thanks to supply chain and logistics issues, primarily to the stop of the yr,” and projected this really should “mainly reverse” in excess of the program of 2023.
CEO Oliver Blume reported Volkswagen “set very clear and bold targets and took required conclusions to streamline procedures” in 2022, even though the coming 12 months will be “decisive” for executing the group’s strategic aims.
Volkswagen Group CFO and COO Arno Antlitz stated that the firm’s sturdy economic situation must permit it to “continue on investing in electrification and digitalization” even in a “challenging financial setting.”
“We have desire fees rising and the total desire is marginally coming down from a purchaser standpoint, from a market place perspective, but on the other hand we are even now operating in an environment, in an financial state, that is characterized by [semiconductor] source that is still not sufficient,” Antlitz instructed CNBC on Tuesday, including that this international shortage of semiconductors is easing.
“Centered on that, we have an get e-book which is virtually 1.8 million autos. Dependent on our sturdy items, sturdy brand names and that get book, we are somewhat confident for 2023.”
Web hard cash flow in the automotive division greater to 43 billion euros by the conclusion of 2022, fueled by the thriving IPO of luxurious brand name Porsche, which reported document earnings on Monday and issued an formidable lengthy-time period outlook.
The downtown Nashville landscape carries on to evolve.
The hottest adjust saw Beaman Automotive move away from Broadway more than the weekend just after decades at the acquainted internet site just off the interstate.
Beaman Toyota is shifting about 9 miles south and the Beaman Buick GMC is shifting about 13 miles south into the Antioch place. Nelson Mazda previously occupied the Mt. Look at Street area. Officers with South Carolina-dependent Hudson Automotive Team, owner of the Beaman dealerships, reported both of those locations are larger and signify an $82 million investment decision.
“With Nashville’s enlargement and progress toward Murfreesboro, these places offer you terrific visibility and the larger footprint we needed to thrive,” said Hudson CEO David Hudson.
Hudson stated the Broadway locale faced place constraints that ended up “stifling.”
Why go?
Brentwood-based mostly GBT Realty acquired the Broadway assets in late 2021, about a year just after Hudson acquired Beaman.
Hudson observed that the two new dealership destinations are larger sized and will, as a result, have much more collection. The firm states that absolutely nothing has adjusted or will transform other than the site.
On purchasing Beaman in 2020, Hudson said, “Part of our company’s method when producing a order is to seem for corporations that are now functioning perfectly, and when a manufacturer is now trustworthy in the group, there is little cause to modify it.”
What’s transferring?
The Toyota and Buick-GMC functions are shifting as properly as the Beaman Automotive Collision Middle, now at 1000 Hawkins St. in Nashville. The collision center’s new residence is an present Beaman elements warehouse at 620 Crutcher Avenue in downtown Nashville.
The Beaman Chrysler Dodge Jeep Ram and Ford dealerships at this time found in Murfreesboro and Dickson will not be moving.
How’s stock staying moved?
Automobile inventory on the Broadway heaps was scheduled to be moved by employees and not by automobile haulers. Ahead of the weekend, there had been additional than 300 automobiles on the Toyota ton and about 200 on the Buick-GMC whole lot. All of people automobiles have been intended to shift to the new dealership places prior to the dealerships’ Monday opening dates, officers explained.
Hudson owns 49 dealerships in 8 states, with destinations in Tennessee, Kentucky, Ohio, Ga, Alabama, Louisiana, North Carolina and South Carolina. In 2022, throughout all of Hudson’s 49 dealerships, more than 77,000 new and applied autos ended up marketed – with 6,500 of individuals being bought in just the two Beaman dealerships. The enterprise anticipates even increased product sales in 2023, due to the fact the transfer will make it possible for improved stock.
A car or truck hauler carrying Chrysler Pacificas’ strategies the Ambassador Bridge that connects Windsor, Canada, to Detroit, Michigan,on Oct 5, 2018 in Windsor, Ontario, Canada.
AFP by way of Getty Visuals
hide caption
toggle caption
AFP by means of Getty Pictures
A car hauler carrying Chrysler Pacificas’ methods the Ambassador Bridge that connects Windsor, Canada, to Detroit, Michigan,on Oct 5, 2018 in Windsor, Ontario, Canada.
AFP through Getty Photos
When most people today consider of Canada, they rarely imagine of cars. But the state, recognized for hockey, maple syrup and limitless wilderness, is one particular of the premier car producers in North The usa. And with the rising great importance of electrical vehicles, Canada hopes to breathe new everyday living into its automotive sector and keep a a lot more than 100-12 months-outdated custom.
Canada’s automotive marketplace is largely positioned in Ontario and Quebec, with Windsor, Ontario, claiming the title of Canada’s automotive funds.
“We’ve been the car money of Canada given that about 1904, when the to start with automobile plant opened in Canada,” mentioned Windsor Mayor Drew Dilkins.
Windsor, just across the river from Detroit, has benefited from its proximity to the United States and the 3 major carmakers headquartered there.
Stellantis, formerly Fiat Chrysler, and South Korean battery maker LG Energy Options (LGES) announced past 12 months that they will commit extra than 5 billion Canadian dollars ($3.5 billion) in setting up a new huge-scale battery production plant in Windsor. The plant is expected to be operational by 2024 and will create an approximated 2,500 positions.
“It truly is a enormous, match-changing financial commitment, and I am not even guaranteed these two words and phrases are major ample to explain how essential it is for our local community,” Dilkins says. “This will have a generational influence. [Companies] will look at the new environment of automotive and will start wanting at Windsor Essex as a spot to do organization.
Financial investment by Stellantis and LGES is element of a greater trend that has seen far more than CA$17 billion in introduced investment in Ontario’s automotive sector considering that the commencing of 2021.
“Ontario has experienced the biggest new expenditure in motor vehicle output in its background about the earlier two decades,” says Flavio Volpe, president of the Canadian Auto Areas Manufacturers’ Affiliation.
Most of this expenditure, truly worth nearly CA$13 billion, is in electrical and battery generation. And by passing the Inflation Reduction Act, U.S. lawmakers have specified Canada a additional enhance to its EV ambitions.
The regulation involves tax credits for EV purchasers, but only if the car or truck is mainly designed and assembled in North The us, and its battery takes advantage of locally mined elements. In accordance to GM Canada’s David Paterson, this could give Canada an gain around the U.S. and Mexico.
Typical Motor’s Canadian Technical Center at Oshawa is a car progress facility in Ontario, Canada.
HJ Mai/NPR
conceal caption
toggle caption
HJ Mai/NPR
Basic Motor’s Canadian Complex Center at Oshawa is a motor vehicle progress facility in Ontario, Canada.
HJ Mai/NPR
“What goes into our [sic] batteries are cathode lively products, which are generally built of nickel and other vital minerals that we come about to have in abundance here in Canada,” he says.
“As we see considerably less need for gasoline, we see far more need for minerals, and Canada is an economic climate designed on organic assets.”
In an exertion to really encourage the shift in the vehicle field toward battery-driven EVs, Canada’s federal federal government together with Ontario’s provincial govt have been investing billions of pounds.
“Our incentive is that you have a work for the reason that we invest about $2.5 billion in taxpayer income in these [car companies,” says Vic Fedeli, Ontario’s Minister of Economic Development, Job Creation and Trade.
The recent investment streak is a welcome sign for an industry that has gone through many ups and downs. Increased automation and competition from lower-wage regions have led to plant closures and job losses over the past two decades.
“We have been coming from a whole generation since about 2000, watching this critical sector decline. We have seen disinvestment in the sector, we have seen job losses in the sector, we have seen plants closed and communities are basically disappearing,” says Angelo DiCaro, research director for Unifor, a union representing about 230,000 Canadian auto workers.
The North American Free Trade Agreement, or NAFTA for short, contributed to this downturn as car companies moved their assembly lines to places like Mexico or the U.S. Southeast to cut costs. The USMAC, which replaced NAFTA in 2020, has somewhat leveled the playing field by boosting regional content requirements and instituting a minimum wage of at least $16 an hour.
DiCaro says that despite the uncertainty surrounding certain jobs that could be lost in this transition to electric vehicles, Canada’s auto workers have a sense of optimism and hope.
According to government data, the auto sector plays a key role in Canada’s economy, contributing CA$16 billion to its gross domestic product (GDP). With nearly 500,000 direct or indirect jobs, automotive is one of the country’s largest manufacturing sectors and one of its largest export industries.
Volkswagen and Tesla are two companies that have publicly stated they are actively looking at Canada as a potential site for a new battery and / or assembly plant. They would join Ford, General Motors, Honda, Stellantis and Toyota, which already have production facilities in Ontario.
“The success of the [Ontario] governing administration and the federal government [sic] will not be described by what we have landed at the moment. It will be irrespective of whether we can lend a sixth automaker or a seventh,” Flavio Volpe suggests. “It will suggest that our vision was deserving of the rhetoric and persuade the ideal automakers in the earth that the upcoming runs through Ontario.”
The global automotive cybersecurity market size is expected to be worth around USD 16.43 billion by 2032, and it is registering at a CAGR of 18.15{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from 2023 to 2032.
Ottawa, March 11, 2023 (GLOBE NEWSWIRE) — As per Precedence Research, the global automotive cybersecurity market size was valued at USD 3.1 billion in 2022. The most recent developments in connected and autonomous vehicles, as well as the rising number of electronic control units (ECUs) in electric vehicles, are driving the expansion of the automotive cybersecurity industry. Due to new manufacturing techniques and consumer-challenging technology, the automotive industry is facing a rapid revolution in cyber security that is being fueled by socioeconomic and environmental changes.
Report Highlights:
Asia Pacific region has accounted revenue share of 37{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2022.
By vehicle type, the electric vehicle (EV) segment is poised to grow at a CAGR of 29{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} between 2023 to 2032.
By security type, the wireless network security segment has generated revenue share of 43{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2022.
By security type, the application security has held revenue share of 35{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2022.
By application, the infotainment segment has contributed revenue share of 37{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2022.
By application, the ADAS & safety system segment is growing at a notable CAGR of 22{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from 2023 to 2032.
Cybersecurity is the defence against malicious assaults, damage, unauthorized access, and manipulation of automobile electronic systems, communication networks, control algorithms, software, users, and underlying data. The market for automotive cybersecurity is expanding as a result of rising demand for automotive cybersecurity solutions brought on by a rise in cyberattacks on the car industry. Cybercrime is on the rise, and it is anticipated that customer comprehension of information security will result in lucrative business opportunities. As a result, owners and organisations are urged to put automotive cybersecurity safeguards in place, which is what propels the sector.
The development of connected cars and the enforcement of vehicle data security regulations by regulatory bodies are expected to fuel further market expansion.
Regional Insights
Asia Pacific held 37{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of the market in 2022 and is anticipated to continue expanding over the course of the forecast period. The number of cyberattacks has been rising steadily across APAC. Yet, a lack of security measures and the rising popularity of work-from-home policies have led to a rapid increase in cyberattacks. The two most prevalent kinds of cyberattacks are malware and ransomware assaults. The number of malware and ransomware attacks in APAC nations is still 1.6 times greater than worldwide. During 2018, ransomware assaults have increased in frequency across the globe. Cyberattacks on the auto industry have become more frequent as connected cars and digitization have proliferated. These attacks target the car and compromise crucial vehicle data, causing owners to incur significant losses.
Based on vehicle type,commercial vehicles, personal vehicles, and electric vehicles can all be classified as segments of the market (EV). The EV category dominated the market in 2022 and is expected to grow in the near future. The market has grown as a result of more people becoming aware of economic development and the downsides of operating hybrid automobiles. In addition, a few of municipal governments are providing subsidies to encourage the purchase of electric cars in anticipation of greater infrastructure development.
Based on security insights, security for endpoints, applications, and wireless networks are the market segments. With a majority of the market share in 2022, wireless network security dominated the market. During test runs, the Wi-Fi-based wireless technology enables automotive professionals to concurrently monitor hundreds of data channels to track vehicle operational parameters and modify the test as it is being carried out. A modern vehicle incorporates numerous information-sharing networks, including wireless channels, to enable a variety of application scenarios.
Based on application, ADAS & safety system, infotainment, body electronics, powertrain, and telematics are the several market segments for car cyber security. With a highest market share the infotainment section was the market leader. Throughout the forecast period, this segment is anticipated to increase significantly.
The whole automotive industry is working to develop cutting-edge technology to give better connectivity options, increase vehicle safety, and enhance the in-car user experience. The “In-Vehicle Infotainment System” is one of the key technologies that serves as the focal point of all modern automobile systems, integrating their operations so they can be managed and monitored from a single central unit.
Based on form, in 2022 the in-vehicle sector dominated the market. In-car-connected services are technologies that make it possible to connect internal vehicle systems to those found in remote locations or external systems. The modern vehicle’s most connected component due to its mobile connectivity. Car Makers have had to adjust to changing consumer demands, which has resulted in ever-more-advanced technologies.
Also, external cloud services are growing at the fastest rate due to improvements in cloud infrastructure and framework. Cloud services offer a very dependable technology, especially given the volume of data produced by driverless vehicles. Moreover, cloud technology will lead to a faster rate of information transfer as the number of cars and devices connected to the cloud rises.
Market Dynamics
Driver
Increase in need for automotive cybersecurity
The rising connectedness of vehicles to everything, including traffic signals, parking metres, other vehicles, and much more, is altering the automotive industry. The employment of new technologies is prevalent, with electrified vehicles, shared mobility, self-driving cars, and advanced driver assistance systems (ADAS) among them (EV). These technologies not only increase comfort and safety on the roads, but they also leave this complex and dynamic environment vulnerable to intrusions. As the ecosystem becomes increasingly integrated, attack points increase, exposing new vulnerabilities that hackers might employ to jeopardise user privacy, car safety, and the integrity of automotive data. The Upstream Security Automotive Cybersecurity Report 2020, produced by an Israeli cybersecurity business, provided in-depth analyses and statistics based on an examination of 633 events that were widely reported since 2010, of which 207 occurred in 2019.
Restraint
Growing diversity in the automotive domain along with the rising complexity of the security software
Due to the large range of automobile types and the numerous applications that can operate within a car, the automotive industry is growing more and more diverse. The variety and complexity of automotive cyber security systems increase as there are more manufacturers of automotive solutions. The market’s growth will be constrained by the inescapable rise in installation and maintenance costs for vehicle cyber security systems as complexity develops.
Opportunity
Enhancing vehicle security using adaptive security
Adaptive security is a type of cybersecurity system that looks at events and actions to stop and prepare for threats before they happen. A business can utilise an adaptive security architecture to provide proportional enforcement that can be increased or decreased while continuously analysing risk. With adaptive security, which many automobiles manufacturers lack throughout their operations, it is simple to defend a dispersed workforce.
Adaptive security uses analytics and automation to protect against targeted and opportunistic cyberattacks, as well as trusted insiders and other insider threats. Adaptive security also safeguards an automaker’s ecosystem, which is growing every day as a result of connected car activities. Hence, it is anticipated that an increase in adaptive security in the automotive industry will fuel growth of the global automotive cybersecurity market during the forecast period.
Challenge
Discrepancies related to pricing strategies among stakeholders
Due to the introduction of ancillary services like multimedia streaming Ecalls and remote diagnostics within connected cars, the entire ecology of the automotive industry is changing. The automobile ecosystem has evolved from being fixed to being dynamic, with each actor accounting for a portion of the revenue. The linked ecosystem’s pricing model has proven challenging to implement due to the presence of various players. With different pricing strategies, many firms struggle to strike a balance between complexity and expense. Currently, software companies utilise a variety of pricing models to make money. Experts in the area claim that cybersecurity solution providers struggle to implement the night pricing plan to boost profitability and decrease missed chances in a range of circumstances.
Recent Developments
In July 2021, in its EVlink line of electric vehicle charging stations, Schneider Electric fixed security issues that may have allowed DoS attacks.
In August 2021, Upstream, an automobile firm, raised $62 million in a Series C round to increase the scope of its cloud-based security offerings.
You can place an order or ask any questions, please feel free to contact at sales@precedenceresearch.com | +1 9197 992 333
About Us
Precedence Research is a worldwide market research and consulting organization. We give unmatched nature of offering to our customers present all around the globe across industry verticals. Precedence Research has expertise in giving deep-dive market insight along with market intelligence to our customers spread crosswise over various undertakings. We are obliged to serve our different client base present over the enterprises of medicinal services, healthcare, innovation, next-gen technologies, semi-conductors, chemicals, automotive, and aerospace & defense, among different ventures present globally.
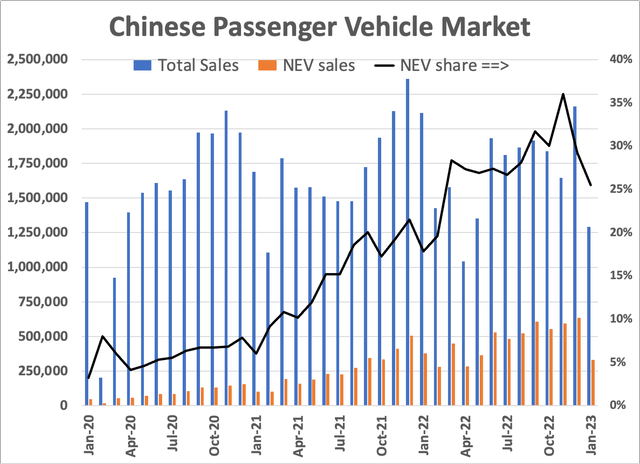
The sales year started off with a whimper. First, the covid stimulus package for the auto industry – a cut from June 1-Dec 31 of the car sales tax from 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} – expired. Those planning to buy cars in early 2023 instead made their purchases last year. In addition, the Chinese central government has been winding down its incentives for New Energy Vehicles (NEVs) for several years. They, too, expired at the end of 2022. That pulled planned NEV sales from 2023 into 2022, over and above the impact of the covid tax cut. In other words, electric vehicle (“EV”) sales in late 2022 were artificially high. This year will be grim across the board for the China automotive sector.
Local government incentives aren’t picking up the slack. Beijing has capped its 2023 NEV license plate incentives at the 2022 level of 70K units, while for 2023 Shanghai eliminated free license plates for PHEVs (and refuses to license urban commuter EVs such as the GM Wuling Hongguang Mini). Now Hunan has begun a 元5000 cash-for-clunkers subsidy, and the central government is urging local governments to upgrade their fleets from ICEs to EVs. However, more prosperous localities such as Shenzhen have already completed the switchover to EV taxis and buses. Most regional and lower-tier cities face a budget crunch, so the process will be slow and will focus on low-priced vehicles. That’s bad news for the many NEV startups, and for Tesla, Inc. (NASDAQ:TSLA) which sit in the premium segment.
Analysis is complicated by the Chinese [lunar] New Year holiday in late January. China is now an urban society, but its cities are populated by workers who migrated from rural areas. This year, around 250 million people traveled back to their hometowns. Car dealerships were closed, and those that reopened early remained empty. Of course, the government offices that issue license plates were closed, too.
To reiterate, it’s payback time. January sales fell 35{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} overall, and 28{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} for battery EVs (“BEVs”). However, as I outline below, February sales looked good only in comparison to January. That is bad news for Tesla, which will face lower margins and higher costs, due to lower capacity utilization and the delayed feed-through of higher commodity prices. It is worse news for the many startups, which will see poor sales from now until the normal cyclical increase that starts in September. NEVs are also facing pricing pressures, due to the multitude of players and spearheaded by Tesla’s price cuts.
Additional months of negative cash flow are very bad news. Already, Weltmeister (not traded) has effectively gone out of business, selling no cars this year and closing most of its remaining facilities last week. In their latest financial statements, available on Seeking Alpha, operating income remained negative for Li Auto, Inc. (LI) [Dec 2022], XPeng Inc. (XPEV) [Sep 2022], and NIO Inc. (NIO) [Dec 2022]. Sales of other entrants – Neta, Zeekr and others (not traded) – remain at very low levels. Again, BYD is an exception, as is GAC with its Aion brand. Both are profitable (or are part of larger, profitable enterprises), and so face no immediate pressures. They (alongside Tesla) also happen to be the two largest and best-performing NEV players.
Below I look at overall passenger vehicle sales, and then turn to NEVs. Going into 2023 Chinese analysts were already looking at lower growth, of the order of 30{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. I believe that is optimistic in terms of unit sales, and will represent minimal growth in 2023 for revenue and a negative for cash flow. I don’t attempt projections, since there are many articles on Seeking Alpha to provide a baseline. My last section focuses on Tesla, reiterating my January 2022 SA article projecting that Model 3 sales would decline.
Note that my core datasets are for retail sales of light passenger vehicles, but do not include imports. They also do not cover light commercial vehicles or buses, and are not wholesale shipments so ignore exports.
Payback: Overall Vehicle Sales
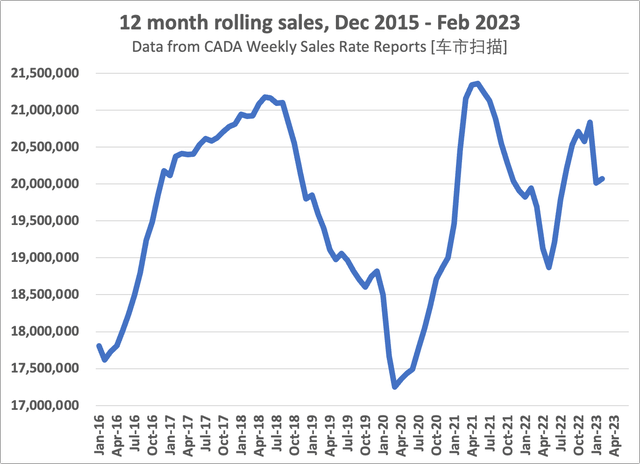
First, China remains the largest vehicle market, surpassing both Europe and North America. But it’s not growing. The migration for towns and farms to cities has ceased, consumers are under pressure as growth remains slow and real estate prices continue to fall, and the working-age population has been falling for a decade. Sales peaked in 2017, and will not expand going forward.
Author’s database, compiled from China Auto Dealers Assoc reports
What are the prospects for CY2023? The government is hoping for 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} growth, but is looking to achieve that through pushing banks to lend for infrastructure and real estate investment. To use a monetary policy aphorism, that’s pushing on a wet string. Local governments saw their fiscal position deteriorate the past two years, and now have bills to pay for the covid testing mandated (but not paid for) by the central government under last year’s rolling lockdowns.
I spent most of my career as a specialist on Japan’s economy, and was in Tokyo in 1992 when their real estate bubble burst, and worked for a Japanese bank before graduate school. I’ve spent days in seminars looking at the evergreening of bad real estate loans, and how that undermined the effectiveness of macro policy. China is going down the same route, in part because that’s the only policy tool Beijing has, given the already complete buildout of regional airports, high speed rail and, lest we forget, a national expressway system that is more extensive than those of the U.S. or Europe – and doesn’t yet need maintenance.
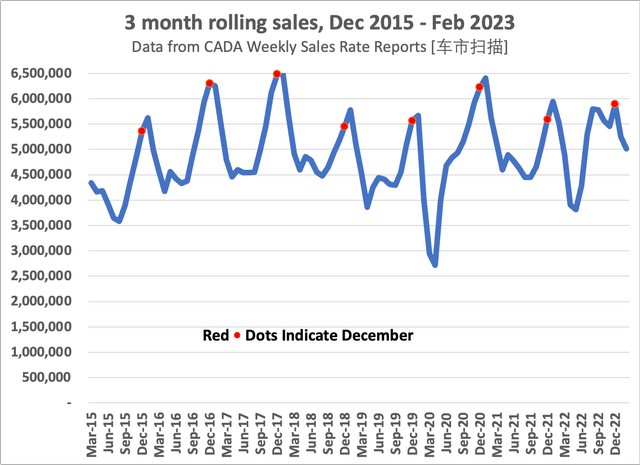
Let’s return to automotive, and look in more detail at passenger vehicle sales. The graph below provides sales using a 3-month moving average. To help with interpretation, December each year is marked with a red dot. First, sales show a distinct seasonal pattern, peaking at the end of winter, in January when the New Year falls later in February, and otherwise (as this winter) in December. Sales then fall through August, in some years with a June bump, before beginning their annual fall ascent.
However, 2022 was different from the previous 7 years, with the rolling average showing an early August peak. That difference represents roughly 700,000 extra sales, sales that will not be booked in the first half of 2023. Compared to recent years, that suggests that sales through July will be down 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, assuming that consumers will be spending as normal. The Chinese government doesn’t believe that will be the case, accepting lower growth and instead focusing on financial system stability. (See, amongst many possible examples, “Caixin Global, Mar 8, 2023: China’s Financial Shake-Up Shows Policymakers’ Growing Focus on Stability, Risk.”) For the sake of brevity, I won’t examine other indicators, such as commercial vehicle sales. All point in the same direction.
Authors database, compiled from monthly CADA reports
EV Sales
What though of NEV sales? While I otherwise ignore the differentiation, one segment was up in January, PHEV (plug-in hybrids), and by 48{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. After all, battery-only EVs don’t fit every use case, and news stories over the Chinese New Year holidays were replete with EV drivers waiting in line to plug into snow-covered chargers, as cold weather depleted their range. There weren’t many PHEV options in 2020, but then not that many EVs were sold, either. The data show the relative weight of PHEVs consistently rising, from about 1 in 8 NEVs sold in 2021Q1 to a bit over 1 in 5 in 2022Q4. That suggests an additional source of pressure on pure EV sales.
Second, the rate of diffusion of NEVs has slowed. Again, as the introduction noted, national incentives have expired and local/provincial ones haven’t increased. Historically, Shanghai has been the single biggest market; altogether, the top 10 cities account for over 1 in 3 NEVs sold (source: my compilation of monthly CPCA reports). Those markets are becoming saturated, with 40{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of sales now NEVs. They are also the wealthiest cities, and so are buying the higher-priced vehicles that NEV makers must sell to be profitable. Expanding sales requires moving into Tier 3-4 cities, but those have lower incomes, are losing populations, have governments that are in fiscal straits, and face the largest real estate losses. The latter are the dominant form of household savings, and in a down market are illiquid. (For more details on real estate, see Kenneth Rogoff and Yuanchen Yang, “A Tale of Tier 3 Cities.” IMF Working Paper 22/196, September 2022.)
Authors database, drawn from icauto.com.cn and other sources
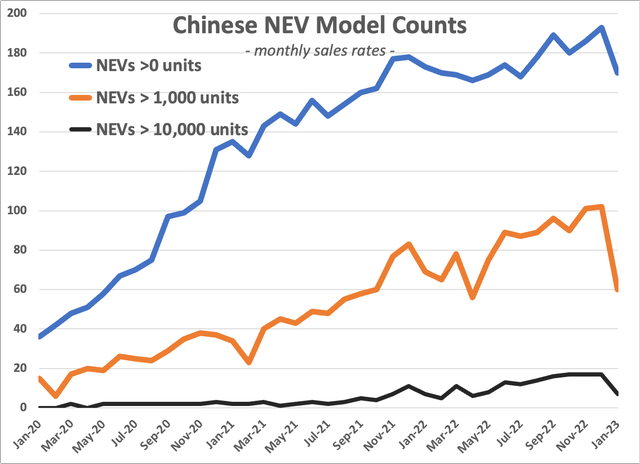
Third, there’s a price war going on. While that’s potentially good for sales volumes, it’s bad for everyone in the industry. Unfortunately for both firms and investors, competition is fierce. I track new model announcements. In 2022, my data include 232 new models and full model changes (and another 466 facelifts and minor changes). Of the new models, 70 were EVs and another 31 PHEVs. This year will see far more, with IHS anticipating 180 new EVs and PHEVs.
Authors database, drawn from icauto.com.cn and other sources
Over the course of 2023, the market will thus become more fragmented, even if some firms exit and some go out of production (as reflected in the blue line of counts of models in my database in the above graph). This should help offset the overall slowdown, as consumers will be more likely to find a model that hits their sweet spot, but it won’t help pricing. At the firm level, the net impact will depend on how many of these are new “top hats” to existing platforms that will come off an existing assembly line. For firms successfully employing a platform strategy, that will increase capacity utilization and economies of scale in component sourcing, even as it decreases sales for each individual model. Whether that will increase net profits (or slow losses) will depend on how much prices deteriorate. I don’t have access to such detailed data, nor do I have the full-time research assistant needed to pull it all together. The only analyst who seems to dive into that level of detail is Eunice Lee at Bernstein, but I have no funds invested with them so no access to those reports, which in any case I wouldn’t be able to cite.
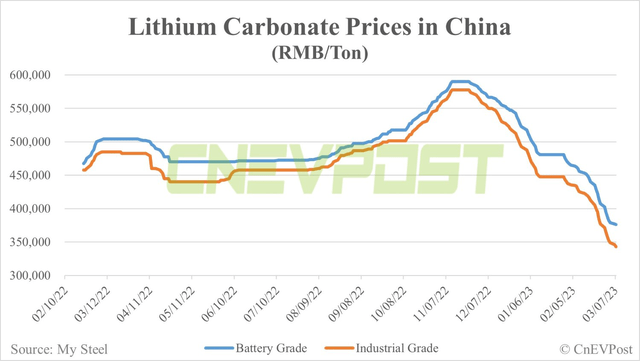
Finally, to me the most sobering item is the 50{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} fall of lithium carbonate prices since December 2022. It’s not because of a large new mine entering production, or new refining capacity. Carmakers overestimated the end-of-year sales surge of consumers rushing to buy before incentives rolled off (see here), and started paring production plans. They similar underestimated the payback of lower sales in January and particularly February. Why? – because the underlying demand for BEVs is proving below consensus.
CnEVPost
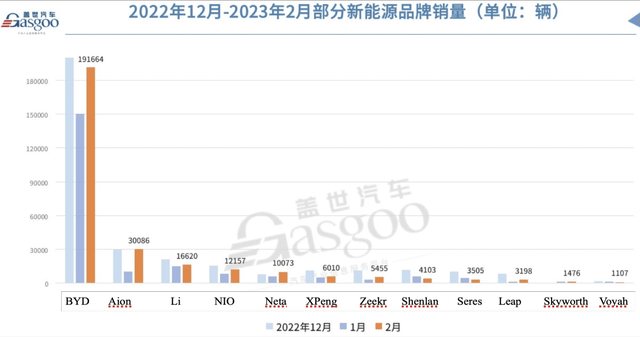
Let’s look at the performance in the major non-Tesla brands (Tesla couldn’t be included because they are slow to release domestic retail data). What the following graph illustrates is nothing short of disaster, because February sales failed in bounce back from the January holiday doldrums. The new entrants need growth to survive. Only 2 firms managed to beat December sales levels: the Guangzhou Automobile Group Co., Ltd. (GNZUF) (“GAC”) Aion brand, whose 4 models racked up sales of 270,000 units in 2022, and the small Neta (also called Hozon in some sources), with 3 models (one launched in November) and 2022 sales of 151,000. I am watching GAC, which is profitable, pays a dividend, and is trading at half of peak. Unfortunately there is no recent analysis on SA, and this article will not attempt to remedy that. Overall, though, I do not believe any of the new entrants in the graph provide “long” investment cases.
Gasgoo web site
Source: auto.gasgoo.com, to which the author appended English company names.
Tesla China
Will Tesla prove robust to these headwinds? How they fare in China in 2023 is central to their growth story and their profitability. The stock price depends on keeping both those narratives intact. Shanghai is Tesla’s largest production facility, so keeping capacity utilization high will be important to controlling costs and preserving margins. Ditto maintaining pricing.
Until we have data for 2023Q1, we will not know whether Tesla has at last dropped its pattern of end-of-quarter retail surges. Changing that habit would mean fewer exports early in a quarter and more later on, and so would leave Europe short of product, leading to a transitional quarter of poor sales. Likewise, in China operations would have to push for more sales early in the month. My own sense of organizational inertia is that such a shift could not be implemented in the space of a month or two, so again would lead to poor sales figures for the transitional quarter. I believe that Tesla management will weigh the gains in operational efficiency against the damage to the growth narrative, and choose the status quo.
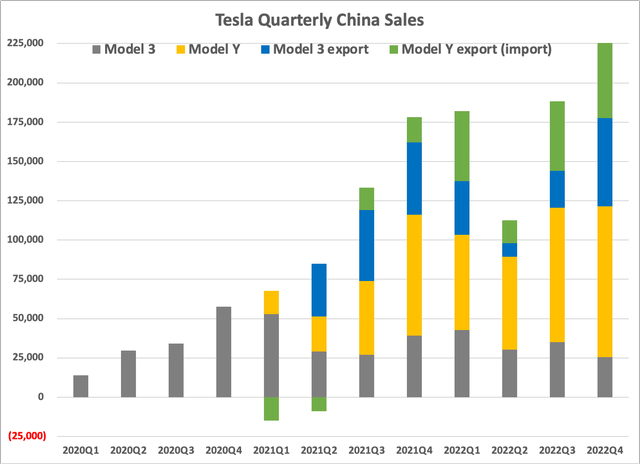
That proviso aside, the data show several things.
One is Tesla’s inability to grow domestic sales of the Model 3, which in fact peaked in 2020Q4. Absent a refreshed interior and new sheet metal to update styling, sales will continue to fall under the onslaught of new models in 2023.
The second is the success of the Model Y, which sells far better than the Model 3 ever has. With a higher selling price but non-battery production costs similar to the Model 3, it is central to Tesla’s profitability.
The third is the dependence of Shanghai on exports, which since 2021Q2 have accounted for over a third of output (2022Q2 was an exception). Without the ability to sell into the European market, Shanghai would operate at under 70{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of capacity. Lower labor costs and component costs imply that fixed costs are a higher share. Ironically, that raises Shanghai’s breakeven point. (Thanks to Glenn Mercer for this point.)
Authors database, compiled from multiple underlying sources
All of this raises a number of questions.
First, as Berlin ramps up, how will Shanghai keep utilization high? No other export markets (think Australia) are big enough to absorb the excess, but preliminary data for February show domestic sales below November and December 2022, while exports were over 50{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of wholesale shipments (source: CnEVPost: Tesla delivers 33,923 … exports 40,479). I follow China, not Europe, so will lean on comments in the discussion to flesh out scenarios.
Second, Reuters reported on March 1 that Tesla will start producing a refreshed Model 3 – some new sheet metal, a modified interior – in September. However, as I argued previously on SA, the Model 3 is not in a particularly attractive segment, though sedans continue to do better in China than in North America. This should certainly stop the slide in sales, but I do not believe it will offset the limitations of the segment. Furthermore, we have no confirmation from Tesla, and every reason to believe they will miss the target date. Additionally, what will Tesla do to maintain sales of the old version after the new one has its public reveal, while will be before it is actually available for sale? Model changeovers are generally accompanied by price reductions, which with September as the date would hit both the top and bottom line in 2023Q2. Given a long history of delays, however, it’s more likely that this is a story for 2024, not this year.
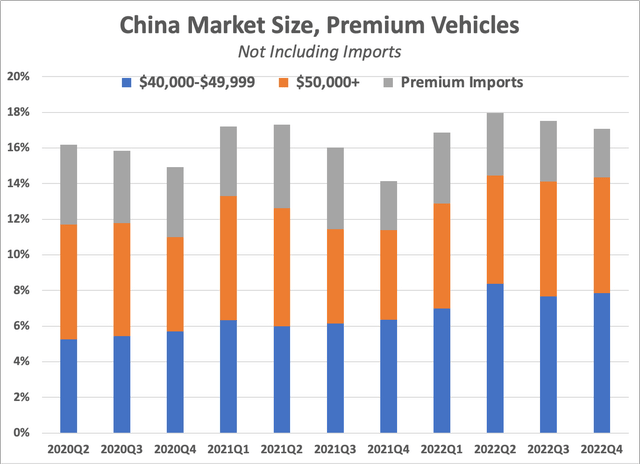
Third, will sales of the Model Y hold up? That single model is now the dominant product for Tesla in China, but it is also a stupendous cash cow, maintaining enviable volume even though it is entering its third year in the Chinese market. My sense is that there is no upside potential. Unlike the U.S., in China the share of the premium market is not expanding, and the dozen or so large, high-income cities that account for most Model Y sales are becoming saturated. Lower lithium prices will support discounting across the NEV spectrum, so will not necessarily help the Model Y. It will however allow premium EV makers with their larger batteries to lower prices more than carmakers operating in lower price brackets. With higher production volumes, and tooling costs now written off, Tesla has more room to discount than new entrants with lower volumes and brand new factories and tooling. So, I also see little downside in volume terms.
Authors database, compiled from various Chinese sources
Conclusions
There are many uncertainties going into 2023. I expect the first half of the year to see much slower growth for NEVs amidst an onslaught of new product. Sales will improve only in 2023Q4, with the normal seasonal upturn, resumed albeit slow economic growth, and lower NEV prices. New entrants in automotive face high hurdles, and I expect another one or two of the smaller NEV players to exit by year’s end, and stillbirths among those just launching their initial products. Watch for additional Chinese EV IPOs – and avoid!
Among the incumbents, GAC remains interesting, with its Aion NEV. Geely Automobile Holdings Limited (OTCPK:GELYF) has about 300,000 in NEV sales, but those are spread across multiple brands and models and corporate entities. That impedes achieving scale in production, and lowers the efficiency of its platform sharing. They nevertheless remain better than other incumbents such as Great Wall, SAIC, VW, GM, Toyota, Honda, Hyundai/Kia, FAW, Dongfeng, Changan, Chery – and on and on. China remains the world’s biggest automotive market, the biggest automotive producer, and is now a net exporter in volume terms. It is also a mature market, and that lowers its attractiveness for investors. Actions speak louder than words: I have yet to take the plunge.
Tesla remains highly profitable in its China operations, but 2023 will be challenging for the Chinese industry as a whole, and Tesla will not be exempt from those pressures. Tesla increasingly depends upon sales of a single product, the Model Y, as the Model 3 is past its prime. The Model Y continues to sell well, and is in a good segment, mid-sized SUVs. However, the premium segment is not expanding, and the steady stream of new NEV models will pressure margins for all producers. Factors such as falling lithium prices help everyone, and with competition, ultimately benefit no one (other, that is, than the final consumer).
In addition, the cash cow of Tesla Shanghai faces a major risk, its reliance on exports to Europe. No other new export markets are large enough to offset any decline there. If Tesla does launch a refreshed Model 3, it will be late in the year so the impact will be in 2024. Meanwhile, while the Cybertruck will launch in the U.S. in late 2023, it is a non-starter in China, where pickups remain utilitarian work trucks that sell in modest numbers in rural areas, and not in the major, high-income cities that comprise Tesla’s core market. Newer, less expensive models are years away and will carry smaller margins multiplied by lower prices.
In sum, Tesla has less downside than the many small players in the NEV market. In line with the NEV market as a whole, Tesla did well in 2022. It’s now payback time, and in line with the NEV market as a whole, Tesla also faces little upside in 2023. That is bad news for a growth stock.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Wholesale used-vehicle prices (on a mix, mileage, and seasonally adjusted basis) increased 4.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in February from January. This was the largest increase for the full month of February since 2009’s 4.4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} rise. The Manheim Used Vehicle Value Index (MUVVI) rose to 234.5, down 7.0{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from a year ago. February’s increase was driven partially by the seasonal adjustment. The non-adjusted price change in February was an increase of 3.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} compared to January, moving the unadjusted average price down 5.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} year over year.
In February, Manheim Market Report (MMR) values saw increases that were not typical, culminating in a 2.4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} increase in the Three-Year-Old Index over the last four weeks. Over the month of February, daily MMR Retention, which is the average difference in price relative to the current MMR, averaged 100.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, meaning market prices were very close to MMR values. The average daily sales conversion rate increased to 64.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and was above normal for the time of year. For example, the daily sales conversion rate averaged 55.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in January 2019. The higher conversion rate indicated that the month saw sellers with more pricing power than what is typically seen for this time of year.
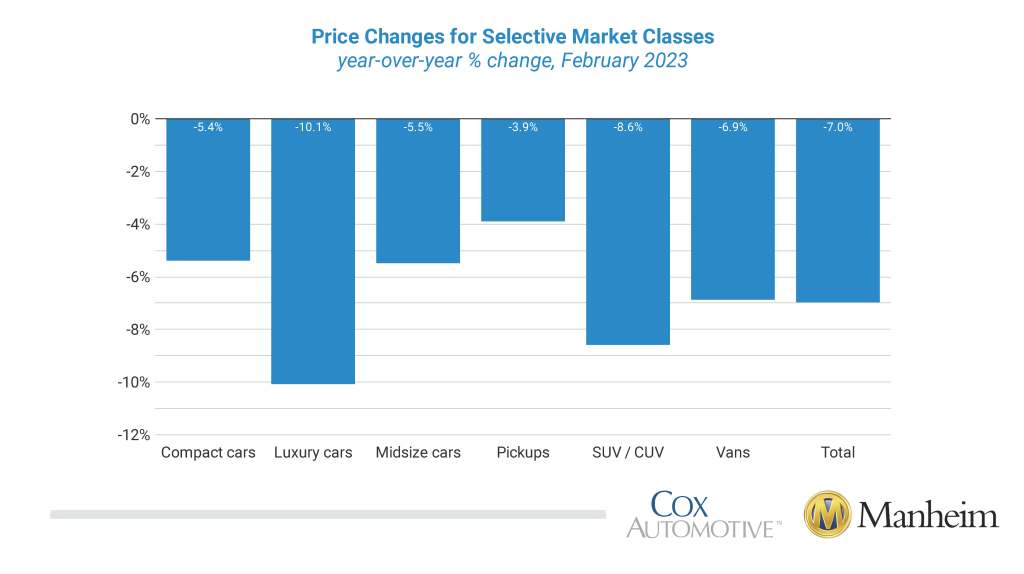
All eight major market segments continued to see seasonally adjusted prices that were lower year over year in February. Pickups had the smallest decline at 3.9{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, with compact cars, midsize cars, and vans losing less than the overall industry year over year. Luxury cars, SUVs, and sports cars lost 10.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, 8.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, and 7.4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, respectively, compared to last February. All eight major segments saw significant price increases compared to January, with gains of between 3.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and 5.9{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.
Used Retail Vehicle Sales Declined in February
Leveraging a same-store set of dealerships selected to represent the country from Dealertrack, we initially estimate that used retail sales declined 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in February from January and that used retail sales were down 9{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} year over year.
Using estimates of used retail days’ supply based on vAuto data, an initial analysis indicates February ended near 41 days’ supply, down from 48 days at the end of January and 13 days lower than how February 2022 ended at 54 days. Leveraging Manheim sales and inventory data, wholesale supply is estimated to have finished February at 24 days, down two days from the end of January and down five days from how February 2022 ended at 29 days.
February’s total new-light-vehicle sales were up 8.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} year over year, with the same number of selling days as February 2022. By volume, February new-vehicle sales were up 9.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from January. The February sales pace, or seasonally adjusted annual rate (SAAR), came in at 14.9 million, an 8.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} increase from last year’s 13.7 million but down 6.2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from January’s revised 15.9 million pace.
Combined sales into large rental, commercial, and government fleets increased 48{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} year over year in February. Sales into rental fleets were up 77{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} year over year, sales into commercial fleets were up 23{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, and sales into government fleets were up 42{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. Including an estimate for fleet deliveries into dealer and manufacturer channels, the remaining retail sales were estimated to be up 4.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, leading to an estimated retail SAAR of 12.3 million, up 0.5 million from last year’s pace but down 0.9 million from last month’s pace. The fleet market share of 17.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} was a 3.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} gain compared to last year’s share of 14.2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and was a 1.2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} increase from last month’s estimated 16.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} market share.
Rental Risk Prices and Mileage Rise Substantially in February
The average price for rental risk units sold at auction in February was up 0.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} year over year. Rental risk prices were up 5.0{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} compared to January. Average mileage for rental risk units in February (at 60,700 miles) was up 2.4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} compared to a year ago and up 8.8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from January.
Measures of Consumer Confidence Mixed in February
The Conference Board Consumer Confidence Index® declined 2.9{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in February, as views of present situation improved but future expectations fell by 8.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. Plans to purchase a vehicle in the next six months fell to the lowest level since November 2021. The confidence index did not decline as much during the pandemic as the sentiment index from the University of Michigan, but that series has improved every month this year. The Michigan index increased 3.2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in February and was up 6.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} year over year. Consumers’ views of buying conditions for vehicles declined modestly in February but remained much better than a year ago. The daily index of consumer sentiment from Morning Consult measured improving sentiment in February following a slight decline in January. That index increased 3.2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in February as the price of gasoline declined. According to AAA, the national average price for unleaded gas fell 4.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in February to $3.36 per gallon on Feb. 28, down 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} year over year.
The complete suite of monthly MUVVI data for March will be released on April 7, 2023, the fifth business day of the month, as regularly scheduled. To hear about the latest MUVVI and trends that shaped the quarter, register to attend the Q1 Manheim Used Vehicle Value Index Call on Friday, April 7, at 11 a.m. EDT.If you are observing the Good Friday holiday, a recording of the call will be available in the Newsroom on Monday, April 10.
For questions or to request data, please email manheim.data@coxautoinc.com. If you want updates about the Manheim Used Vehicle Value Index, as well as direct invitations to the quarterly call sent to you, please sign up for our Cox Automotive newsletter and select Manheim Used Vehicle Value Index quarterly calls.
The Manheim Used Vehicle Value Index was adjusted to improve accuracy and consistency across the data set as of the January 2023 data release. The starting point for the MUVVI was adjusted from January 1995 to January 1997. The index was then recalculated with January 1997 = 100, whereas prior reports had 1995 as the baseline of 100. All monthly and yearly percent changes since January 2015 are identical. Read more about the decision to rebase the index and review the index methodology for more details.