Kyle Richards’ husband opens real estate firm in Palm Beach County

Kyle Richards’ husband opens real estate firm in Palm Beach County

Genuine Housewives star and California electric power-Real estate agent Mauricio Umansky introduced a franchise of his luxurious brokerage firm in Palm Seashore Gardens this 7 days with an eye on the area’s most opulent residences and perfectly-heeled denizens.

Umansky, who is generally featured on the “Actual Housewives of Beverly Hills” with his spouse Kyle Richards and has a Netflix collection known as “Buying Beverly Hills”, introduced Tuesday that The Agency was opening an office environment on PGA Boulevard.

Started in 2011, The Company has franchises all around the planet and in some of the wealthiest communities in the region, which includes Aspen, Cape Cod, Maui, the Hamptons and Santa Barbara. In Florida, the firm, which has a whole profits quantity of $41 billion, has opened store in Naples and Bal Harbour.

Umansky, who life in Los Angeles, mentioned the final decision to open up an business in Palm Beach Gardens was not only dependent on the migration of people today from California to Florida, but he recognizes there is an maximize in transplants.

Extra:Palm Beach’s extravagant authentic estate price ranges ooze into the restrained Town of Gulf Stream

Far more:Condominium sale sets record for shiny Bristol and West Palm Beach

Additional:The Bristol’s proprietors: Leaders, dealers and a healer

Why Kyle Richards’ partner, Mauricio Umansky of ‘Buying Beverly Hills’, chose Palm Seashore Gardens for new brokerage agency locale

Mauricio Umansky is a star on the Real Housewives of Beverly Hills and co-founder of luxury real estate firm The Agency.

“We have witnessed that migration and the good quality of everyday living and fiscal pros in Florida have certainly played a part,” Umansky claimed.

The new place of work is positioned at 2000 PGA Blvd. near the Town Centre browsing shopping mall, although a press launch continuously refers to Palm Beach front.

“We couldn’t be more psyched to continue on our strategic growth throughout South Florida with the debut of our newest office in Palm Seaside,” stated Executive Vice President of Franchise and Gross sales Jim Ramsay in a push launch. “The life style on Palm Beach front holds wonderful synergy with The Agency’s revolutionary model and philosophy.”

Though income of single-family members residences saw their most affordable quantities because 2013 final calendar year, the ultra-luxury industry is still humming, some Realtors mentioned.

‘A real estate bottom?’ More homebuyers jump back in as the year kicks off

‘A real estate bottom?’ More homebuyers jump back in as the year kicks off

Actual estate brokers validate what housing facts is starting off to show: More homebuyers are rising from their self-imposed hibernation.

The volume of home finance loan apps for household buys rose 25{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} week above week, the Mortgage Bankers Association (MBA) survey for the week ending Jan. 13 found. Housing sentiment ticked better at the end of last yr, per Fannie Mae. And property builders are reporting an raise in consumer site visitors in January, the first uptick considering that December 2021, according to an market survey.

These customers are hoping to reap the benefits from a additional favorable marketplace, bagging seller incentives alongside with a a little bit decreased home finance loan rate, right before the spring-acquiring period appeals to far more competitiveness.

“I experienced one particular of my shoppers at Meta and an additional from Microsoft who have been energetic up right until September of past calendar year access out to me final weekend,” Jeff Reynolds, a broker at Compass and founder of UrbanCondoSpaces.com, told Yahoo Finance. “They had wanted to see what the industry would do, and given that it seems to have stabilized and prices are down, they are hoping to get a phase ahead of what would inevitably be a real estate bottom.”

Home sellers are more likely to offer buyers concessions, a Redfin report found. At least 42{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of homes sold during the fourth quarter of 2022 included an incentive. (Credit: Getty Creative).

Home sellers are additional probable to provide customers concessions, a Redfin report uncovered. At the very least 42{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of households marketed throughout the fourth quarter of 2022 bundled an incentive. (Credit rating: Getty Artistic).

‘Bringing people today back in’

The dip in mortgage loan prices in latest weeks has taken some of the edge off of the document-placing ascent fees clocked in last year. Last week, the typical level on the 30-yr fixed home finance loan — the most normally made use of home financial loan for a order — settled nearer to 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} than 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, fitting into extra buyers’ budgets.

“Interest prices are greater for 1st-time consumers. I assume in a natural way it is just bringing persons back again in,” John Downs, senior vice president at Vellum House loan, advised Yahoo Finance.

At the very same time, residence prices have also softened, with the median record value falling to $400,000 in December, according to Redfin, down 11.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from June’s peak of $449,000.

“The vast majority of activity is from new customers,” Reynolds mentioned. “In our microclimate in downtown Seattle, the bulk of activity has hit really very affordable price tag details. Which is pushed primarily by that millennial consumer, that youthful consumer, or very first-time buyer eventually getting gain of market circumstances — possibly for the 1st time.”

‘Picking for deals’

The consumers who are coming again are also acquiring gutsy, recognizing that the sellers who remain in the marketplace are open to negotiation.

“In 2022, consumers set the market place by bidding up, which led to escalating charges and basically possessing to pay to earn,” Downs reported. “Now, in its place of ready for listing charges to fall, purchasers post presents with large discount rates and make the seller make a decision. And that would seem to be operating.”

At minimum 16.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of houses bought in December experienced a value lower, Realtor.com info located, an boost from 7.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} a 12 months ago. Even property builders are squishy on cost.

Just one of Monte Miner’s purchasers obtained $15,000 off a freshly created residence at first priced at $409,000, according to the real estate agent at Ironwood Fine Attributes in Arizona.

Rick Nazarro of Colonial Manor Realty talks with a pair of interested buyers in the driveway as a couple waits to enter a property he is trying to sell during an open house in Revere, MA. (Credit: Blake Nissen for The Boston Globe via Getty Images)

Rick Nazarro of Colonial Manor Realty talks with a pair of interested potential buyers in the driveway as a pair waits to enter a home he is hoping to sell throughout an open up residence in Revere, MA. (Credit: Blake Nissen for The Boston Globe by using Getty Photos)

“Buyers are coming back, but they are buying for discounts. Let’s say a property is shown for $400,000 — a good deal of the provides coming in are beneath that variety,” Miner mentioned. “Some sellers’ pricing expectations are stuck in the past, like 3 months ago. It is distinctive now.”

Not only are some people finding large rate reductions, they are also snagging vendor concessions to further relieve the stress of still-high home rates.

For instance, at the very least 35{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of builders lowered their home costs in December, facts from the Nationwide Affiliation of Homebuilders located. A further 62{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of builders ongoing to use incentives to appeal to purchasers, such as amount obtain-downs and paying out points. In accordance to Redfin, roughly 42{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of residences bought in the closing 3 months of 2022 involved a vendor concession, such as funds for repairs or closing prices.

“If you never haven’t sufficient cash for closing costs,” Downs explained, “sellers are supplying to shell out it for you,”

A sign is posted in front of new condominiums for sale on December 19, 2022 in Los Angeles, California. (Credit: Mario Tama/Getty Images)

A sign is posted in front of new condominiums for sale on December 19, 2022 in Los Angeles, California. (Credit score: Mario Tama/Getty Photographs)

Timing is all the things

With fees at last inching down, now could be an opportune time to acquire a household before the spring year is in total swing, Downs reported. But you require to be prepared. Getting a pre-qualification all set, placing a spending plan, and conversing to a true estate qualified can improve your probabilities of negotiating a much better deal at closing.

In accordance to Miner, stepping into the market place right before it will get flooded by competitiveness could be a very good shift if you want to negotiate terms.

“From what I’m observing,” Miner explained, “I sense like the base is below.”

Gabriella is a own finance reporter at Yahoo Finance. Follow her on Twitter @__gabriellacruz.

Click here for the most current financial information and financial indicators to assist you in your investing decisions

Read the newest money and enterprise news from Yahoo Finance

Obtain the Yahoo Finance application for Apple or Android

Follow Yahoo Finance on Twitter, Fb, Instagram, Flipboard, LinkedIn, and YouTube.

Best real estate markets to buy a home in 2023

Best real estate markets to buy a home in 2023

Even with growing homeownership expenditures squeezing out buyers, some authentic estate markets will stay very hot in 2023, generally thanks to their relative affordability in comparison with the rest of the U.S., a new forecast finds.

The best locations have a little something else in frequent, as well: They’re all positioned in the South.

Dependent on a variety of things, which include home affordability, occupation advancement, migration gains and housing source, the National Affiliation of Realtors (NAR) analyzed 179 markets to ascertain which will provide the most worth to consumers. The info appears to be back again a person 12 months from Oct 2022 and demonstrates predicted need from consumers in 2023.

The median rate of residences in some of these markets isn’t less expensive than the nationwide median of $398,500. Nonetheless, these cities scored superior on other metrics these kinds of as task advancement or housing source.

Right here are the 10 most effective areas to buy a residence in 2023, according to NAR:

1. Atlanta-Sandy Springs-Marietta, Georgia

Median residence selling price: $371,200 

With major tech companies these kinds of as Apple, Microsoft and Visa opening Atlanta offices in latest a long time, the town has a robust occupation current market. 

The Atlanta metro area remains relatively reasonably priced as opposed with other areas in the state. Over 20{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of renters can afford to pay for to buy a median-priced property in the space, based mostly on a calculation that includes a 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} down payment. The countrywide ordinary is 15.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.

2. Raleigh, North Carolina

3. Dallas-Fort Worth-Arlington, Texas

4. Fayetteville-Springdale-Rogers, Arkansas-Missouri

Median property cost: $328,400

Household to three Fortune 500 firms — Walmart, Tyson Foods and J.B. Hunt Transportation Services — this metro spot is next among NAR’s major 10 rankings in conditions of housing affordability.

It is a growing sector, far too, with yearly populace growth of 2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} — perfectly previously mentioned the nationwide typical of .01{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.

Properties are also inexpensive, with rates second only to Huntsville, Alabama, amongst this listing. The share of renters that can find the money for the typical property is almost double the nationwide typical. 

5. Greenville-Anderson-Mauldin, South Carolina

Median residence value: $335,400

Although housing affordability is on par with the nationwide ordinary, task development in this spot is powerful, specially for substantial-paying out info know-how positions like laptop or computer programming or website growth. 

There are additional houses to decide on from, much too, as the supply of properties in 2022 was extra than 2 times the nationwide average. 

6. Charleston-North Charleston, South Carolina

Median house price tag: $416,800

Of the top 10 rankings, the Charleston spot is 2nd only to Raleigh for the best median price tag for houses. It’s also underneath the nationwide common when it comes to affordability.

Having said that, this quick-growing current market has potent migration gains and job advancement that is nearly twice the countrywide ordinary.

7. Huntsville, Alabama 

Median home price tag: $327,500

Alabama’s most populous metropolis is the most cost-effective location for properties amongst this record. Just beneath 30{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of renters can pay for a common residence with a 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} down payment, which is almost two times the nationwide common.

Expanding work chances and small cost of residing will continue on to draw in even a lot more movers in 2023, according to NAR.

8. Jacksonville, Florida

Median house value: $398,000

As with several cities in Florida, Jacksonville became a migration hotspot all through the pandemic, with property costs soaring by virtually 58{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} considering the fact that the beginning of 2020.

Jacksonville’s household costs are just about on par with the median value in the U.S., but it truly is a lot more cost-effective than other regions statewide, according to NAR.

The qualifying revenue to purchase a median-priced dwelling with a 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} down payment is about $98,000. Which is considerably less than most huge metro areas across the state, which includes Miami, where by the qualifying cash flow with a 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} down payment is $140,000.

Jacksonville also has a strong job market and a excellent supply of properties compared with the relaxation of the nation. 

9. San Antonio-New Braunfels, Texas

Median residence price: $342,700

San Antonio grew to become a migration hotspot during the pandemic, particularly from California, exactly where household selling prices and the cost of dwelling have a tendency to be additional expensive.

The city has come to be a place in just the point out of Texas, also. A lot of probable homebuyers have migrated to San Antonio from close by Austin, mainly thanks to less expensive house price ranges.

In San Antonio, citizens earning $85,000 qualify for a median priced residence, which include a 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} down payment, a great deal less than $130,000 required in Austin. Position growth is also more powerful than the national regular.

10. Knoxville, Tennessee

Why rent in NYC is out of control right now

Real-Estate Investing With Little or No Money Down: Investor

Real-Estate Investing With Little or No Money Down: Investor
  • Ana Snider purchased her very first house applying a VA loan.
  • She turned every single property into a cash-flowing asset by leasing them out. 
  • She shares different kinds of mortgage help plans that everyone can use to get began.

Ana Snider claims the American dream is not useless. But sluggish and steady, and just setting up somewhere, wins the race. 

She’s an energetic obligation Navy officer who took an curiosity in authentic estate immediately after renting out the supplemental bedrooms in her key property. 

Before getting her initially house, Snider had been residing in army-foundation housing and required her personal place. So she began on the lookout for her very first property even though preserving up for what she considered would be a essential down payment. 

On the other hand, she was capable to use a VA Mortgage, backed by the Division of Veteran Affairs, for her to start with obtain, which required no dollars down. It landed her a four-bedroom, 3-rest room home for $268,000 in Lemoore, California. Her new monthly property finance loan payment would sum to $1,600, in addition utilities which were about $150 to $200 a month. 

Snider then decided to hire out a few of the bedrooms to her coworkers for $500 each and every, creating $1,500 a month. This left her with a living cost of $100 for the mortgage loan as well as utilities. 

“I realized, oh very well, I acquired this asset for absolutely free and now somebody’s paying my hire,” Snider stated. 

A calendar year later, she went off on deployment and rented out the entire assets to one tenant for $1,750. 

Today, Zillow estimates that the same house is truly worth $365,000. For Snider, that expense grew to become a cash-flowing asset that appreciates in benefit more than time. 

The practical experience made her comprehend that investing in actual estate would be a fantastic way to establish generational wealth. When she returned from her deployment, Snider required to find out much more about this asset course. She commenced listening to the “Bigger Pockets” podcast and genuine estate talks on Clubhouse. But the flood of data from distinctive investors only left her far more bewildered. 

Snider experienced a lot of general information but however wasn’t confident how to truly get begun, what type of property to buy, and even what area would be best. 

She resolved to get her real estate license as a beginning stage, signing up for the study course in April 2020. A year later on, she came across a piece of land in Bremerton, Washington that checked off all her ideal containers. It was a piece of land that had two houses on it for $299,777. 

The primary residence, a 3-bed room, 1-rest room single-family members device, sat in the entrance, alongside the principal highway. The back again house was a one particular-bedroom, a person-rest room device. 

Both homes wanted some rehabbing, which Snider liked. With a tiny do the job, she could increase the property values. The front home was livable but outdated. The back household required a little bit much more function. 

By that issue, she had made provides on other attributes but stored obtaining outbid by potential buyers who ended up providing all dollars. This home had been on the market for six months and the previous buyer’s offer had just fallen as a result of. 

Snider was not ready to get a VA loan for the comprehensive quantity simply because the appraiser would not evaluate the back device as a home and in its place labeled it as a storage unit. So she had to safe a standard bank loan with a 2.99{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} interest fee and a 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} down payment. Her down payment was $8,994. Her in general monthly mortgage loan would be $1,647. 

Snider then moved into the key household when she up to date the flooring and did some dry walling on the back again dwelling. The subcontractor who did the do the job put his time in pro bono so Snider only paid for the substance. In exchange, when he was completed, he would lease the principal house for $1,400. 

About two months later on, the subcontractor became her tenant and Snider moved to the back household where by she would spend the subsequent 9 months. A large aspect of her home finance loan was now protected by her new tenant. This left her with a regular payment of $200 to protect the home loan. 

Right after a few months, she required far more house and commenced hunting for a more substantial most important residence so she could also rent out the back again property. 

In May perhaps 2022, she bought her third home. It was a solitary-household, three-bedroom, two-lavatory dwelling that experienced been lately renovated. This property also sat on a massive ton, which would permit her to develop an supplemental house on it in the future. 

The buy selling price was $429,000. Snider turned to the remainder of her VA loan, which protected most of the amount, other than for $11,700. Snider would need to have to include that hole out of pocket. 

By this time, she had her broker license and was equipped to depict herself as the buyer’s agent on the home. As soon as she marketed it to herself, her fee was $7,000 which she set toward the income payment. This remaining her with an out-of-pocket price of $4,700. 

Her mortgage loan on that residence would be $2,300. Snider then rented out one particular of the rooms for $1,350. 

Entirely, the a few homes Snider now owns insert up to a total price of $1.1 million, in accordance to Zestimate. The complete money she paid out up entrance on all three additional up to just below $14,000. 

How to get started with little to no cash down

If you come about to have access to a VA loan, it can be a wonderful choice for the reason that it isn’t going to call for a downpayment and you never want to get mortgage insurance. Every county has a cap on the financial loan total. But if you purchase home that’s under that cap and however have some loan dollars in leftovers, you can use it for supplemental attributes. 

To be qualified, you or your spouse must satisfy a several specifications set by the Department of Veterans Affairs, and the lender’s credit and income necessities. You will also need a letter of eligibility from Veterans Affairs. 

Whilst Snider was equipped to accessibility a VA loan for two of her houses, she famous that if you aren’t in the army, there are several other financing options you can turn to that would also allow for you to get started investing with minimal dollars down. 

The first just one is a Federal Housing Administration bank loan (FHA). This is a authorities-insured house loan that calls for a reduce down payment. You can put down as small as 3.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} without having acquiring strike with a bigger curiosity fee. You can also stay clear of the added cost of home finance loan insurance plan, which standard loans involve if your down payment is down below 20{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.

If you are using advantage of an FHA bank loan, you are going to need to shift into the property for at minimum a calendar year. Snider recommends having benefit of this head commence by on the lookout for properties with multi-units. This permits you to rent the other units to address your property finance loan payments. You can get a home that has up to four models, or a fourplex, and even now have it categorized as a residential bank loan. If Snider were to start off around, she told Insider her to start with property would be at least be a duplex. 

There are also a large amount of 1st-time residence buyer down payment incentives presented at the state amount. The phrases of these packages vary from condition to state but a straightforward Google search will pull up the selections out there for your spot. You can combine the condition guidance systems with an FHA or regular financial loan. 

A USDA mortgage is a further possibility. This is a form of home loan supplied for homes in some rural regions by the United States Office of Agriculture, Rural Growth. These loans can supply up to 100{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of the expected financing to capable potential buyers, including the closing expenditures. 

Having said that, obtaining permitted has constraints which include that it need to be a one-family members residence and be in particular geographic locations. 

Last but not least, innovative funding is another choice, which just means alternate means of acquiring a loan. A person primary route that buyers can request for is to have the vendor finance the financial loan. This simply just means as an alternative of turning to a lender, you can sign a agreement with the vendor and shell out every month as although it were being a lease payment. There are quite a few factors why a vendor may agree to these types of an arrangement, like the have to have to get out of a property finance loan they cannot afford or just wanting to offload the house speedily. 

Regardless of how you get commenced, many solutions could be explored, Snider noted. You just have to get started somewhere. 

“I only moved to the United States in 2001 and the American Desire is not lifeless. You just have to go after it because there are millionaires currently being built in real estate every working day,” Snider said. “A good deal of them started out with just an FHA financial loan and downpayment support.” 

Red-hot Miami housing market expected to defy 2023 cost correction as blue state exodus continues

Red-hot Miami housing market expected to defy 2023 cost correction as blue state exodus continues

Florida’s red-incredibly hot actual estate market place is not expected to interesting anytime shortly as scientists predict Miami household selling prices will defy a 2023 charge correction and carry on to increase. 

U.S. current dwelling profits slowed for the 11th consecutive month in December as increased property finance loan costs, surging inflation and steep dwelling charges sapped shopper demand from the housing market. 

But Miami looks to be the exception to the rule as People in america keep on to abandon blue condition tax guidelines.

“As very long as California and states like Massachusetts move steps like the mansion tax or the millionaire’s tax and continue to travel ultra-substantial web value folks out of their states, I imagine that this year is likely to demonstrate wholesome progress for Miami and South Florida,” actual estate expert Dina Goldentayer explained to “Mornings with Maria” Friday. 

Research Claims Wealthy BLUE Condition IS AMERICA’S MOST Economical, BEATING STATES Countless numbers ARE Going TO

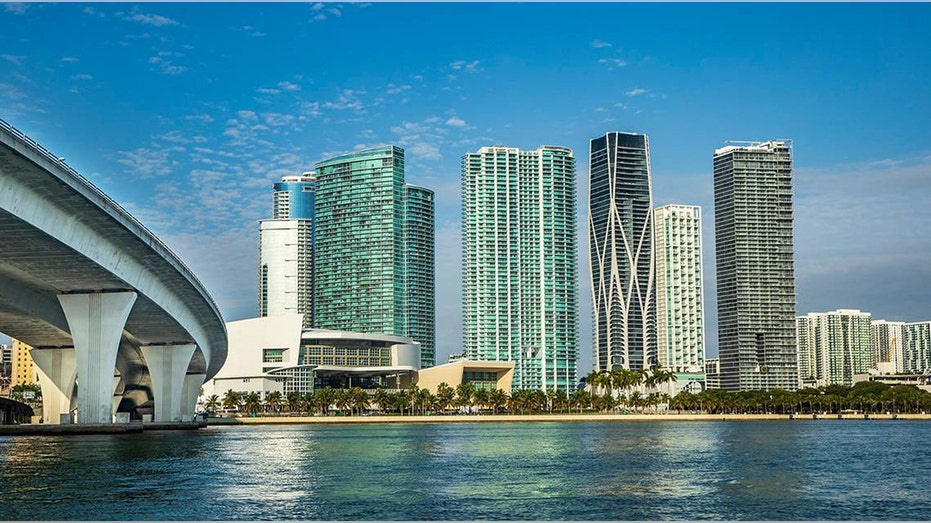
Miami high-rise condo buildings

Solitary-family property and condo rates carry on to climb in South Florida, in spite of a slowdown in sales action. In 2023, housing selling prices in Miami are anticipated to increase, in accordance to a analyze from Goldman Sachs. (Pedro Portal/Miami Herald/Tribune Information Serv (Pedro Portal/Miami Herald/Tribune News Assistance by means of Getty Pictures / Getty Pictures)

Goldentayer, the govt director of revenue at Douglas Elliman, observed an “encouraging” new paper released by Goldman Sachs scientists very last week forecasting Miami will be 1 of only two key housing U.S. markets to escape a staggering countrywide household cost correction in 2023.

In accordance to the U.S. Census Bureau’s Classic 2022 population estimates, Florida is the quickest-growing point out with a 1.9{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} populace enhance involving 2021 and 2022. 

Harsh WARNING ON US Authentic ESTATE Sector ISSUED: ‘AMERICA Demands Much more HOUSING’

But with an unparalleled total of homebuyers flocking to the Sunshine State, realtors are nevertheless grappling with an stock difficulty. 

“Stock is continue to fairly constrained. You know, a 12 months ago, if I experienced a buyer fly in, we may perhaps be ready to see five to eight houses. Now, I could see I could demonstrate that similar purchaser eight to 12 residences. But the inventory is continue to rather restricted,” Goldentayer stated Friday. 

“And there’s considerably from an oversupply in the sectors of the marketplace in which there is much more inventory. In a natural way, you happen to be going to see much more leverage for prospective buyers out there.”

home sales

According to a new paper completed by Goldman Sachs researchers, the Miami metropolitan spot is anticipated to be 1 of the two housing marketplaces to see rate raises in 2023.  (iStock / iStock)

An more issue that is fueling Florida’s housing marketplace is the surge in global purchasers. Goldentayer shared that several global consumers have come from all about the globe to get a piece of the Sunshine Condition – having said that, the “bread and butter” for the Miami marketplace stays purchasers leaving blue states. 

DESANTIS WARNS In excess of CHINA Actual ESTATE INVESTMENTS: ‘GOBBLING UP LAND’ NOT IN FLORIDA’S Very best Interest

“The primary intercontinental buyer for the Miami marketplace remains Canadians. I have a large amount of clientele from Toronto and Montreal. I am unquestionably operating this year with far more European potential buyers,” she ongoing.

“The bread and butter for my market stays potential buyers from blue states like California, like New York. They nevertheless quite considerably fuel the extremely market market.”

GET FOX Business enterprise ON THE GO BY CLICKING Here

FOX Business’ Megan Henney contributed to this report.

Up from here? The free fall in housing market demand just concluded, says Capital Economics

Up from here? The free fall in housing market demand just concluded, says Capital Economics

But there could at last be some good information for builders and brokers: Scientists at Cash Economics consider housing sector activity is bottoming out.

“There are developing indicators that housing industry activity may be near to a trough. The decline in house loan costs around the past pair of months has led to a little enhancement in affordability and a increase in homebuyer sentiment, albeit from a report low. Corroborating this, mortgage loan applications for household buy have ticked greater in the previous couple of months, which ought to feed by means of to increased product sales,” writes Sam Corridor, assets economist at Funds Economics.

It is not just Cash Economics. There is a increasing optimism among brokers and brokers across the place. They’re hoping that loosening economical ailments, which noticed the regular 30-yr fastened mortgage charge drop from 7.37{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 6.09{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} over the earlier two months, will assist to give the looming spring year a minimal juice.

Let us be obvious: Even if housing industry activity (i.e. residence gross sales) has in fact bottomed out, it doesn’t guarantee that household sales will have a swift restoration. Immediately after all, housing affordability remains “pressurized” to a historic diploma. That will happen when U.S. home costs soar 41{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in just over two a long time and mortgage prices spike from 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to over 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in just a 12-thirty day period span.

“But any recovery in housing market place action this year will be tepid. Stretched affordability, a weakening overall economy, and falling residence charges will all weigh on activity. As a end result, we assume 2023 will be the weakest year for gross sales given that 2011 and for starts since 2014,” generate Cash Economics scientists.

Just because U.S. dwelling profits might be nearing a base will not suggest we need to also pencil in the bottom for U.S. property charges.

“Affordability will continue being stretched,” compose Funds Economics scientists. “We believe residence prices will have to have to slide by a further 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} or 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to convey affordability again to a degree that will support additional usual amounts of need.”

Via October, the Circumstance-Shiller Countrywide Residence Cost Index has U.S. house price ranges down 2.4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from the June 2022 peak. In 2023, Funds Economics expects U.S. dwelling rates to fall 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} whilst the ordinary 30-calendar year home loan charge slips to 5.75{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} by yr-stop. Peak to trough, Money Economics expects U.S. dwelling rates to fall among 8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}

Moody’s Analytics chief economist Mark Zandi also thinks U.S. residence product sales are nearing their base though countrywide home charges have further to drop.

“Housing desire [home sales] is near to a trough housing supply [housing starts and completions] has however to hit bottom and [U.S.] residence prices have a way to go in advance of achieving their nadir,” Zandi tells Fortune.

Peak to trough, Zandi expects U.S. household price ranges to fall 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}—with “overvalued” housing marketplaces out West having hit the toughest.

Let us say Capital Economics and Moody’s are proper and countrywide home costs slide 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from peak to trough. If that takes place, household rates as calculated by Circumstance-Shiller would slide again to Oct 2021 stages. On one hand, that would mark the 2nd-most important residence price tag correction of the put up-WWII era. On the other hand, it would be relatively tame in contrast to the 26{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} nationwide house price tag correction observed among the housing bubble’s best in 2007 and the housing crash’s base in 2012.

Seeking for additional housing facts? Stick to me on Twitter at @NewsLambert.

Master how to navigate and fortify trust in your business with The Rely on Element, a weekly newsletter analyzing what leaders want to triumph. Signal up below.