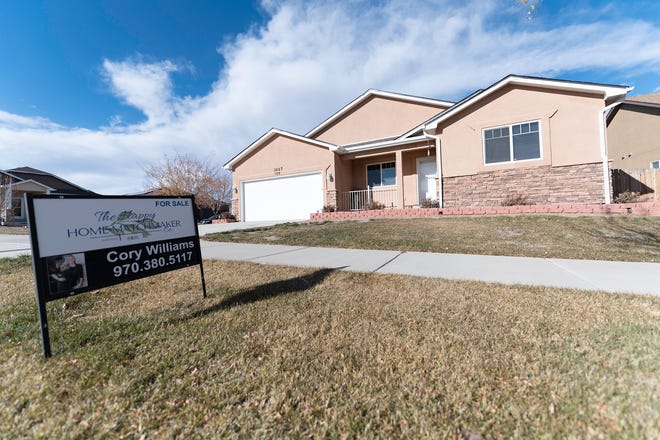
Prospective homebuyers in Clark County and across the nation are facing a similar issue when exploring for a home: There are barely any to select from.
“We’re conversing about really record-low stock,” he mentioned. “There is not a ton of stock in the lower value ranges that are the most affordable, the place most of the transactions materialize.”
Southwest Washington had 2.4 months of stock in November, that means it would just take that very long for all houses on the industry to offer if no new residences ended up listed. However this is an advancement from previous wintertime when stock was much less than a single month, Lamb does not foresee ranges returning to the four to six months regular of a well balanced sector.
“It is a ‘Why is the canine taking in its tail?’ form of dilemma,” he mentioned. “You have no inventory, then anyone who would like to shift simply cannot transfer because they don’t have anywhere to go, and so they cannot set their residence on the marketplace.”
It is also challenging to boost stock by developing new housing, he included. Among complying with Washington’s constructing regulations and the extended procedures of acquiring permits and entitlements, it can take years to create subdivisions.
In Lamb’s working experience, although the state’s regulations result in significant-excellent housing, this high-quality will come with a expense that deters new enhancement.
“It is extremely challenging and highly-priced to make everything in Washington,” he explained. “For example, the insulation code. I have had various builders convey to me that the last improve in the insulation code extra tens of thousands of dollars to the value of the residence.”
As a result, some men and women are not shopping for homes due to the fact there aren’t more than enough homes to obtain.
Even as inventory stays a challenge, neighborhood purchasers can just take consolation in declining house loan costs and profits costs. The median household sale price tag fell 2.1 {515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from Oct to $514,000, although fascination prices for 30-calendar year mounted home loans are trending downward towards 6 per cent, according to the authorities-sponsored property home finance loan packager Freddie Mac.
Lamb thinks mortgage loan charges will continue coming down, producing the marketplace far more favorable to buyers and putting much less tension on sellers. These lessen charges, put together with falling selling prices, are creating houses extra cost-effective than they had been a number of months ago.
In the prolonged phrase, nevertheless, Lamb does not assume housing will become noticeably far more cost-effective. “The froth that arrived with that ridiculous market is kind of blowing off,” he explained. “Bottom line is, I really don’t see selling prices getting reduce.”
A report unveiled last 7 days by real estate info curator ATTOM disclosed that the slowing true estate industry is influencing property flippers as effectively. Nationwide home-flipping fees dropped for the duration of the third quarter to 7.5 {515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of all house income, down from 8.2 p.c in the second quarter, and investor income on flips fell to a 13-year small.
Heading ahead, Lamb advises homebuyers to be patient as desire fees arrive down and the current market stabilizes.
“If they are individual, they’ll be in a position to come across a dwelling,” he reported. “For all consumers, the times of heading, ‘Oh, I’ve bought 30 houses to select from’ — properly, no. But you may have two or 3. Which is far better than it was.”
Pueblo’s serious estate current market is continuing to gradual down, and the fallout is impacting companies industrywide. It’s not just Realtors feeling the impacts — it really is residence builders, home loan lenders and title corporations far too.
“Overall, the housing slowdown is obtaining a ripple influence across the market as we see a lot more title firms, house loan corporations and builders lessening staff members,” explained Dave Anderson, Pueblo Association of Realtors communications chair.
“There’s layoffs coming, I am confident,” claimed Randy Nobiensky, self-employed contractor with RH Builders who is seeing the effect on builders and Realtors. “We are all connected, all in the exact same boat, and with the interest premiums exactly where they are. Folks are not obtaining, they are buckling down.”
Nobiensky, who is vice president of the Pueblo Space House Builders Association, explained the cost of materials, supply chain issues, soaring desire charges and inflation have all produced the marketplace tough for builders. The significant dazzling spot of his year was becoming named builder of the 12 months by his friends, but he said he is looking at some longtime builders opt for retirement.
New developing permits are slowing
Just 16 new creating permits were issued in Pueblo County in November.
“Searching at the very first 11 months of the yr, we’re down 202 permits as opposed to the exact period of time in 2021,” Anderson stated.
The affect has led builders, in particular spec home builders who never have a customer lined up in progress of the make, to halt development on new houses, provide down their stock and “wait it out,” Nobiensky claimed.
“They have five, 10 or 15 households on the marketplace, so they are going to halt building until the inventory they have has offered,” he described. “For our neighborhood, that is 90{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of us.”
“It’s terrifying because which is how we make a living. It’s not wanting great, but it is just a cycle,” Nobiensky claimed.
The builders with a ton of houses on hand may possibly be attempting to liquidate them with revenue quite shortly, he spelled out.
As a customized house builder, Nobiensky is not impacted rather as a great deal, but he’s gone from generating four to 5 properties in a yr to two under construction suitable now. He has been ready to make ends fulfill by shifting to a commercial finish career and remodeling perform to “fill in the gaps.”
He predicts other builders also will very likely change to remodeling do the job as house owners shift target to enhancing the households they reside in because a lot of are not able to manage to buy a new dwelling proper now.
Property finance loan interest premiums have almost doubled from a calendar year in the past and are hovering amongst 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, primarily based on the buyers’ credit score scores. That signifies home loan payments can be almost double, too.
Nobiensky claimed his consumers are likely to be retired couples who are not impacted as a lot by the home loan fees since they have funds from the sale of one more house.
Prior to the fascination premiums climbing, Pueblo’s real estate market endured from small inventory and high need. Now, because of to the sharp enhance in the fascination level, the specific opposite is true.
Activity across Pueblo’s actual estate market place ongoing to slow in November, with new listings down somewhere around 25{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. Pueblo saw 116 much less listings this November than it did in November 2021, Anderson explained.
“Pending product sales were down 43.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} as opposed with very last November, practically matching the major fall in offered listings, which had been down just shy of 47{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502},” he stated.
Last November, 320 residences offered in Pueblo this year it was just 178. The amount of cash the revenue generated dropped also, from $88.7 million final November to $53.5 million this November.
Nobiensky reported although ailments are hard, he thinks the 2008 economic downturn and serious estate crash was considerably worse.
“I do not imagine any of us actually know for sure,” he claimed. “But it is not likely to be as long because aspect of the issue is inflation and finding merchandise like concrete, windows and garage doors — all of which is fixable.”
“COVID-19 took its toll” on building content charges and availability, and “now we are just attempting to get caught up,” he explained.
What will the potential bring?
Home loan Financial institution Russ Lane claimed it is his individual belief that fascination prices will continue being “at about the same location they are now or go just a very little larger for about six months.”
Anderson reported, “Many in the industry are predicting a rough yr in advance.”
“I assume we will be all proper. We can weather conditions the storm,” Nobiensky reported.
1 factor is for specific: Pueblo is not by yourself in enduring the actual estate slowdown.
“The slowdown can be witnessed across a multitude of groups with quantities that are a significantly cry from the industry frenzy of a year back,” mentioned Martin Schechter of the Colorado Affiliation of Realtors.
Chieftain reporter Tracy Harmon addresses business news. She can be reached by e mail at tharmon@chieftain.com or by way of Twitter at twitter.com/tracywumps.
When it comes to building prosperity, People in america say a person matter and do a further.
When asked the ideal way to build personalized prosperity, 23{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of grownups said investing in serious estate, according to the new CNBC Make It: Your Money study, carried out in partnership with Momentive. That tends to make it the most popular would-be prosperity developing method, in advance of investing in stocks (16{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}), commencing your have small business (15{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}) and getting a second task or facet hustle (12{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}).
But that is not what all those searching to raise their prosperity actually did this year. In 2022, the No. 1 action Individuals took to develop wealth, stated by 27{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of respondents, was investing in the inventory market place. Just 12{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} invested in actual estate.
So what is actually maintaining Individuals from investing the way they want? The largest factor, financial professionals say, is charge.
“In real estate, it can take income to make cash,” claims Nicholas Bunio, a qualified economic planner in Downingtown, Pennsylvania. “Indicating you want to pay back either money for the residence, or mortgage loan the home. Not to mention take care of up the residence and annually routine maintenance. Which expenditures dollars.”
In excess of the earlier year on your own, the average price tag of a 20{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} down payment for a house in the country’s 50 premier metropolitan areas has developed by 35{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to almost $63,000, in accordance to new info from LendingTree.
It’s no marvel, then, that wealthier respondents in Make It is study were extra probable to have invested in true estate. Just 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of respondents earning $50,000 or fewer said they acquired real estate this year, as opposed with 12{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} earning among $50,000 and $99,000 and 21{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} earning $100,000 and up.
It’s not hard to see why investors have been salivating over true estate these days. Certain, you could need tens of hundreds of bucks to get begun, but appear at the funds individuals are producing! U.S. residence selling prices ended up up 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in the 12 months ending in October 2022, according to info from CoreLogic. Inventory selling prices declined additional than 15{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} over the identical time period.
But for lots of investors seeking to receive long-phrase returns, the barrier to enter the genuine estate market may conclude up staying a silver lining. Shares have a a long time-lengthy historical past of delivering compounding, wealth-building returns that outpace the amount of inflation above time.
The similar can not essentially be claimed for actual estate, claims Kevin Brady, a CFP with Wealthspire Advisors in New York City. “Genuine estate has a historical observe history but that record reveals that very long-time period returns generally match or scarcely exceed inflation,” he claims.
From March 1992 by September of this calendar year, house costs have logged ordinary once-a-year progress of 5.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, according to data from exploration business CEIC. More than the exact same period, the S&P 500 posted an annualized total return of 9.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.
“Bottom-line, youthful investors need to have a healthy allocation to stocks,” claims Brady.
Indication up now: Get smarter about your income and profession with our weekly publication
Don’t overlook: 60{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of Individuals see crypto investing as extremely risky—but millennials are nonetheless its largest followers
If “hot” was the overused word to describe the U.S. housing maret in 2021, then lukewarm to outright freezing might best describe how the market fared overall this 12 months.
The pandemic housing market place growth, which saw property price ranges go up by 40{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} about a two-yr period of time, started slowing down in the second half of the calendar year as mortgage costs doubled when compared to the beginning of the year.
As the Federal Reserve sought to tamp down decades-higher inflation with rate hikes in the course of the yr, rising house loan charges contributed to the expanding mismatched anticipations amongst prospective buyers and sellers. Houses sat on the marketplace for months as sellers ongoing to rate homes at premiums potential buyers could no lengthier manage. Contracts were canceled, asking costs were slashed and inventory ranges dropped.
Soon after crossing 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in October, mortgage loan prices have been slipping steadily around the last five weeks, which could offer you some aid to prospective buyers but could not offset nevertheless-higher asking selling prices.
So, what is ahead for the housing market in 2023? We spoke to six experts for their predictions:
The Federal Reserve and mortgage costs
The Fed raised its crucial limited-expression fascination level by 50 percent a percentage position Wednesday, a lesser hike than its previous 4, as inflation showed signals of easing.
The Fed also indicated that the financial state would be grappling with slower growth, higher unemployment and higher inflation in 2023.
Weaker expansion normally sales opportunities to reduce lengthy-time period fascination costs, such as home loan rates, claims Mike Fratantoni, main economist for the Home loan Bankers Affiliation.
“The housing industry has surely welcomed the recent drop in property finance loan prices,” he reported. “This decrease is reflecting market place expectations of being close to the peak for short-term fees, as perfectly as increased symptoms that the U.S. is headed for a economic downturn subsequent year.”
Innovations in home loan finance
Housing finance has arrived at an inflection stage, states Janneke Ratcliffe, vice president of the Housing Finance Policy Centre at the Urban Institute.
She expects to see innovation speed up with lenders, startups, advocates, scientists, and policymakers actively pushing the envelope close to what is attainable in property finance loan finance.
“We’re observing pilots and new plans around choices in credit history scoring, artificial intelligence, local climate adaptation, made housing, and a lot more,” she states. “Not only does the sector see the problems of inequality, but lots of players are also actively voicing their commitments to shut the racial homeownership hole.”
Ratcliffe also expects to see enhanced use of adjustable-amount home loans, which made up 12{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of complete applications in November, up from 3.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in November 2021.
“Would-be homebuyers need to not fear this financial instrument,” she says. “Their use has generally been widespread, and regulatory reforms instituted after the Fantastic Recession have considerably mitigated their threat.”
Foreclosures is the consequence of two simultaneous triggers: the lack of ability to spend, which outcomes in delinquency and the absence of equity in a property, states Odeta Kushi, deputy main economist for 1st American Economic Corp..
With ample fairness, a home-owner has the choice of marketing the house or tapping into that fairness to weather conditions a momentary economical setback. The inverse – a absence of equity in the house devoid of a economical setback that prospects to delinquency – will once more not finish in foreclosures.
Property owners have extremely substantial ranges of tappable household equity currently, offering a cushion to face up to opportunity price tag declines, but also protecting against housing distress from turning into a foreclosure, claims Kushi.
“In truth, if distressed home owners are needed to resolve delinquency, presented their equity buffers, involuntary gross sales are significantly a lot more likely than foreclosures,” she says. “While we can hope the selection of foreclosures to drift increased as the labor current market slows and home selling prices tumble from their peak, the result will probable be extra of a foreclosures trickle.”
Housing inventory will remain low
The continual lack of listing stock has been the crucial driver of value gains during the pandemic-era housing boom, and it will be the essential underpinning of prices in the course of 2023, states serious estate appraiser Jonathan Miller, who prepares the monthly Douglas Elliman Genuine Estate report for New York Town.
“Listing stock was piled to the sky in earlier housing downturns,” claims Miller. “People are wedded to the lower fees they refinanced into or procured residences all through the increase. Excess supply is not the tale for 2023 simply because, even with modest listing stock progress, price declines should really be held to a least.”
Redfin forecasts about 4.3 million dwelling revenue in 2023, which is much less residence product sales than in any yr given that 2011 and a reduce of 16{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} year in excess of year.
Declining household charges
Whilst there will be no wave of foreclosures, house prices will decline in 2023, claims Taylor Marr, deputy chief economist for Redfin.
Marr expects the median U.S. house-sale value to fall by approximately 4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2023. Even with selling prices falling 4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} 12 months above yr, properties will be considerably fewer affordable in 2023 than they have been prior to the pandemic homebuying increase, he suggests.
“Taking future year’s projected selling prices and mortgage loan premiums into account, the standard homebuyer’s monthly payment will be about 63{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} greater in 2023 than it was in 2019, just ahead of the pandemic commenced.”
Residence selling prices will decrease the most in pandemic boomtowns even though markets in the Midwest and Northeast will maintain up finest, claims Marr.
Costs are anticipated to fall most in pandemic migration hotspots like Austin, Texas, Boise, Idaho, and Phoenix, as well as pricey West Coast cities. In the meantime, housing marketplaces in somewhat economical Midwest and East Coast metros, in particular in the Chicago region and parts of Connecticut and upstate New York, will keep up somewhat perfectly.
“Those areas have a tendency to be extra stable than high-priced coastal regions, and they didn’t warmth up as a great deal all through the pandemic homebuying frenzy, that means they also really do not have as far to drop,” he states.
New household development outlook
Single-family members housing commences are set to article a calendar decline in 2022, the 1st this sort of drop in 11 years, even with a persistent structural deficit of housing in the U.S., in accordance to the National Association of Property Builders.
Residence builder sentiment, as calculated by the NAHB/Wells Fargo HMI, has declined for 11 straight months, signaling an ongoing contraction for property creating in 2023.
“Single-spouse and children household developing will ultimately direct a rebound for housing and the total financial state in 2024 as curiosity premiums fall back on sustained basis, bringing need back to the for-sale housing market,” states Robert Dietz, main economist for the Nationwide Association of Home Builders.
Dietz also expects multifamily design quantity will slide back in 2023, immediately after a really powerful 12 months in 2022. Multifamily property developing, which is more than 95{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} built-for-rent, seasoned strength in 2022 as mortgage loan fascination prices increased and for-sale housing affordability ailments declined.
“However, there are almost 930,000 flats underneath development, the highest whole because January 1974,” he claims. “A growing unemployment level, improved apartment offer, climbing vacancy prices and slowing hire progress will sluggish multifamily development future 12 months.”
Making conversions?
Business to residential conversions will remain additional speak than motion, in accordance to Marc Norman, affiliate dean of the New York College College of Skilled Studies’ Schack Institute of Genuine Estate.
“We’ve lived with the pandemic for practically 3 a long time, but that even now is not sufficient time to change ownership, financing, and regulatory devices for conversion of underutilized office environment place,” he states. “We might see the beginnings of conversions, but most structures will continue to be in limbo owing to extensive-term professional leases and the continuing higher expense of financing.”
Swapna Venugopal Ramaswamy is a housing and overall economy correspondent for United states These days. You can follow her on Twitter @SwapnaVenugopal and indicator up for our Daily Revenue newsletter here.
On 5 Oct 2021, AS Harju Elekter posted a inventory exchange launch in which it declared that Harju Elekter AB, a subsidiary of AS Harju Elekter, concluded an arrangement with LC Growth Fastigheter 101 AB, a subsidiary of Wästbygg Gruppen AB, in purchase to purchase 100{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of the shares of LC Progress Fastigheter 17 AB. Harju Elekter resolved to obtain the serious estate business under Harju Elekter Companies AB rather of Harju Elekter AB, and on December 15, 2022, Harju Elekter Solutions AB concluded the transaction to acquire 100{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of the shares of LC Growth Fastigheter 17 AB.
The ordered real estate business LC Growth Fastigheter 17 AB was designed exclusively for the construction of the Västerås manufacturing facility, in which the output requirements of Harju Elekter were taken into account in the design course of action. In the future, it is prepared to merge the ordered corporation with Harju Elekter Products and services AB, which benefits from the Group’s basic principle of retaining creation functions and true estate administration in different organizations. Aron Kuhi-Thalfeldt (chairman), Tiit Atso, Priit Treial, Tiit Luman and Erko Lepa had been appointed to the bought company’s Board and Mikael Schwartz Jonsson (Running Director of Harju Elekter AB) was appointed as Managing Director. The cost of the transaction was 10.5 million euros (SEK 115 million).
The inventory trade release of AS Harju Elekter, printed on 13 September 2021, announced that for leasing the setting up in Malmö, which will be finished by the stop of 2022, a lease arrangement was entered into with Nyfosa AB. As Nyfosa AB was unable to receive a making allow for the building of the setting up and no suitable rental premises could be observed in Malmö, AS Harju Elekter made a decision to move output from Malmö to the Group’s recently developed factory in Västerås and to the current manufacturing device in Keila in the very first 50 percent of 2023 for the reason of price tag effectiveness.
Harju Elekter is an global industrial team with extensive practical experience in delivering future proof answers for electrical ability distribution. We engineer, manufacture, and install electrification answers for utilities, industries, infrastructure, public and industrial structures. The entities of Harju Elekter Team in Estonia, Finland, Sweden, and Lithuania employ close to 900 men and women, and the Group’s 9-month revenue in 2022 was 125.3 million euros.
Tiit Atso Chairman of the Management Board +372 674 7400
Zillow Senior Economist Jeff Tucker breaks down the outlook of the housing current market and house loan premiums pursuing the Fed’s most recent price hike, together with regional house pricing traits ahead of 2023.
Video clip Transcript
[AUDIO LOGO]
DAVID BRIGGS: Fed Chair Jerome Powell expressing inflation in the housing market could start out to great by the center of 2023. But will a further 50 level hike further more punish the housing sector? Joining us now is Zillow Senior Economist Jeff Tucker. Jeff, very good to see you. How will today’s determination by the Fed impression the housing sector that the Fed chair reported, quote, “had weakened appreciably?”
JEFF TUCKER: Yeah, you know, modern announcement was not a surprise in terms of the true 50 foundation position hike. So I consider that information of somewhat having his foot off the brakes experienced been priced in for mortgages and 10-calendar year treasuries previously. So it continue to seems like a modest phase in the right route. We have noticed that 10-calendar year Treasury doing work its way down from more than 4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 3 and 1/2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.
And critically for housing, that has brought the home loan fee down on a 30-year mortgage from about 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} again down to about 6 and 1/3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. That’s seriously key development in terms of improving affordability for homebuyers. And this– it really is a long road for us to get back again from this substantial-inflation, significant-fee natural environment to a much more gradual and regular reduced-inflation, a lot less-high-priced natural environment. And we are making development in that way at this minute.
SEANA SMITH: Jeff, you stated the progress that we’re creating, the fall in home loan fees. Do you expect that decline to proceed? And in which do you consider prices are headed then if, in point, we do see that decrease proceed?
JEFF TUCKER: I assume that is the foundation situation scenario appropriate now. We are observing a ton of products inflation kind of turning the corner. And we have a good deal of motive to be expecting shelter inflation also to turn the corner in the new calendar year. The Zillow lease index calendar year-above-yr development peaked back in February. That usually takes time to movement as a result of to the CPI lease index.
So we anticipate sometime in the first or next quarter to actually see that get started to decelerate on a yr-more than-12 months basis. That is the solitary biggest component in providers in the CPI. So placing that all together, I assume the foundation situation has to be that inflation form of carries on on this trajectory downward.
So what does that do to mortgages? I feel that does deliver us back into the 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} assortment above the program of 2023. The far more optimistic circumstance is that we make a great deal of development towards the lessen end of that variety. The considerably less optimistic circumstance is that we conclude up stalling in the upper 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}– higher five-place anything p.c assortment for home loans.
DAVID BRIGGS: Yeah, it definitely is hard to think about premiums acquiring a great deal underneath 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. In conditions of housing costs, what’s your prediction for ’23?
JEFF TUCKER: Yeah, our forecast right now looking a yr forward is for charges to fall by probably 50 {515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 1 proportion position from now, 12 months forward. Either way, it is really close to flat. I know there are a lot more bearish forecasts out there of far more sizeable price tag declines.
I imagine the variety just one factor in our design halting us from that prediction is the reduced stock. Stock has not created up in a big way. A good deal of sellers are just remaining place in their households. So it actually indicates out there in the market place, you don’t see a glut of homes for sale. That has type of helped preserve a lid on some of all those procedures in which costs essentially start off to fall rapidly.
You will find surely neighborhood coloration to this, of class, in which West Coast marketplaces and some of the Inland West, like Phoenix and Las Vegas, they’ve currently fallen possibly close to 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from a peak back again in about May well or June. And I feel they however have a very little little bit of area to appear down. But at a nationwide stage, we just don’t see this type of inventory force of pressured sellers or really inspired sellers. If anything at all, sellers are determined, type of remain put, hunker down, and continue to be heat by their 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} home loan that they locked in back in 2021.
SEANA SMITH: Jeff, what does all this indicate then for the rental market place for the reason that value is nevertheless substantially increased yr-around-calendar year? I guess, on a thirty day period-above-month basis, you might be beginning– the information that Zillow set jointly starting to see some enhancement. So what does that imply in terms of rental charges? And how long until we see that mirrored in the CPI facts?
JEFF TUCKER: Yeah, we have viewed rents– asking rents basically start out to decrease thirty day period-in excess of-month in the previous– generally this winter season, even past the usual seasonal pattern. So it looks like there is certainly a little bit of imply reversion in which that rent advancement is cooling down seriously sharply. That is terrific news for renters. It can be terrific information for the inflation actions.
But it’s truly at minimum a 12-month lag from that slowdown in our asking rent index filtering through to CPI for lease and owners’ equivalent hire. It really is difficult to say, but I believe probably the very best-circumstance circumstance is that February could change out to be the peak for year-about-calendar year CPI hire growth. That would just be 12 months after our hire index peaked. There could be a bit of a lag, possibly it is really someday in the spring. But we do know this is by now bringing relief to renters both obtaining renewal– renewal letters or likely out there taking into consideration a new apartment to go into this winter season.
DAVID BRIGGS: Yeah, exciting, seriously, to see in which they’re falling the speediest. New York and Seattle between the leading five, not wherever you normally anticipate it. Talking of locations, the Midwest seems to be the greatest position for initial-time homebuyers, in accordance to Zillow details. Why so?
JEFF TUCKER: It’s all about affordability. Affordability has been holding again the housing industry, particularly keeping back again household income quantity all all over the state. That one-two punch of price appreciation and bigger mortgage prices usually means that destinations like Seattle, New York, Miami, that mortgage is just out of attain for a big swath of homebuyers at the second.
So we appeared around the nation and where is the past variety of regional bastion of affordability? It truly is the Midwest. These are destinations where by center-course families’ money is however plenty of to qualify to get a pleasant relatives-sized residence. Nobody likes spending higher fascination, even in the Midwest, but you can find a large amount more people who can qualify to purchase a household there and in which it’s still seeking like they’re just in a very good placement to purchase in all those marketplaces.
I thought it was placing, way too, that these were some of the same marketplaces you just highlighted where hire is now rising the speediest. These are the marketplaces exactly where youthful individuals environment out on the lookout for a area of their possess, regardless of whether leasing or getting, they are acquiring a lot more option sort of in the heartland, in the Midwest, and the Wonderful Lakes locations. So in phrases of housing marketplace exercise, which is exactly where we hope it to be the busiest in the calendar year forward.
SEANA SMITH: Jeff, what about the trends of shopping for with family and close friends? That’s one thing that trapped out to me. A whole lot of us questioned it, whether or not or not that is a smart economic strategy. I will not want you to weigh in on that. But that momentum seriously, I assume, just indicators accurately what is going on in the housing industry appropriate now and the fact that so numerous to start with-time homebuyers only can’t pay for it no issue wherever they are in the nation.
JEFF TUCKER: That’s absolutely proper. It arrives back to affordability. And this is a technology of Individuals moving into their mid-30s now. The main of the millennial technology is very quite a few. There are quite a few million excess individuals in their early 30s and late 20s correct now, and they’re just as determined as previous generations to get into homeownership, but they are operating into the biggest affordability challenge in a technology, perhaps that we have at any time seen, many thanks to that just one-two punch of prices and mortgage premiums.
So folks are receiving imaginative. They’re wondering of other methods to get into homeownership. We have found some other type of life milestones are delayed for the millennial generation, issues like relationship and getting young ones. So that type of results in this circumstance where there are people in their early 30s or late 20s who might feel, Okay, how about if my mom and dad go in on a property with me?
How about if my pals and I go in on a household jointly? We have acquired a area to stay. We know that the selling price– you know, that our every month lease isn’t really heading to keep going up like if we stay in the rental market. So it is variety of folks looking for techniques to get into homeownership.
And I’m unquestionably reassured that the way that they are undertaking it is not what we did in 2005 and 2006 with ninja financial loans and no underwriting and balloon payments. Property finance loan underwriting is still rock sound and pretty strict, frankly, for homebuyers. Which is why folks are on the lookout at these methods of just wondering, Alright, who can I acquire a dwelling with if I won’t be able to just do it by itself suitable now?
SEANA SMITH: I don’t know. It even now seems a little bit dangerous to me just in terms of proudly owning a house with buddies or other relatives associates. I really don’t know. Probably I am an outlier there. Jeff Tucker, fantastic to have you. Many thanks so a great deal for signing up for us this afternoon.