As home prices drop, Colorado’s real estate industry looks to history to understand trends

As home prices drop, Colorado’s real estate industry looks to history to understand trends

If you’re house hunting, there are plenty of homes available in Colorado — nearly 10,000 at the end of March, which is up 41.8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from a year ago. 

Prices are a bit lower, too.

If you need a loan to pay for the house, though, that’ll cost more than it would have a year ago. Even so, mortgage loan rates are about where they were in 2008. And that’s roughly two-thirds lower than the peak in the early 1980s.

In this Oct. 22, 2019 file photo, a sign stands outside a home for sale in southeast Denver. (AP Photo/David Zalubowski, File)

The way Colorado Realtors see it is that while the for-sale market has slowed significantly and median sale prices have dropped, it’s been worse. Way worse. And now, the market appears to be settling down with the latest inflation report showing prices aren’t rising as fast as before and the Federal Reserve considering a pause on upping interest rates.  (More on that below.)

“The reality is that there’s a bunch of people that need to buy and sell homes. Their life situation changed. That’s a natural thing. It’s not like the world’s come to an end. It’s just slowing down,” said Realtor David S. Anderson, with Re/Max of Pueblo. “And we’re probably getting more to a more neutral market that we haven’t been in since ’19 when you were looking at three to four months on the market.”

Anderson has a point. Just look at the March home sales data from the Colorado Association of Realtors between 2014 and 2023. 

The count of houses sold in March is closer to where it was in 2019 in the seven-county Denver metro area, according to the latest “Market Trends” report from the Colorado Association of Realtors. Statewide, the number of days a house sat on the market before someone bought it was back to the more leisurely pace of 2019 as well. As for inventory? Bidding wars are rarer. Houses are available, though there are fewer for sale now than two years ago. 

In the largest market, median sale prices fell 12.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to $650,000 in the city of Denver, and that’s kind of a relief for the real estate industry because the frenzy pushed prices up so high, many prospective buyers left disappointed even after offering more than the asking price on multiple properties. 

“It’s like the heavens have opened up and a giant eraser has come down from the sky and is just kind of erasing all of the 2021 and 2022 madness,” said Matthew Leprino, CEO of Denver-based real estate brokerage Remingo. “Yes, prices are decreasing (but) they’re still higher than they were in 2020. And ’21 and ’22 were weird. They were bad. They were really expensive. But we don’t appear to be going into a huge regression. It might just be that we’re bouncing back out.”

The low interest rates in the past couple of years — between 2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} — are gone, with mortgage loan rates at 6.39{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, as of Friday, according to Mortgage News Daily. Buying a lower-median-priced home in Denver at today’s higher interest rate is nearly $300 more per month than last year’s higher-priced home at a lower interest rate according to Bankrate’s mortgage calculator. 

“The public has gotten very spoiled thinking they should get a 2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} or 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} interest rate. That’s not going to happen again,” Anderson said. “If you get down into 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, you’re getting a damn good interest rate. And 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} is actually very good.”

A home is listed for sale on Oct. 20, 2022 near Lookout Park in western Arvada. (Olivia Sun, The Colorado Sun via Report for America)

Buyers haven’t stopped buying houses in Colorado. 

Sunny Banka, who sells houses in Aurora and Centennial, blamed cold weather for keeping people from home shopping in March. But in April, she’s expecting different results. Shoppers have had a year to get used to higher interest rates. Currently in Aurora, there are 409 single family houses for sale and 418 with pending sales. 

“We are getting bidding wars,” said Banka, who has been a Realtor for 44 years. “A (colleague) put a $550,000 home on the market over the weekend and had 80 showings and 14 offers. It sold for about $30,000 over (the list price).”

The house must be priced right and in a good neighborhood, said Banka, whose clients are split between buyers and sellers. She said she has to educate them about what it takes to be in the housing market today. 

What’s also been helping? Relatives, she said. 

“What I’m seeing is there’s a lot of grandma, grandpa, great aunt money, mom and dad, who are helping with the down payment to help offset those higher interest rates for first-time homebuyers,” she said.


Denver inflation higher than the US

Higher housing, energy and food costs were reasons for the Denver-area’s 5.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} inflation rate increase in March from a year ago. This was higher than the national 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} rate, according to the U.S. Bureau of Labor Statistics, which does not track inflation rates by states. 

The good news for consumers is that this means prices aren’t rising as fast as they were last year. But this also means that consumer prices are still rising, and that’s on top of March 2022’s 9.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} increase. The top items that changed in price last month:

▲▲ Higher ▲▲  

  • Nonalcoholic beverages were up 16{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} 
  • Fruits and vegetables, up 14.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} 
  • Dairy and related products, up 12.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}
  • Rent of primary residence, 10.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}
  • Food away from home, up 10.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}
  • Owners’ equivalent of rent, up 7.8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}
Health and wellness manager Jennifer Pham, right, and project manager Joan Deming, place fresh fruits and vegetables out on shelves before shoppers arrive at the Clayton Cares Market on the Clayton Early Learning campus in Denver. (Kathryn Scott, Special to The Colorado Sun)

▼▼ Lower ▼▼

  • Used cars and trucks, down 11.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}
  • Gasoline, all types, down 2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}
  • Electricity, down 2.9{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}
  • Medical care, down 0.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}

You may not have noticed the increases because we had experienced much higher inflation last year, when the Denver-area rate hit 9.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in March 2022. That jump from the Federal Reserve goal of 2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}-3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} seems to make the latest increase less of a shocker.

“We’re still accelerating fast, just not accelerating as fast as we were a few months ago,” said Joe Craig, interim faculty director for the University of Colorado Colorado Springs Economic Forum. “That’s hard for consumers to notice. I would posit that a lot of consumers are still thinking, ‘Oh my god, prices are still going up. Why is the Fed still doing this? They’re slowing down our economy.’ Yes. But not at the same rate, which is a hard concept to get across and a hard concept to feel because we’ve been anchored to that 2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.”

Inflation hits lower-income households much harder than the better off. When the price of a dozen eggs or a gallon of gasoline increases, everyone pays the same amount. 

Higher inflation here “probably is just indicative of the fact that Denver is wealthier on average than the West as a whole and the nation,” Craig said. “The higher income brackets are still continuing to spend and that’s probably what we’re seeing with higher inflation in Denver. It is unfortunate though for the working class of Denver, but there’s always a tension like that in popular big cities.”

Looking at core inflation of the past two months, however, points to a more regional impact, said Brian Lewandowski, executive director of the Business Research Division at the Leeds School of Business, University of Colorado Boulder. Remove the volatile pieces like food and energy prices and Denver’s core inflation was at 5.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, or the same as the nation’s.

“I think the difference is really that the supply issue that we had was a more local phenomenon that drove up fuel prices locally,” he said. “I would expect that to come down because our prices are now coming down pretty quickly. … And on the housing front, we’re still leading the nation down in terms of (Federal Housing Finance Agency) home price index. I think we’re actually going to see the Denver metro region normalize with the U.S. as we progress through the year, perhaps even lower than the U.S.”

➔ Hmm… gas prices are up again. According to the AAA gas price tracker, Colorado’s average price for a gallon of regular gas was $3.57 on Friday, up 11 cents from last week and down 32 cents from a month ago. US prices also went up by 8 cents in a week. AAA’s explanation? “The main culprit is the high cost of oil, gasoline’s main ingredient, which is hovering in the low $80s per barrel. The national average has risen daily since March 29.” >> See gas prices

How it’s going for some Sun readers

Sun readers seem to be doing OK. Roughly 40{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} responded to last week’s reader poll that their household budgets are the same as last year, though half of that group said it’s because things cost more so they’re buying less but spending the same amount.

Nearly half of respondents feel that the economy’s impact on their life is more or less the same as last year.

Kristiana Huitrón, from Colorado Springs, said that helping her adult children has added to her budget. “I wish my adult children could get jobs that cover medical insurance and retirement and that paid them a wage that would sustain them over their lifetimes,” she wrote.

Cutting down on eating out was the top expense cut from household budgets. The second? Cable TV and other traditional paid-TV services. “Not paying for satellite was the best decision ever,” wrote a person from Arvada. 

On the other hand, Laurence Slivon from Durango didn’t mind paying more for Starlink, the satellite internet service, and for streaming video services. Slivon, who said he’s retired, is ready to splurge. He picked the “Haven’t cut anything” option in the poll.

After an initial big purchase on an electric vehicle, Louisville resident George Burson said he cut out gasoline, which used to set him back about $50 a month. “Since we have solar panels, my electric bill didn’t go up when we got the EV,” he wrote. “I’m adding more solar panels both for the environment and to keep the electric bill down.”

Thanks to everyone who participated in last week’s reader poll. Here’s the next one:

Take the poll: Housing


Other working bits

➔ Denver-based unicorn is now called Guild. Access to higher education has helped employees at Walmart, Disney, Chipotle and others get ahead thanks to their partner Guild Education, the Denver company valued above $1 billion based on venture investment. Now Guild has dropped the second part of its name to bolster their career advancement at those companies. A goal is to offer workers more opportunities and help employers retain staff. CEO Rachel Romer said in a statement, “We are building a movement that lifts up the moral imperative to accelerate access to opportunity for America’s workforce.” >> More from Guild 

➔ Law bans deceptive solicitations for business fees. If you paid more than $1 to register a trade name in Colorado, you paid too much. And now anyone behind deceptive marketing practices to trick businesses into paying “exorbitant costs” could face penalties of up to $20,000 for each violation, according to Senate Bill 37, which was signed into law by Gov. Jared Polis on April 11. The Colorado Secretary of State’s office handles new business formations, change of ownership and other business filing requirements online and probably at a cost lower than you’d think. >> See list of Colorado’s business fees

➔ Colorado mission-driven funds get $30.7 million. Community Development Financial Institutions, often the only financial lender in a community that works with low- and moderate-income clients who traditional banks often won’t consider, received a $1.73 billion boost from the U.S. Treasury Department. Nine are in Colorado and received a total of $30.7 million. That includes First Southwest Bank in Alamosa. Bank CEO Kent Curtis said that First Southwest plans to use the funds to support new loan programs, such as one that will help rural water distribution systems in low-income areas in southwestern Colorado and the San Luis Valley. Here’s the list of Colorado recipients:  

  • Colorado Enterprise Fund, Inc., in Denver, $3,718,258
  • Community Choice Credit Union, in Commerce City, $2,478,839 
  • Community Enterprise Development Services in Aurora, $955,179 
  • First SouthWest Bancorporation in Alamosa, $4,957,678 
  • Impact Development Fund in Loveland, $3,718,258
  • Mercy Community Capital in Denver, $2,478,839 
  • Native American Bank in Denver, $4,957,678
  • NuVista Federal Credit Union in Montrose, $3,718,258
  • Oweesta Corporation in Longmont, $3,718,258

Thanks for sticking with me for this week’s report. As always, share your 2 cents on how the economy is keeping you down or helping you up at cosun.co/heyww. ~ tamara 

Don’t miss the free weekly newsletter on Colorado jobs and unemployment. Sign up: ColoradoSun.com/working

Miss a column? Catch up:

What’s Working is a Colorado Sun column about surviving in today’s economy. Email tamara@coloradosun.com with stories, tips or questions. Read the archive, ask a question at cosun.co/heyww and don’t miss the next one by signing up at coloradosun.com/getww. 

Support this newsletter and get Colorado economic news weekly. coloradosun.com/join 
Commercial real estate market could crash soon. Here’s why

Commercial real estate market could crash soon. Here’s why

The business real estate sector may perhaps be headed for a crash that rivals the 2008 economic disaster this yr.

Workplace and retail house valuations could plummet as significantly as 40{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from peak to trough this 12 months as higher curiosity costs make it more challenging for investors to refinance trillions in looming credit card debt, according to Lisa Shalett, main investment decision officer for Morgan Stanley Prosperity Administration.

“MS & Co. analysts forecast a peak-to-trough CRE price drop of as considerably as 40{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, even worse than in the Fantastic Financial Crisis,” Shalett wrote in a weekly investment observe. “Additional than 50{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of the $2.9 trillion in industrial home loans will have to have to be renegotiated in the following 24 months when new lending charges are most likely to be up by 350 to 450 basis points.”

Complicating the subject is the point that compact and regional financial institutions are the biggest source of credit history to the $20 trillion industrial genuine estate current market, keeping about 80{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of the sector’s excellent debt. Regional financial institutions are at the epicenter of the upheaval within just the money sector, and there are worries that the turmoil could make lending expectations drastically far more restrictive.

HOW THE BANKING Disaster COULD HAMMER Smaller Businesses

Amazon HQ2 park campus in Arlington, Virginia

The Amazon HQ2 Fulfilled Park campus in Arlington, Virginia, April 3, 2023. (Nathan Howard / Bloomberg by way of Getty Images / Getty Pictures)

Throughout a credit crunch, financial institutions drastically elevate their lending benchmarks, generating it challenging for firms or households to get loans. Borrowers may possibly have to concur to much more stringent conditions like significant desire charges as banking companies test to reduce the fiscal chance on their close.

Banks were being currently tightening lending requirements right before the disaster inside of the field began. A quarterly survey of mortgage officers posted by the Fed confirmed that a expanding number of banking companies tightened lending benchmarks and saw reduced need in the ultimate 3 months of 2022.

JAMIE DIMON WARNS BANKING Crisis HAS Raised ODDS OF Economic downturn

“Refinancing risks are front and middle” for professional home entrepreneurs, a individual Morgan Stanley take note mentioned. “The maturity wall in this article is front-loaded. So are the involved challenges.”

Even prior to the collapse of Silicon Valley Financial institution and Signature Financial institution in early March, the professional genuine estate market place was struggling with a range of difficulties, such as increased desire rates and waning demand for workplace area as more providers enable personnel to perform from home.

Federal Reserve

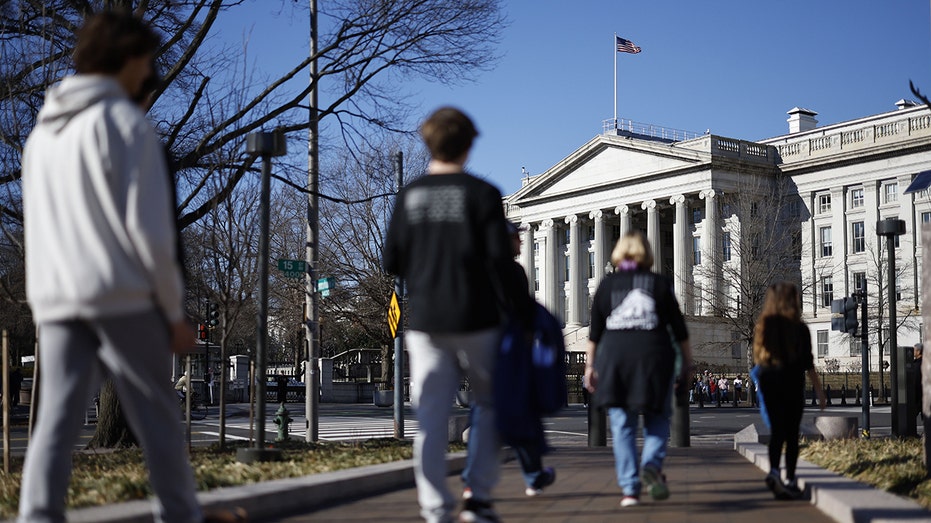
Pedestrians stroll in the vicinity of the U.S. Treasury Building in Washington, D.C., Dec. 30, 2022. (Ting Shen / Bloomberg through Getty Pictures / Getty Visuals)

“Industrial genuine estate, now dealing with headwinds from a shift to hybrid/distant get the job done, has to refinance much more than 50 percent of its mortgage credit card debt in the upcoming two many years,” Shalett wrote in a weekly report printed this week.

The Federal Reserve has raised fascination prices nine occasions from near zero to upwards of 4.75{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, and it is predicted to approve a 10th fee hike for the duration of its next conference that is scheduled for May perhaps 2-3. It is the steepest leap in borrowing expenses since the 1980s.

Still, other people are fewer pessimistic about the future of the commercial true estate market. Solita Marcelli, UBS World Wealth Management chief financial investment officer of Americas, claimed the headlines with regards to business office house “are even worse than fact.”

Simply click Here TO Study Extra ON FOX Business enterprise

“An anticipated credit score crunch on the back again of climbing expense of funding for banking institutions may perhaps further more compound its problems,” Marcelli stated in a be aware. But she additional, “We do not consider a repeat of the 2008 liquidity crisis is probably — exactly where capital markets essentially shut for funding.”

“In our perspective, the well being of the total banking system and market place liquidity disorders are substantially improved than they were being all through the [Great Financial Crisis].”

‘Attainable housing’ planned at Hines’ new Brazoria County community

‘Attainable housing’ planned at Hines’ new Brazoria County community

In an endeavor to construct what it phone calls attainable housing, real estate powerhouse Hines plans to establish 2,100 houses on virtually 1,000 acres in Brazoria County. 

The task comprises 954 acres that Houston-centered Hines and its lover,  Canada-centered serious estate organization Trez Capital, not long ago acquired in Iowa Colony, about 30 miles south of Houston. The land is off Texas 288 near the prepared extension of the Grand Parkway, which would connect the far south suburbs.

Attainable housing, according to the industry’s conventional definition, is inexpensive for households making the area’s median cash flow. Household charges at the community are anticipated to range from the $300,000s to over $700,000, in accordance to Hines. That signifies the rates of some properties would very likely place them beyond “attainable.”

Similar: Houston dwelling product sales tumble 18{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in March

It wasn’t straight away apparent no matter if the firm was referring to the median profits of Iowa Colony, Brazoria County or the Houston spot. The median income in Brazoria County, in accordance to the Census Bureau, is extra than $87,000, while that of Harris County is about $65,000.

In the Houston spot, a house desired to make about $94,000 each year to afford to pay for regular payments on a $337,900 median-priced dwelling at the conclude of previous 12 months, in accordance to an estimate by Houston Affiliation of Realtors.

The ordinary house value in Iowa Colony is about $427,000, somewhat above the Houston area’s normal dwelling cost of $408,647, according to HAR.

“As Houston proceeds to be a major employment hub in the Southwest, coupled with a supply-constrained sector and swift in-migration, the need to have for attainable housing remains important,” mentioned Carson Nunnelly, controlling director at Hines. “With wonderful colleges in a key site, this undertaking will be vital in furnishing much more homebuying prospects in Brazoria County.”

Hines expects to crack ground on the group, which does not nonetheless have a title, in the second quarter of 2023. To begin with, Hines strategies to total 400 tons by 2024, and it expects homes to be available by early 2025.

The neighborhood would be Hines’ initial residential undertaking in Brazoria County, wherever the populace has grown by just about 21 {515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} considering the fact that 2010 to practically 379,000 in 2021, in accordance to census data.

The job would increase just 5 miles south of the learn-prepared local community Meridiana, which has appeared on countrywide lists of the 50 greatest-advertising grasp-planned communities. About 400 homes have been marketed in Meridiana in 2022, in accordance to the actual estate consulting firm RCLCO.

PODCAST: What to anticipate in Houston’s shifting housing sector in 2023

Brazoria County has also attracted developers hoping to charm to residents wanting to rent one-spouse and children properties. Past 12 months, a newly shaped household arm of Houston-based Clay Growth unveiled strategies for a 97-house group of single-family rental properties in Iowa Colony anticipated to be accessible this spring. In the meantime, true estate business Wan Bridge, also based in Houston, declared an 812-household single-loved ones rental community in Bonney, about 30 miles south of downtown Houston.

The Iowa Colony task would be Hines’ greatest whole lot improvement challenge in Houston because Initial Colony, a 9,700-acre learn-prepared group in Sugar Land, the enterprise reported.

Planned in the Alvin Independent Faculty District, the Iowa Colony group is envisioned to offer parks, climbing and biking trails, and, in potential phases, a pool, playground and clubhouse.

Hines has partnered with Trez Money for a number of jobs across the Southwest in new yrs, together with Somerset Environmentally friendly, Laurel Glen, Grayson Woods, Raburn Reserve in Houston and the not too long ago announced Brookewater master-prepared group in Rosenberg.

“We are robust believers in the extended-term development of Texas,” said John Hutchinson, vice chairman and worldwide head of origination at Trez Money. “We proceed to see the require for more housing in Houston and throughout the condition and will proceed to operate with robust developers like Hines to meet the escalating long term desire for household real estate throughout the point out.” 

Derek Graber with Dosch Marshall represented Hines in the land obtain, when David Cook dinner and Meredith Cullen with Cushman Wakefield represented the seller. The project was financed by Flagstar Lender and Rocky Lai Associates.

marissa.luck@chron.com

Homes for Sale in Brooklyn and Manhattan

Homes for Sale in Brooklyn and Manhattan

Manhattan | 234 West 148th Street, No. 2B

A 1-bedroom, a person-bathtub, 743-sq.-foot condominium with an entry closet, an open kitchen and dwelling region with a dishwasher and wine fridge, a bedroom with two closets, a washer dryer, dual-zone heating and air-conditioning, and a 650-sq.-foot terrace, on the next ground of a 7-tale making with a online video intercom, gymnasium, residents’ lounge and bicycle place. Heather Cella and Lauren Schaffer, The Company, 845-641-7790 theagencyre.com

Prices

Common prices: $728 a thirty day period
Taxes: $49 a thirty day period (abated)

Execs

The huge terrace is a good element. The ground-flooring parking garage gives bargains to residents. The 421a tax abatement operates as a result of Dec. 31, 2028.

Cons

There aren’t quite a few home windows in the condominium, and although the terrace is big, it doesn’t have a lot of a perspective.

Manhattan | 200 East 59th Road, No. 10B

A just one-bed room, 1-and-a-fifty percent-bathtub, 835-square-foot apartment with an entry closet an open kitchen area and residing location with a dishwasher, wine fridge and rubbish disposal a bedroom with two closets and a windowed en suite bath with a rain shower and heated floors a 144-square-foot terrace 10-foot ceilings motorized window shades twin-zone heating and air-conditioning and a washer dryer, on the 10th flooring of a 35-story doorman making with a gymnasium, residents’ lounge with terrace, catering kitchen, concierge, bicycle space and storage models. Kathryn Neugold and Hannah Morris, Douglas Elliman, 203-470-5335 elliman.com

Prices

Prevalent expenses: $1,427 a thirty day period
Taxes: $1,508 a month

Pros

Alongside with a perspective of Midtown, the terrace has a drinking water spigot and an electrical outlet. There is no cost to use the residents’ lounge for private events.

Downsides

Storage models price $25,000 to $70,000 each individual. There is no bathtub in the apartment.


Brooklyn | 60 Pineapple Avenue, No. 4H

A one-bed room, two-bath, roughly 1,200-sq.-foot apartment with two corridor closets a kitchen with a double oven, wine fridge and dishwasher a 30-foot dwelling and dining spot a principal bedroom with two double closets a windowless den location motorized window shades and a deeded storage unit, on the fourth ground of an 8-story 1899 building with a element-time doorman, are living-in superintendent, porters, bicycle storage, laundry and deal rooms, and a different entrance ramp. Peter Gumas, Berkshire Hathaway HomeServices, 917-601-3685 bhhsnyproperties.com

Costs

Widespread costs: $2,089 a thirty day period

Professionals

There are loads of closets. The bed room matches a California king mattress.

Disadvantages

The den and the bathrooms do not have windows. There’s no washer and dryer bundled, even though they are permitted.

Offered the fast rate of the present current market, some houses may no lengthier be readily available at the time of publication.

For weekly electronic mail updates on residential authentic estate information, indicator up below.

The Housing Market Is Confusing the Top Real-Estate Forecasters

The Housing Market Is Confusing the Top Real-Estate Forecasters
  • Major forecasters are divided on the housing sector outlook for 2023.
  • Zillow economists be expecting household charges to increase about the subsequent calendar year, while these at Moody’s see the opposite.
  • Here is how leading genuine-estate forecasters be expecting dwelling costs to change this year.

The housing industry has despatched mixed signals these days, and that’s left the authentic-estate forecasters torn on what comes future for property selling prices.

In reality, household prices are slipping and mounting concurrently, relying on the place you seem, with declines in the West and gains in the South and East.

In which the housing market place goes from here mostly depends on the Fed’s trajectory on desire charges, which affect home finance loan fees. Very last month’s monetary turmoil that began with Silicon Valley Bank has led analysts to forecast that a pause or reduce in level hikes could be looming. 

Here’s how best companies assume household prices to go in 2023. 

Zillow: Household selling prices will increase

Primarily based on the Zillow Household Benefit Index, analysts forecast that household charges will boost .5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from January 2023 to January 2024. 

Skylar Olsen, Zillow’s chief economist, instructed Insider at a reporter roundtable very last 7 days that the lack of inventory helps make it tough to anticipate value declines.

“We won’t be able to guarantee that dwelling selling prices will go on to fall simply because the inventory is not there to make it possible for that to transpire,” she stated. “I definitely will not know exactly where the stock comes from to aid rates occur down.”

CoreLogic: Dwelling selling prices will increase

Immediately after 7 consecutive months of declines, the CoreLogic Residence Selling price Index confirmed a .8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} sequential rise in February, and the firm’s main economist claimed very last week that pent-up homebuyer demand together with declining prices has pushed Us residents again into the current market.

By February 2024, CoreLogic expects residence selling prices to increase yr about yr by 3.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. 

Moody’s Analytics: House selling prices will fall

The firm’s economists count on house prices — as calculated by Moody’s Analytics Repeat Profits House Cost Index — to tumble 4.2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} amongst December 2022 and December 2023. 

“Probably boosts in unemployment and a US recession later this yr will moreover stress product sales and rates,” analysts from Moody’s Traders assistance wrote in a report early this month.

Countrywide Affiliation of Realtors: Household costs will rise

In a report published in March, the NAR forecasted that current home prices will see a 1.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} climb by the initial quarter of 2024, and new dwelling prices will see a 2.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} boost for the exact same period of time. 

Nadia Evangelou, senior economist and director of forecasting at the NAR, explained to Insider final month that the banking crisis could guide to property finance loan costs slipping faster than expected, which could in the end guide to a lot more customers entering the sector.

National home prices just bottomed out, says real estate data juggernaut CoreLogic

National home prices just bottomed out, says real estate data juggernaut CoreLogic

Suitable out of the gate this yr, it was clear that the U.S. housing market—which saw a historic decline in household gross sales in the second fifty percent of 2022—was no longer in cost-free-drop method. The marketplace stabilized around January through a blend of improved consumer assurance, tight source, and slight declines in dwelling charges/home finance loan rates doing just sufficient to make improvements to affordability.

Quick-forward to April, and it’s searching like the housing market place has not just stabilized—it may well be returning to advancement method. At the very least that is according to CoreLogic.

After 7 consecutive months of home value declines, the CoreLogic Property Price Index detected a .8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} residence selling price uptick in February.

Situation-Shiller, the gold conventional for home selling price readings, won’t report its February reading until finally April 25. Even so, CoreLogic doesn’t really feel obligated to wait around for the Case-Shiller studying: The Irvine, Calif.–based authentic estate knowledge agency is all set to call the national property price tag base.

“U.S. household charges rose by .8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in February, double the thirty day period-above-month raise traditionally observed and indicating that prices in most marketplaces have by now bottomed out,” writes Selma Hepp, main economist for CoreLogic. “But when housing market troubles stay, significantly in gentle of house loan level volatility and the ongoing banking turmoil, pent-up homebuyer demand from customers is responding favorably to reduce charges in many markets.”

Heading forward, CoreLogic’s forecast product expects U.S. property selling prices to rise 3.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} amongst February 2023 and February 2024. For viewpoint, that’d be just a hair beneath the 4.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} return house charges have averaged per year because 1987.

Maintain in brain, even if national home selling prices have bottomed, it will not suggest each individual market will be insulated. In individual, frothy zoomtowns like Austin and Boise could be susceptible to corrections in the next 50 percent of 2023 if costs keep on being elevated and inventory starts climbing swiftly again as the hectic spring time concludes.

“The divergence in residence cost changes throughout the U.S. displays a tale of two housing markets. Declines in the West are due to the tech field slowdown and a extreme lack of affordability after decades of undersupply. The regular gains in the Southeast and South mirror powerful work markets, in-migration patterns and relative affordability because of to new home development,” writes Hepp.

Not anyone agrees with CoreLogic.

In specific, firms like Fannie Mae and Moody’s Analytics think dwelling costs will drop this calendar year. Heading ahead, both of those firms’ respective forecast designs have U.S. property costs slipping 4.2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} involving the fourth quarter of 2022 and the fourth quarter of 2023. The explanation? Spiked home finance loan prices coupled with the Pandemic Housing Boom’s operate on property rates has merely pushed affordability as well considerably beyond fundamentals.

Newsletter-Yellow-Line-15

Hungry for extra housing info? Follow me on Twitter at @NewsLambert.

Subscribe to Well Modified, our newsletter entire of easy approaches to do the job smarter and stay much better, from the Fortune Effectively staff. Signal up these days.