Evaluate ULA, a so-termed Mansion Tax in Los Angeles, has been eco-friendly-lit by practically 58{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} per cent of the city’s voters in a referendum this month, regardless of remaining panned by many in the real estate marketplace.
Critics in the market have argued that Los Angeles people are already around taxed, and that the evaluate will be an additional weight on the current market and won’t fix the really issue it’s making an attempt to tackle.
The evaluate, which was on the Nov. 8 ballot, is anticipated to generate an believed $900 million a yr to support homeless folks in Los Angeles by rising the transfer tax on significant-conclude property sales in excess of $5 million commencing in April 2023.
The tax level, generally paid by the seller, will be 4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} for homes valued at more than $5 million but below $10 million and will jump to 5.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} for houses valued at $10 million and earlier mentioned. A home owner promoting a $10 million assets, for illustration, would be on the hook for $550,000 in more taxes on the sale.
As of Nov. 25, there are 511,720 “yes” votes vs. 374,099 “no” votes for the measure, in accordance to knowledge from the county.
“Having been a resident of Los Angeles for more than 50 years, I have witnessed the city produce and evolve in the course of many social actions, changes of management and proposals for bettering our way of everyday living,” explained Sally Forster Jones, an agent with Compass. “We all concur that there requires to be a way to assist the unsheltered in discovering households and to reduce the difficulty of homelessness. Evaluate ULA is basically not the option to achieving this frequent aim.”
The measure, she claimed, will negatively affect all stages and price tag factors of the market, from renters to home owners to landlords, and discourage growth at a time when the city is previously struggling with a lack of inventory.
“We need to have a far better system that does not exacerbate the housing scarcity even though trying to reduce the difficulty of homelessness,” she stated. “We must not agitate just one situation in an attempt to minimize an additional. Evaluate ULA will possible even make both of those troubles worse.”
The funds raised by the transfer tax are aimed at lessening homelessness, producing housing far more reasonably priced and protecting very low-revenue seniors from shedding their homes. It will be carried out “with potent citizen oversight from unbiased homelessness experts who know what works—not politicians,” according to United To Dwelling LA, the team that backed the measure.
Having said that the initiative “could have a considerable and perhaps detrimental impression on the [Los Angeles] housing market place and our area financial system,” Jon Grauman, of the Grauman Rosenfeld Team at The Company, said in an e mail.
“While we are all sympathetic to the dire homeless difficulty that exists in L.A., taxing the wealthiest residents in a city that is arguably currently over-taxed—thereby leading to several persons to leave the state—is not the option,” he mentioned.
Los Angeles currently ranks as a person of the prime metropolitan places that community citizens are searching to go away, bested only by San Francisco, in accordance to Oct migration data from residence portal Redfin.
The info confirmed that one fifth, or 20{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, of local citizens working with Redfin’s residence research had been on the lookout at households outside of Los Angeles.
Even further criticism came in the sort of the city’s expending report, argued Ari Afshar of Compass.
Los Angeles “needs to get a better handle on how it is paying the billions already devoted to solving the homeless disaster,” he stated.
“Between Measure H and Project Roomkey, all Angelenos have been taxed to support the initiatives and nevertheless there’s practically nothing to demonstrate for [it],” he reported, referring to two other initiatives in spot to deliver homelessness companies in the town. “Get to the bottom of the reckless expending, sharpen the pencils and really do what we were explained to would be done. No a person demands to be taxed additional to have a lot more Angeleno bucks squandered.”
(WXYZ) — A warning has been issued to female actual estate agents about a male who could be a danger.
Realtor Amy Stack with Prosper Realty Organization claimed by and large, most interactions with potential consumers and sellers are very little out of the everyday. Nevertheless a few weeks back, she said she experienced a odd interaction with a male who observed her information on the internet.
“Unfortunately, it will come with the territory of currently being a woman agent,” Stack said.
She said she experienced again-to-back missed cell phone calls from the guy who claimed he wished to provide a warehouse he owns with his mom in Detroit.
“First detail he remarked on was that he observed me on-line, saw my photograph and that he knew that I could get the job done,” Stack recalled.
When she returned the phone, Stack claimed purple flags popped up one particular after a further.
“He had claimed he required to choose me purchasing and to church,” she said. “I understood at that level that like I just need to get this man off the cellular phone and say whichever he wanted to hear, so I could then block his number.”
She reported she ran a background check out on the man by applying an app known as Forewarn. She claimed she takes advantage of it routinely.
“He experienced a good deal of frightening rates that are brought up,” Stack stated.
The man is a registered intercourse offender with the very first offense in 2003.
Realtor Rachel Blue with Elite Realty mentioned her discussion with the person also begun on the phone. She obtained the phone in August.
“He asked if I wanted to come glance at the making. I stated, ‘Sure that’s great.’ And then he claimed, ‘Are you heading to bring any person?’ That was my purple flag,” she recalled.
“And I reported, ‘Yes, I’m likely to deliver my photographer to take some photos.’ (He replied,) ‘You do not will need to mainly because I previously have photographs,'” Blue ongoing.
She mentioned he instructed her make sure to put on designer boots. The instances he arrived to the business, she was not there. However, he remaining voicemails that 7 Action News listened to. In 1 of them, he was irritated she hadn’t return his simply call.
Blue said she seemed thoroughly and could not uncover the house the person claimed to individual.
A short while ago, an corporation termed Realcomp set out this internal bulletin for realtors, as well as the Larger Metropolitan Realtors Association, to beware of a sexual intercourse offender behaving surprisingly towards feminine realtors.
“And I was like, ‘Oh, this is the man,'” Stack recalled her reaction.
Blue recalled, “It was actually stunning.”
“It’s form of sad that an individual does this to 14 men and women and you will find no consequences,” Stack mentioned.
Blue claimed, “Personally, it was not like a legislation enforcement issue for me. It was type of like an awareness.”
She claimed she carries hid and that brokers are inspired to get a self-defense program.
Blue claimed, “I have an app on my phone exactly where my loved ones is aware of exactly where I am going. Just about every time I go to showings, I send my place out (declaring), ‘Hey, this is exactly where I am heading.’ If I stress about it, I attempt and take somebody with me. Even with women… it will not subject, male (or) female, you want to consider the exact same safeguards.”
Nathan Boji, president of the Larger Metropolitan Association of Realtors said, “We are seriously adamant about educating on safety and fantastic industry practices.”
He stated September is Realtor Protection Month. Boji stated GMAR done courses for its 11,000 members on subject areas like situational recognition and self-protection techniques.
Also, techniques like parking on the avenue as an alternative of the driveway, not permitting another person get concerning you and the doorway were being mentioned, letting other individuals know if you have showings, and getting another person with you.
“We do get it really very seriously. We do converse about it all through the year,” Boji said.
Editor’s Be aware: Erik Lundh is a principal economist at The Meeting Board. The opinions expressed in this commentary are his individual. Browse far more impression at CNN.
A considerably-feared correction in US residence price ranges is underway. Though this may perhaps feel like déjà vu, the motorists powering the the latest spike in costs and the present-day housing current market downturn are diverse from the ones witnessed in the 2000s. This time all over, the US economic process is far better geared up, and a nationwide crisis is considerably less most likely.
Courtesy Evercore
It is legitimate that US owners should put together for an unattractive 2023. Immediately after decades of underinvestment and suppressed provide, US household rates rose an eye-popping 45{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in between January 2020 and June 2022, as small curiosity rates and the surge in distant operate spurred need. For comparison, in the lead-up to the housing downturn that began 16 several years in the past, prices ended up up by 30{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in excess of a equivalent period.
But the housing bubble in the 2000s was underpinned by predatory lending, poor underwriting, adjustable-price mortgages and rampant speculation. People have been confident that housing was a terrific small-expression investment and that prices would only keep on to increase. This famously turned out not to be the case.
As fascination costs rose leading into 2006, costs finally began to slide later on that 12 months, and householders started defaulting on their property finance loan payments. As costs fell additional, householders rushed to dump their attributes, developing a feed-back loop that cascaded all over the overall actual estate marketplace. The subsequent fiscal crisis was induced by mass defaults in low-high quality home loans that had been wrapped up in mortgage-backed securities. These belongings all of a sudden became close to-worthless, which threw the financial program into crisis.
On top of that, many years of rampant need spurred builders to overbuild in the early 2000s, flooding the nation with a residence surplus. As a outcome, subsequent the Terrific Recession, it took several years for demand from customers to work via the large housing inventory that had been amassed. This, in transform, crushed the homebuilding business, causing chronic underbuilding in excess of the subsequent many years.
Quickly forward to right now, and the circumstance is extremely distinct: Dwelling prices are slipping simply because the Federal Reserve is increasing fascination costs to quell inflation. This, in convert, has pushed property finance loan premiums larger. Whilst the ordinary fee on a 30-calendar year property finance loan fell sharply last week, it is even now additional than double what it was a year back (3.10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} a year in the past vs. 6.61{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} right now). These rates make financing new residence purchases unaffordable for quite a few potential buyers, so demand from customers is slowing and prices are slipping.
Thankfully, desire and provide fundamentals could restrict the draw back for US residence price ranges. Millennials, the major generational cohort since the baby boomers, have gotten older and are hunting to obtain their initially households. Regretably for them, there aren’t more than enough to go about. But this implies higher selling prices, even even though they are setting up to fall and will proceed to do so, will very likely be relatively sticky. In essence, demand from customers from Millennials will almost certainly enable preserve prices from moving into freefall – as was the case in 2008. It is extremely not likely this decrease would spark another fiscal crisis.
On top of that, in the several years that followed the 2008 money crisis, new rules were introduced. Banking companies are now required to be much better capitalized lending requirements are significantly extra demanding, leading to greater-good quality financial loans most mortgages are mounted-level and financial derivatives, such as asset-backed securities, are greater controlled. This all buttresses the money process from one more housing downturn.
Other valuable tendencies consist of the spike in refinancing exercise about the very last couple a long time connected with extremely-very low desire premiums. This pushed down regular payments for quite a few homeowners, earning servicing their home loans much easier.
Additionally, Individuals have more fairness in their homes than they did main up to the very last fiscal crisis. Without a doubt, personal loan-to-benefit ratios, which measure the amount of a home finance loan relative to the benefit of a house, for US home loans have fallen to just 42{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} – a 12-12 months minimal. This creates additional of a “cushion” for charges to decrease ahead of household values tumble down below the financial loans that underpin them. Thus, if a property is marketed at a loss, it’ll most likely strike home owners before it hits the banking institutions.
The ongoing housing cost correction will have implications for the US economy, but lower property rates should aid to quell significant inflation. It will certainly come at the expense of economic progress, as homebuilding activity is presently slowing rapidly and purchaser self esteem (and expending) will probably experience as nicely. But it is not likely we’re heading for a repeat of 2008.
Last year, Auckland’s largest real estate company couldn’t sell properties quickly enough to meet demand in New Zealand’s biggest city.
Houses were “flying out the door,” said Grant Sykes, a manager at real estate agency Barfoot & Thompson. “There were chin-dropping moments when agents stand around the room and are gobsmacked at the prices being achieved,” he told CNN Business.
In one example, a property sold for 1 million New Zealanddollars ($610,000) above the asking price in an auction that lasted all of eight minutes. (Most homes in New Zealand are sold at auction.)
That was in May 2021, when salesattracted thousands of bidders who drove prices ever higher. Since then, Barfoot & Thompson’s clearance rate at auction has plummeted, according to Sykes, prolonging sales times and sending prices lower.
The time it takes to sell a property in New Zealand has increased by around 10 days on average since October 2021, according to the Real Estate Institute of New Zealand. Sales have plunged nearly 35{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} and median house prices are down 7.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} over the past year.
New Zealand is at the sharp end of a global housing market squeeze that has grim ramifications for the world economy.
The pandemic boom, which sent pricesinto the stratosphere, is running out of steam and house prices now are falling from Canada to China, setting the stage for the broadest housing market slowdown since the global financial crisis.
Rising interest rates are driving the dramatic change. Central banks on a warpath against inflation have taken rates to levels not seen for more than a decade, with ripple effects on the cost of borrowing.
US mortgage rates topped 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} last month for the first time since 2002, up from just over 3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} a year ago, before pulling back slightly in November as inflation eased. In the European Union and United Kingdom, mortgage rates have more than doubled since last year, chasing would-be buyers from the market.
“Overall, this is the most worrying housing market outlook since 2007-2008, with markets poised between the prospect of modest declines and much steeper ones of 15{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}-20{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502},” said Adam Slater, a lead economist at Oxford Economics, a consultancy.
One key factor determining how low prices go? Unemployment. A sharp increase in joblessness could lead to forced sales and foreclosures, “where steep discounts are common,” according to Slater.
But even if the correction in prices is mild, a housing market slowdown could have severe consequences because housing transactions in turn boost activity in other sectors of the economy.
“In an ideal world, you’ll get a bit of froth blown off the top [of house prices] and everything is fine. It isn’t impossible, but it’s more likely that housing downturns come with nastier consequences,” Slater told CNN Business.
House prices are already falling in more than half of the 18 advanced economies that Oxford Economics tracks, including the United Kingdom, Germany, Sweden, Australia and Canada, where prices dropped by around 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from February to August.
“Data lags probably mean that most markets are now seeing falling prices,” said Slater. “We’re in the early period in quite a clear downturn now and the only real question is how steep and how long it’s going to be.”
House prices in the United States — which rose during the pandemic by the most since the 1970s — are falling too. Economists at Goldman Sachs expect a decline of around 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}-10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from the peak reached in June through to March 2024.
In a “pessimistic” scenario, US prices could plunge as much as 20{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, Dallas Fed economist Enrique Martinez-Garcia wrote in a blog post recently.
Prices for new homes in China fell at the fastest pace in over seven years in October, according to official figures, reflecting a deepening property market slump that has gripped the country for months and is weighing heavily on its economy. Home sales have fallen by 43{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} this year, according to China Index Academy, a research firm.
Sales are sliding elsewhere too, as banks take a more cautious approach to lending and aspiring homebuyers delay purchases in the face of much higher borrowing costs and a deteriorating economic outlook.
House sales in Britain were 32{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} below the previous year’s level in September, according to official figures. A closely watched survey showed that new buyer inquiries fell for the sixth successive month in October to the lowest level since 2008, excluding the early months of 2020 when the market was largely shut because of the pandemic.
In the United States, sales of existing homes were down by more than 28{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} year-over-year in October, the ninth consecutive monthly decline, according to the National Association of Realtors.
Mortgage rates in 25 major cities around the world tracked by UBS have almost doubled on average since last year, making house purchases much less affordable.
“A skilled service sector worker can afford roughly one-third less housing space than before the pandemic,” according to the UBS Global Real Estate Bubble Index.
As well as putting off new buyers, the sharp increase in rates has shocked existing homeowners accustomed to more than a decade of ultra-low borrowing costs.
In Britain, more than 4 million mortgages have been issued to first-time buyers since 2009, when rates were near zero. “There’s a lot of people out there who don’t appreciate what it’s like when their monthly outgoings rise,” said Tom Bill, head of UK residential research at broker Knight Frank.
In countries with a larger share of variable rate mortgages, such as Sweden and Australia, the shock will be immediate and could increase the risk of forced sales that drive prices down faster.
But even in places where a large proportion of mortgages are fixed, such as New Zealand and the United Kingdom, the average maturity of these mortgages is quite short.
“This means much more debt will be subject to (often significantly) higher rates over the next year or so than might first appear to be the case,” Slater wrote in a report last month.
While interest rates have been the catalyst for the housing market slowdown, the jobs market will play a bigger role in determining how low prices ultimately plunge.
Modeling of past house price crashes by Oxford Economics shows that employment is the decisive factor in determining the severity of a downturn, because a spike in joblessness raises the number of forced sellers.
“History shows that if labor markets can remain strong, then the chances of a more benign correction are higher,” according to Innes McFee, chief global economist at Oxford Economics.
Employment levels in many advanced economies have recovered since falling at the start of the pandemic. But there are early signs that labor markets are starting to cool as weak economic growth hits demand for workers.
After recovering strongly at the beginning of the year, the number of hours worked was 1.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} below pre-pandemic levels in the third quarter, amounting to a deficit of 40 million full-time jobs, according to estimates by the International Labour Organization.
“The outlook for global labour markets has worsened in recent months and on current trends job vacancies will decline and global employment growth will deteriorate significantly in the final quarter of 2022,” the ILO said in an October report.
The unemployment rate in the United States ticked upwards in October to 3.7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. In the United Kingdom, job vacancies have fallen to the lowest level in a year. The UK Office for Budget Responsibility expects unemployment to rise by 505,000 to a peak of 1.7 million — an unemployment rate of 4.9{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} -— in the third quarter of 2024.
“A decisive increase in unemployment is a very big danger for housing markets,” said Slater of Oxford Economics.
Most market watchers are not expecting a repeat of the 2008 housing market crash. Banks and households are in better financial shape, and housing supply in some countries remains tight.
But even a modest a fall in house prices will knock confidence, causing homeowners to cut back on spending.
A slowdown in activity will also deal a blow to many other parts of the economy because of the housing market’s links to builders, lawyers, banks, moving companies and furniture stores, to name a few.
China’s property market accounts for about 28-30{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of GDP because of these linkages. In the United States, housing’s broader contribution to GDP generally averages 15-18{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, according to the National Association of Home Builders.
In a worst-case scenario — one in which house prices fall more sharply than anticipated and price declines are met with a slump in residential investment and tighter lending by banks —Oxford Economics forecasts that world GDP will expand by just 0.3{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2023, rather than the 1.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} it currently expects.
“An additional negative factor, compared to the [global financial crisis], is that the Chinese housing market is also in a downturn,” according to Slater. “So rather than offsetting the impact on world output of a global housing downturn, as was the case after the GFC, the Chinese housing sector is contributing to the slump.”
It is been a wild actual estate trip above the previous handful of a long time. Just after a pink-sizzling industry characterized by bidding wars, low curiosity rates, and elevated costs, house loan fees amplified to the greatest degree in 20 years, main to a slowdown of both of those obtaining exercise and purchase price ranges.
Still, with inventory however reduced, property price tags continue to be high, including in the Philadelphia area.
There are a lot of predictions about exactly where the housing sector is heading in 2023. But what about additional out? Following all, purchasing a residence usually calls for very long-time period setting up. We questioned several household serious estate professionals for a 5-year forecast of the housing sector. Here’s on the lookout at you, 2027.
But very first, a snapshot of the residential authentic estate scene nationally, as of autumn 2022.
Home sales value: The median existing-residence product sales price tag rose 8.4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from just one calendar year in the past, to $384,800, according to September 2022 facts from the Nationwide Affiliation of Realtors (NAR). For new residences, the current typical gross sales cost nationwide is $470,600 — up about 14{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from a year in the past, claims Danushka Nanayakkara-Skillington, assistant vice president, forecasting and evaluation for the Nationwide Affiliation of Homebuilders (NAHB).
Stock: Although greater than it was in January 2022, the provide of properties remains traditionally small, says Lawrence Yun, NAR chief economist and senior vice president of analysis. The stock of unsold existing houses was at a 3.2-month source in September 2022.
Days on the market place: With stock nevertheless restricted, residences keep on to offer promptly. In September 2022, the median quantity of days on the market for sold residences ranged from 13 to 23, relying on the value, in accordance to the September NAR info. In a far more regular sector, it is 45 times, Yun claims.
Houses bought: Much less existing residences are marketing nationwide. In accordance to the September NAR data, throughout 2022, the seasonally modified total determine dropped from 6.49 million in January to 4.71 million in September. In the meantime, revenue of new single-spouse and children residences in July 2022 have been at a seasonally altered once-a-year price of 511,000 — which is 29.6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} decrease than in July 2021, says the U.S. Census Bureau and the Office of Housing and Urban Development.
30-year home finance loan prices: According to Freddie Mac, as of Nov. 10, the latest average 30-12 months fixed mortgage fee was 7.08{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, the greatest it is been in 20 many years.
New dwelling starts off: In accordance to Nanayakkara-Skillington, the seasonally altered annual amount for new solitary-household household commences is 892,000, which is down 18.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} when compared with very last calendar year.
Home finance loan interest costs could proceed to boost for a couple weeks or months, suggests Yun, incorporating that 7{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} looks to be the level for the rest of this calendar year and most of up coming year. Within two decades, the level really should return to 5.5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} or 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, he adds. Nanayakkara-Skillington agrees, predicting that fees will drop to about 6{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} by the center of 2024.
Yun foresees no or slight modifications in acquire price tag tags on a nationwide foundation up coming year, with boosts or decreases of about 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. The only exception is California, he claims, in which the market place could see 10{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} declines: “Because it’s so costly, California is constantly the most vulnerable to alterations in interest fees.” Total, in 5 years, he expects charges to have appreciated a whole of 15{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} to 25{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.
Though it’s been demonstrating bubblelike houses, the residential true estate industry ought to not violently pop, Yun expects. While he predicts that gross sales will be at a reduced level future yr, with only 5.3 million units bought, he foresees a gradual improve afterward, up to an once-a-year six million models by 2027.
Regardless of the larger home loan charges, residence rates are nonetheless over what they ended up a person 12 months ago, he adds. Even if they decline 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} future 12 months, which is not near to crashing — which is characterized by a a single-third drop.
“A 30{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} decrease will not transpire since there is not sufficient stock,” he claims. “A crash comes about with oversupply.” He believes the housing lack will go on this yr, with the supply balancing out by five a long time.
Yun expects the seller’s industry to carry on, even though housing stock remains low. By 5 years, however, he foresees a balanced marketplace, exactly where neither the purchaser or seller holds sway. As a substitute, the negotiating electrical power involving get-togethers will be a lot more equal and depend on the unique situation.
Caroline Feeney, executive editor, HomeLight, feels the change away from a seller’s industry has currently begun. In accordance to a current survey the company done, only 51{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of HomeLight brokers described their recent community market place as a seller’s marketplace. She also expects a balanced industry inside a couple yrs.
With hybrid function schedules turning into the norm and commuting no lengthier as appropriate, Yun predicts that the suburban current market will keep on to be strong. Meanwhile, 55{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of leading HomeLight agents think the markets that heated up the fastest in the course of the pandemic (which includes Austin, Phoenix and Boise) are possible to be the initial to great down and see the biggest decreases for the duration of a marketplace correction, says Feeney. Yun expects expansion in parts with increasing populations, specifically the Carolinas, Florida, Texas and Tennessee. Backing up his prediction, 50{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of new single-loved ones construction is in the South, notes Nanayakkara-Skillington.
The quantity of single-spouse and children properties underneath construction has lessened over the last 4 months. In contrast, the selection of multifamily homes underneath development has enhanced about the past handful of years, states Feeney, who credits this advancement in portion to their decrease value tags — flats are likely to be cheaper than detached houses — and the stress on municipalities to decrease shortages and present far more very affordable housing.
Nonetheless, with significant house loan costs and inflationary setting up material selling prices, Nanayakkara-Skillington expects the multifamily market’s growth to stabilize in a handful of several years, with the variety of new commences decreasing 8{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2023, and a different 5{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in 2024.
China’s housing costs fell in October due mostly to slipping prices in a lot less created, so-termed Tier-3 metropolitan areas, in accordance to Goldman Sachs assessment of official facts.
Long run Publishing | Potential Publishing | Getty Images
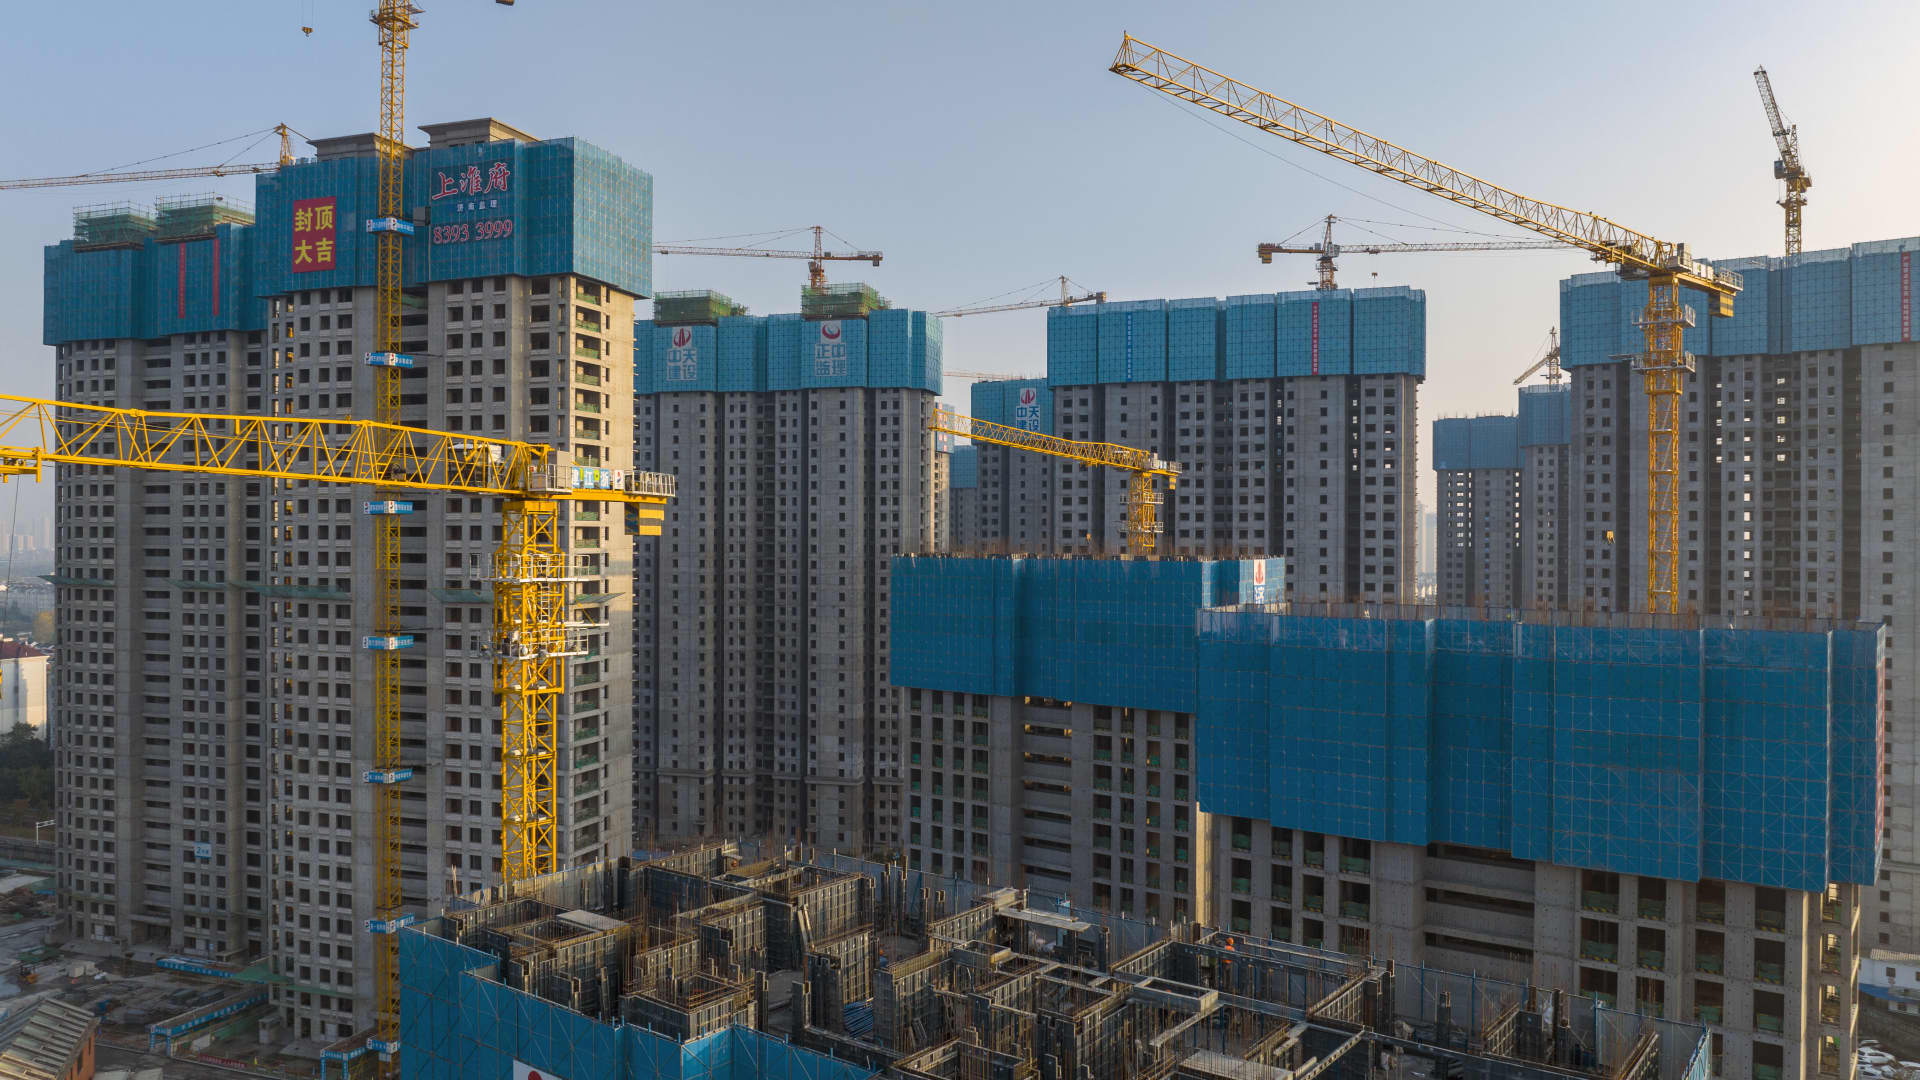
BEIJING — China’s actual estate sector is not but poised for a brief recovery, regardless of a rally this month in shares of significant property developers.
That is because current help by Beijing don’t directly solve the primary dilemma of falling home product sales and costs, analysts say.
Past 7 days, residence developer stocks surged after information the central lender and banking regulator issued measures that encouraged banking companies to help the actual estate marketplace. It will come together with other help actions before this month.
Shares of Country Backyard garden, the most significant Chinese developer by gross sales, have far more than doubled in November, and all those of Longfor have surged by about 90{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}. The stocks have now offered back again some of this month’s gains.
Meanwhile, iron ore futures surged by about 16{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} this month — Morgan Stanley analysts say about 40{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} of China’s steel use is applied in home building.
The problem is one of “solid expectations, but weak fact,” and marketplace rates have deviated from the fundamentals, Sheng Mingxing, ferrous metals analyst at Nanhua Study Institute, reported in Chinese translated by CNBC.
Sheng explained it truly is important to check out whether or not residences can be accomplished and delivered throughout the peak building time period of March and April.
This truly is a short-term reduction in phrases of the developers having to meet fewer debt repayment needs in the close to potential…
The new actions, widely noted in China but not officially released, stipulate bank loan extensions, connect with for dealing with developers the similar irrespective of whether they are point out-owned or not and aid bond issuance. Neither regulator responded to CNBC’s request for comment.
“This truly is a short term aid in phrases of the developers having to meet up with less financial debt compensation desires in the around upcoming — a non permanent liquidity reduction fairly than a fundamental turnaround,” Hong Kong-primarily based analyst Samuel Hui, director, Asia-Pacific corporates, Fitch Rankings, said Wednesday.
“The key is that we however have to have the essential underlying house product sales marketplace to increase,” he mentioned, noting homebuyer confidence depends on whether developers can complete constructing and delivering residences.
Earlier this calendar year, numerous homebuyers refused to continue on spending mortgages on flats when design was delayed. Properties in China are ordinarily sold in advance of completion, generating a main resource of income movement for builders.
A drawn-out recovery
Analysts vary on when China’s assets sector can recuperate.
Fitch explained a timeline “continues to be extremely uncertain,” though S&P Worldwide Ratings’ Senior Director Lawrence Lu expects a recovery could arise in the next 50 percent of following year.
“If this coverage is executed promptly, this will halt the downward spiral to the builders, this will aid to restore the investors’ self-confidence [in] the builders,” he mentioned.
Household housing income for the initially 10 months of the calendar year dropped by 28.2{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} from a yr ago, the National Bureau of Stats reported last 7 days. S&P World Ratings stated in July it expects a 30{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} plunge in product sales for 2022, worse than in 2008 when profits fell by about 20{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}.
A slowdown in economic advancement, uncertainty about ongoing Covid controls and problems about long run earnings have dampened urge for food for buying households.
Incorporating to people anxieties are falling costs.
Housing price ranges across 70 cities fell by 1.4{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in October from a year in the past, in accordance to Goldman Sachs investigation of data unveiled Wednesday.
“Despite much more local housing easing actions in recent months,” the analysts said, “we believe that the residence marketplaces in decreased-tier cities still confront solid headwinds from weaker expansion fundamentals than substantial towns, which includes web inhabitants outflows and opportunity oversupply complications.”
The report mentioned housing prices in the most significant, tier-1 cities rose by 3.1{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} in October from September, whilst Tier-3 metropolitan areas noticed a 3.9{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} drop through that time.
About two decades back, Beijing commenced to crack down on developers’ higher reliance on personal debt for expansion. The country’s most indebted developer, Evergrande, defaulted late previous 12 months in a substantial-profile financial debt crisis that rattled trader self esteem.
Concerns about other true estate companies’ skill to repay their debt have due to the fact unfold to when-wholesome developers.
Buying and selling in shares of Evergrande, Kaisa and Shimao is still suspended.
Go through much more about China from CNBC Professional
Even though Covid controls have dragged down China’s advancement this yr, the true estate market’s struggles have also contributed considerably.
The house sector, such as relevant industries, accounts for about a quarter of China’s GDP, in accordance to analyst estimates.
“I think the actual estate sector will grow to be lesser of a drag to the economic system in 2023,” Tommy Wu, senior China economist at Commerzbank AG, claimed Wednesday.
“It is also early to convey to whether the measures rolled out so much will be ample to rescue the serious estate sector,” he claimed. “But it feels additional assuring now due to the fact it seems extra probable that far more forceful steps will be rolled out if the real estate downturn nevertheless won’t convert around significant in the coming months.”
In the long run, China’s real estate field is undergoing a state-directed transformation — to a smaller sized component of the financial state and a company model much much less reliant on selling apartments prior to they’re concluded.
The property sector has shrunk by approximately one-third as opposed to last yr, and will possible remain the similar sizing up coming yr, S&P’s Lu claimed.
Point out-owned developers have fared much better during the downturn, he pointed out.
In the first three quarters of the yr, Lu said profits by state-owned builders fell by 25{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502}, in comparison to the 58{515baef3fee8ea94d67a98a2b336e0215adf67d225b0e21a4f5c9b13e8fbd502} profits drop for builders not owned by the point out.
And despite current coverage moves, Beijing’s stance continues to be organization in dissuading dwelling purchases at scale.
No matter whether it is messaging from the Countrywide Bureau of Studies or the People’s Financial institution of China, formal announcements this month reiterated that houses are for dwelling in, not speculation — the mantra that marked the early beginnings of the true estate market place slump.